

Call: NEUTRAL
This was a genuinely strong operating quarter with a headline that overstates how much of it is structural. Net sales grew 24% (20% constant-currency) with 47% operating-income growth and gross margin holding at 56.6% despite an oil-driven cost spike triggered by the Middle East conflict — real operating leverage, not accounting noise. But the segment-level price/volume/FX bridge in the 10-Q shows net pricing was essentially flat and roughly 19% of the sales increase was currency; volume did the rest, and a meaningful slice of that volume was a one-time promotional program (Disney/Home Depot limited-edition cans) and an explicitly acknowledged ~$3 million of demand pulled forward from Q4 into Q3 ahead of price increases and Middle East supply concerns. The “raised” FY26 guidance is mostly an accounting reclassification (the Americas homecare/cleaning brands moving from held-for-sale back into the guided base) layered on a genuine but modest operating raise — management itself confirmed on the call that the true operating raise was roughly +$1.1 million at the low end of operating income guidance with the high end essentially unchanged, while the gross-margin guide was simultaneously cut 100 bps at the midpoint (54.5-55.5% vs. 55.5-56.5% three months ago) on the same oil-cost pressure.
The stock’s own trading pattern tells the more interesting story: it gapped to a new 52-week high before giving back roughly 40% of the after-hours/opening gain intraday, consistent with the market starting to digest the gap between the 24% headline and the more modest underlying trajectory once the filing details were available. At $267.63 the stock trades at roughly 43x FY26 guidance-midpoint EPS — about 2x the peer-median multiple and above even our required-return hurdle math on a normalized exit multiple. The business is high-quality and the quarter was real, but the price already assumes both the quarter’s pace and the current multiple persist; that combination, next to a genuine near-term deceleration risk (implied Q4 growth of only ~5% at the guidance midpoint) and an unresolved CFO transition, argues for Neutral rather than chasing the print.
Position Verdict
A genuinely strong quarter got re-priced to a valuation that already assumes the strength repeats, while the print's own volume/price/FX bridge and implied Q4 guide show a meaningful share of Q3's growth was promotional or pulled forward rather than structural, leaving little room for even a normal-premium multiple outcome to clear a satisfying return.
Business Trajectory & Forward Estimates (1–3yr)
WD-40 is not a broken or decelerating business — the Enduring Business Model targets (mid-to-high-single-digit constant-currency sales growth, gross margin above 55%, Adjusted EBITDA growing faster than sales, >25% ROIC, asset-light) are credible given the brand’s history and this quarter’s real operating leverage. The disagreement with the market is about pace and durability at today’s multiple, not business quality.
1. Next-print estimates (Q4 FY26, reporting ~October 2026):
Next print (Q4 FY26)ConsensusOur rangeBasis for differenceNet sales$177.6M (avg; $173.1M-est. range)$168-176MManagement’s own full-year guide backs into Q4 revenue of only $163.8-178.8M (+0.2% to +9.4% YoY); consensus sits near the guide’s high end without full credit for the ~$3M explicitly-acknowledged Q3/Q4 pull-forwardNon-GAAP diluted EPS$1.65 (avg; $1.62-1.70 range)$1.52-1.65Gross-margin guide was cut 100bps at the midpoint (54.5-55.5% vs. 56.6% just posted) as lagged specialty-chemical/base-oil costs flow through inventory in Q4Q4 organic (ex-FX, ex-pull-forward) sales growth [swing KPI]not separately estimated by Streetmid-single digitsSecond derivative: decelerating sharply from Q3’s +24% (+20% cc) — the true read on how much of Q3 was structural
Our range sits at-or-below the low-to-mid of guidance and below Street consensus, which currently reads more like an extrapolation of Q3’s pace than a clean read of management’s own math.
2. FY+1/FY+2 path. FY26 (0y) consensus: revenue $668.9M avg (+7.9% YoY), EPS $6.01 avg — both still below the low end of the reported FY26 guide range ($675-690M / $6.05-6.35) because the consensus feed we captured had not yet fully re-rated in the hours after the print (eps_trend 0y: 6.0125 current vs. 5.99 at 90 days — essentially flat, confirming the lag). FY27 (+1y) consensus: revenue $715.6M avg (+7.0%), EPS $6.48 avg (+7.8%). We expect FY26 consensus EPS to move up ~3-5% over the next 1-2 weeks simply to catch up to the new guide midpoint ($6.20), but we expect FY27 consensus to face 2-4% downward pressure over the next two prints if Q4 confirms the growth deceleration and gross margin stays soft into fiscal 2027 — a “raise now on the headline, trim later on the base” pattern.
3. Three-way separation. Management’s framing: “operating leverage inherent in our business model,” a “second strongest quarter of the year” still to come in Q4, gross margins to be “vigorously defended.” Consensus: still catching up mechanically to the new range, implicitly underwriting continued high-teens-plus growth into Q4. Our path: Q4 revenue and EPS below-to-in-line with guidance (not above), FY27 organic growth closer to the historical mid-single-digit algorithm than to Q3’s rate, and gross margin recovery in FY27 back-half-weighted and uncertain in pace — the CFO herself would not commit to a cadence (”it is hard... to comment on that at this point in time”).
External anchors (required): (1) WTI crude spiked into the $95-115/bbl range management assumed in April guidance, then fell back to ~$69-70/bbl by late June 2026 as Strait of Hormuz shipping resumed (CNBC, Al Jazeera) — but WD-40’s own June input-cost pullback was only 20-25%, well behind the 40%+ spike, confirming management’s inventory-lag mechanic rather than an early margin-relief signal. (2) Clorox’s Q2 FY26 print (same calendar window) explicitly cited “shipments ahead of consumption” — i.e., its own channel pull-forward — alongside higher manufacturing/logistics costs, while Church & Dwight flagged inflation/tariff drag on margin; this is a sector-wide, not WD-40-specific, phenomenon this cycle, which corroborates rather than dismisses the pull-forward read.
Earnings power in ~3 years: on the base case, WD-40 compounds toward roughly $8+ in EPS by FY29 (high-single-digit CAGR off the FY26 base) — a legitimate, high-quality compounder consistent with the new Enduring Business Model targets. It is not, on our numbers, a business that needs to compound at Q3’s 24% pace to be worth owning — which is exactly the gap with today’s price (Section B).
Trajectory falsifier (external): a renewed spike or sustained elevation in WTI/specialty-chemical spot prices (e.g., a Strait of Hormuz re-escalation) through Q4 FY26 and into FY27 would break management’s “temporary pressure, FY27 recovery” framing and the gross-margin guide itself — this is the single monitorable external series that would move the call in either direction.
What’s Priced In vs. Our View (Variant Perception)
What the price requires (Section 5): holding our base-case FY29E EPS path, the current $267.63 needs an exit multiple of ~42x just to clear a 10% annual return and ~48x to clear 15% — both above our 33-38x deserved range and above the stock’s own historical multiple ceiling in a normal (non-post-beat) year. Even our bull-case EPS path does not clear a 10% return at a normalized 35x multiple (Section 5, “what the price is paying for”). Our trajectory view (Section A) is a real but ordinary mid-to-high-single-digit compounder, not a business whose growth rate just structurally re-rated to 20%+.
Divergent — the price is ahead of the trajectory. This should be a Neutral-to-cautious stock, not a fresh long.
Why the mispricing can persist, and why it may not persist long: the mechanism is headline/optics obscuring the underlying pace — a 24%-growth, 47%-operating-income-growth, “guidance raised” print is a classic momentum trigger that gets bought in the after-hours session before the segment-level price/volume/FX bridge, the ex-reclassification guide math, and the Q4 implied deceleration are fully digestible from the 10-Q. That mechanism is already partially self-correcting: the stock’s ~9% intraday fade off the July 10 open is consistent with exactly this re-appraisal beginning within the first trading session. With only 3-4 sell-side analysts covering the name and a Street mean target ($260) already below today’s price, there is limited near-term catalyst for the gap to widen further, and it could close within days-to-weeks as models catch up rather than over a multi-quarter horizon. That limited durability — not the direction of the gap — is why conviction is Low-Med and the call is Neutral rather than Short.
Positioning & Catalysts
WDFC is a small-cap ($3.6B), thinly covered (3-4 analysts) name typically held by quality/dividend-compounder investors and momentum buyers who chase big beats; it is not a crowded short (WD-40 has a long dividend-growth history and low typical short interest), so this is not a squeeze setup in either direction — more a “the story needs another print to be re-underwritten” situation. Dated catalysts: the Q4 FY26 print and initial FY27 guide (~October 2026) is the real test of the pull-forward giveback and gross-margin recovery cadence; the still-unnamed permanent CFO appointment (Sara Hyzer is transitioning to President, Americas) is a governance overhang that resolves on its own timeline; oil/specialty-chemical spot pricing over the next two quarters is externally monitorable in real time.
Scenarios & Expected Value
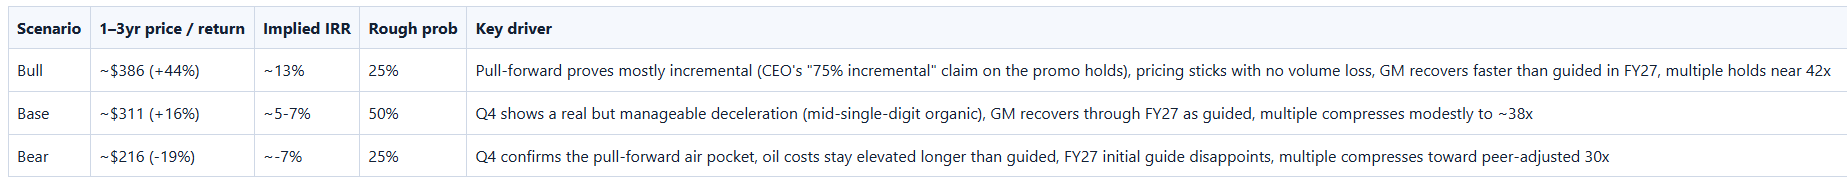
Expected value is roughly flat to modestly negative, skewed by a bear case that is at least as probable as the bull and requires less to happen (the bear needs only Q4 to confirm what management already flagged; the bull needs the market to keep paying a rich multiple and the pull-forward to prove mostly incremental). This skew supports Neutral over Long.
What Breaks the Call / Too-Hard Honesty Check
Bull break: Q4 FY26 organic growth (ex-FX, ex-pull-forward) printing above the guide-implied ~5% midpoint and gross margin printing at/above the 55.5% guide ceiling would show the momentum is structural, not pulled forward — revisit toward Long. Bear break (external): WTI/specialty-chemical spot prices re-normalizing faster than guided (WTI holding below ~$75 through Q4) would support a margin upside surprise that breaks the bear case even if volume decelerates. The swing variable — how much of the 24% quarter unwinds — resolves within one more print (~3 months away) and the valuation math is skewed enough (rich multiple, credible pull-forward evidence, deserved range below spot) to support a real directional lean; this is a Neutral call with a bearish tilt, not a Too-Hard, but Low-Med conviction reflects genuine two-sided near-term uncertainty on magnitude.
WD-40 is a legitimately excellent business whose own Q3 filing shows the growth wasn’t as clean as the 24% headline, and at ~43x forward earnings the stock needs the market to keep believing it was anyway.
What Was New This Quarter
Net pricing was essentially flat; volume and FX did almost all the work. The 10-Q’s segment bridge shows Americas price +$0.4M / volume +$21.1M / FX +$1.6M; EIMEA price -$0.6M / volume +$7.2M / FX +$4.4M; Asia-Pacific price +$0.2M / volume +$3.8M / FX +$1.2M. Total: price ~flat, volume ~$32M (84% of the $38.2M increase), FX ~$7.3M (19%). This is a volume story, and a meaningful chunk of that volume (the Disney/Home Depot promotion in the U.S., ~$3M of explicitly-acknowledged EIMEA/APAC pull-forward) is non-recurring or borrowed from Q4.
Guidance “raise” is mostly a reclassification, not new operating strength. The Americas homecare/cleaning brands (previously excluded as held-for-sale) are back in the guided base (~$12M sales / $2.9M op income / $0.17 EPS). Backing that out, the true FY26 operating raise vs. the April guide was: net sales CC floor +$10M (ceiling unchanged), operating income floor +$1.1M (ceiling essentially unchanged), EPS floor +$0.13 (ceiling +$0.03) — management confirmed this framing explicitly on the call.
Gross-margin guide was cut, not raised, at the midpoint. New range 54.5-55.5% vs. 55.5-56.5% three months ago — a 100bps cut, split 40bps reclassification / 60bps “higher-than-expected cost increases” (oil/specialty chemicals).
CFO transition mid-cycle. Sara Hyzer moves to President, Americas, with no permanent successor named; the controller was elevated to Chief Accounting Officer as a continuity bridge (effective June 29, 2026).
KPI framework retirement. The 55/30/25 business model — WD-40’s investor-facing scorecard for over a decade — sunsets after FY26 and is replaced by the “Enduring Business Model” (sales growth, gross margin, Adjusted EBITDA growth vs. sales growth) starting FY27, reducing easy YoY comparability into next year.
Homecare/cleaning divestiture abandoned. After “extensive engagement with potential buyers,” management could not complete the Americas HCCP sale and reclassified the assets as held-for-use, recording a $1.3M one-time amortization catch-up (properly excluded from non-GAAP results).
New $100M buyback authorized June 15, 2026 — but doesn’t start until September 1, 2026, providing no technical support ahead of the Q4 print.
2nd-Order Implications
Fact: ~$3M of EIMEA/APAC volume was explicitly pulled forward from Q4 into Q3 ahead of price increases and Middle East supply concerns → implication: Q4 organic growth is mechanically lower than it otherwise would have been → 2nd-order: the market, having just rewarded the Q3 beat, is likely to punish a Q4 print that reads as a deceleration even if it is in line with management’s own guidance → thesis relevance: sets up a binary near-term catalyst where “in-line with guidance” could still read as disappointing given Q3’s pace.
Fact: gross-margin guide cut 100bps at the midpoint on lagged oil/specialty-chemical costs, explicitly flagged to hit hardest in Q4 → implication: Q4 EPS growth decelerates on both the revenue and margin lines simultaneously → 2nd-order: consensus EPS estimates for Q4 (currently $1.65, barely moved from pre-print levels) likely need to come down, not just revenue → thesis relevance: we expect Q4 EPS estimates to drift down 3-8% over the next several weeks as the margin-guide cut is modeled in.
Fact: operating cash flow underperformed net income by a widening margin this quarter on AR growth tied to the promotional sell-in → 2nd-order: if Q4/Q1 FY27 collections lag (a normal risk after a large channel-loading quarter), free cash flow conversion — historically a core part of the bull case (>25% ROIC, asset-light) — could look weaker for a quarter or two, even as reported EPS looks fine → thesis relevance: watch DSO and AR growth vs. sales growth in the Q4 print as a quality-of-earnings check.
Fact: CFO transition with no permanent successor named, occurring in the same window as a complex accounting reclassification (held-for-sale → held-for-use) and a KPI-framework change (55/30/25 → Enduring Business Model) → implication: heightened key-person and reporting-continuity risk during a period when investors most need clean, comparable disclosure → 2nd-order: any FY27 guide given without a permanent CFO in place would carry above-average execution/credibility risk → thesis relevance: a factor supporting Low-Med rather than High conviction on either side.
Estimate revisions: we expect FY26 consensus EPS to move up 3-5% over the next 1-2 weeks (simple catch-up to the new $6.05-6.35 guide) but FY27 consensus (currently $6.48, +7.8% YoY) to face 2-4% downward pressure over the next two prints as the market re-underwrites the true (ex-reclassification) growth algorithm and margin-recovery pace.
Valuation framework: the quarter does not change the appropriate multiple framework (P/E remains the primary lens for this business), but it does raise the bar for what “premium” means — the stock re-rated from ~40x TTM in February to ~43x on the new guide, moving further from, not closer to, a defensible peer-adjusted premium.
Valuation
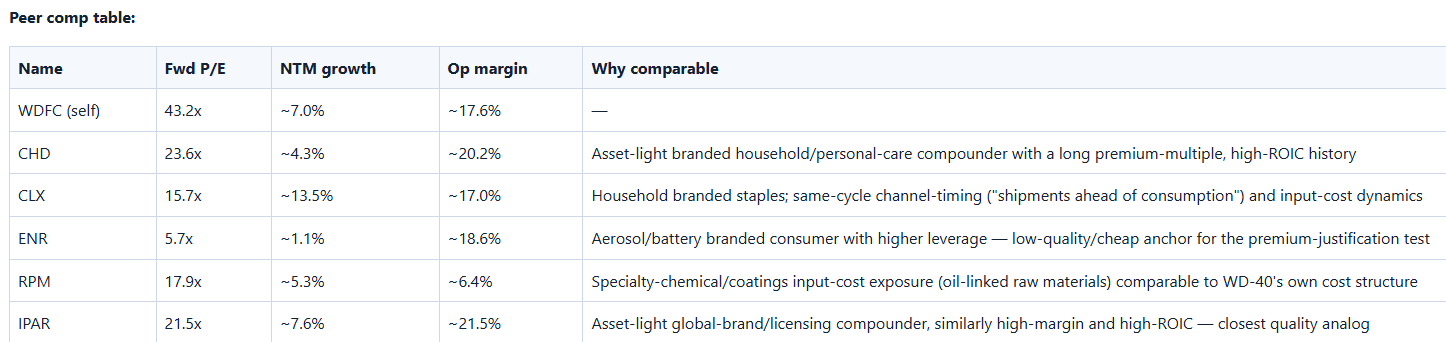
Peer median forward P/E is ~17.9x (RPM); WD-40’s superior ROIC target (>25%) and near-zero capex asset-light model justify a real premium, but WD-40’s NTM growth (~7.0%) and operating margin (~17.6%) are in line with — not dramatically better than — several of these peers, including IPAR, the closest quality analog, which trades at half WDFC’s multiple with comparable margins and growth. A defensible premium here is roughly 30-60% above the peer median (~23-29x), not the ~140% premium the stock currently commands.
Multiple vs. own history: at 43.2x forward, the stock sits above the top of its own 1yr trailing-P/E range (29.5x-40.3x) but still just below its 3yr ceiling (49.9x, set in August 2024) — though that 3yr high is not a clean comp for today’s setup, since it predates this cycle’s oil shock and reclassification noise and reflected a different regime; the more relevant, recent-regime anchor is the 1yr band, and today’s multiple is already above it. Multiple vs. peers: as above, the stock trades at more than double the peer median (~141% above) despite a growth/margin profile that is comparable, not exceptional, versus the set — “in line with peers” would be the wrong read; the gap is real and not explained by fundamentals alone. Consensus drift: FY26 (0y) consensus EPS is essentially flat over 90 days (6.0125 current vs. 5.99 90 days ago, 1 up/1 down revision in the last 30 days) because the feed had not caught up to the new guide at capture time; FY27 (+1y) consensus EPS has drifted up modestly (6.48 current vs. 6.37 ninety days ago, but 2 down-revisions in the last 7 and 30 days each) — mixed, slightly stale signal that neither strongly supports nor contradicts our view, disclosed as such.
What the price is paying for: holding our base-case operating path (FY29E EPS $8.18) and solving for the exit multiple, the market needs ~42x for a 10% return and ~48x for 15% — both above our 33-38x deserved range and above the stock’s own normal-year historical ceiling. Flipping the solve: holding a normalized 35x exit multiple (mid of our deserved range) and solving for the required FY29E EPS to clear a 10% return gives ~$9.76 — above even our bull-case FY29E EPS of $9.20. In other words, even the bull-case earnings path does not clear a 10% hurdle at a normal-premium multiple. The price is dominantly paying for duration of an elevated multiple, not operating delivery — the opposite of what a fresh long needs.
Sensitivity read: across a grid of Year-3 (FY29E) EPS $7.20-$9.20 and exit multiples 30x-42x, the 3yr IRR spans roughly -9% to +16%; the multiple axis dominates the spread more than the EPS axis — a 12-point multiple swing moves the outcome about as much as a full $2/share EPS swing, and multiple compression is the higher-probability risk given today’s extension versus both history and peers.
Deserved forward multiple: 33-38x (applied to FY27E EPS of $6.76) — because (1) durable but ordinary mid-to-high-single-digit organic growth once the Q3 pull-forward normalizes, not the 20%+ pace just posted; (2) genuinely superior but not unique capital efficiency (>25% ROIC target, asset-light) that a direct quality analog (IPAR) offers at roughly half today’s multiple; (3) a real, guided near-term margin air pocket (100bps guide cut, oil-cost lag into Q4/FY27) that caps near-term multiple expansion until margin recovery is proven → implied price $223-$257 vs. $267.63 today (4-17% below current levels). The peer anchor and the required-return math both pull toward the low-to-mid 30s; own-history pulls toward the high 30s/low 40s in strong years — we weight the peer and required-return anchors most heavily because the historical ceiling (49.9x, August 2024) reflects a different cost/regime environment than today’s.
Bull/Bear — Key Variable
Single most important variable: Q4 FY26 organic (ex-FX, ex-pull-forward) net sales growth, which resolves at the October 2026 print. It controls both the estimate-revision trajectory (whether FY27 numbers get cut or held) and the sentiment regime (whether Q3 is read as a new growth level or a one-quarter spike) — and it is genuinely underappreciated because the market’s after-hours reaction traded the 24% headline, not the guide-implied ~5% Q4 midpoint.
Bull path: Q4 organic growth prints mid-to-high single digits or better (the promotional “75% incremental” claim holds, new distribution ramps as planned, pricing sticks with limited volume loss) and gross margin comes in at or above the 55.5% guide ceiling. Chain: confirms the quarter’s strength was mostly structural → FY27 consensus holds or rises → multiple holds near 40x+ → implied price ~$380-390, IRR ~13%.
Bear path: Q4 organic growth prints flat-to-low-single-digit (the pull-forward and promo prove mostly borrowed demand) and/or gross margin misses the 54.5% guide floor as oil costs stay elevated longer than modeled. Chain: confirms Q3 was inflated → FY27 consensus cut 3-8% → multiple compresses toward peer-adjusted levels (~30x) → implied price ~$216, IRR ~-7% (matching the §1E Bear row). This is how an investor loses money even though the underlying brand and category positioning remain fine — a growth-rate reset plus a multiple reset compounding in the same direction.
Why it’s hard to call: the CEO’s own “75% incremental” claim on the Home Depot/Disney promotion is unverifiable from outside the company and is exactly the kind of number management has an incentive to frame favorably; the true organic run-rate is genuinely unknown until Q4 actuals are in hand, and oil/specialty-chemical spot pricing (an external, largely unforecastable geopolitical variable) determines the margin side independently. Leading indicators: WTI and Brent spot prices (weekly), any interim retail-sell-through commentary from Home Depot-exposed peers, and DSO/AR trends that would show up before the Q4 print in any interim disclosure.
Second variable (close behind): the pace of FY27 gross-margin recovery once oil-cost relief flows through — management would not commit to a cadence on the call, and this determines how much of any Q4 growth disappointment gets offset by margin upside.
Call / Filing Nuggets That Matter
Segment price/volume/FX bridge is the single most decision-useful table in the 10-Q — it is the only place the “flat net pricing, FX-heavy, volume/promo-driven” read is directly verifiable rather than inferred from the press release narrative.
EIMEA operating margin only ticked up 20bps (57.9%→58.1% nine-month) despite 9% segment sales growth and heavy FX tailwind — operating leverage there was thinner than the consolidated 47% operating-income growth headline suggests; most of the leverage this quarter came from the Americas segment (26.2%→27.2% quarterly operating margin) tied directly to the promotional program.
*Asia-Pacific gross margin declined from 59.0% to 56.5% YoY* on petroleum-based input costs concentrated in the Asia distributor markets affected by the Iran conflict — a segment-level data point the consolidated 56.6% gross margin headline masks.
$7.0M of the 2023 Repurchase Plan’s $50M authorization remains unused heading into the new $100M authorization that only becomes effective September 1, 2026 — no near-term buyback support into the Q4 print.
Research and development spend was flat-to-down YoY ($1.9M vs. $2.5M in Q3; $6.0M vs. $6.3M nine-month) even as A&P spend rose — consistent with a marketing/promotion-led rather than innovation-led growth quarter.
Q&A Tension: The two most probing questions came from Michael Baker (D.A. Davidson), who pressed management line-by-line on whether the FY26 guidance “raise” was real math or just the accounting reclassification plus discretionary cost cuts — management answered directly and quantified the ~$1.1M true operating-income raise, which is the basis for our Section 2/3 analysis. Linda Bolton-Weiser (Water Tower) pushed on the pace of FY27 gross-margin recovery and pricing-elasticity risk (given customer pushback in the prior cycle’s larger price increases); the CFO’s answer was notably hedged — “it is hard... to comment on that at this point in time” — an unresolved question the Street should not treat as settled.