

The headline read on NKE’s Q4 FY2026 is an illusion. An unplanned $986 million IEEPA tariff refund inflated reported EPS to $0.72 and gross margin to 49.2%, obscuring an underlying print that delivered $0.20 per share on a 40.2% gross margin -- essentially flat with the prior year on both metrics. Strip the one-time item and this was an in-line quarter against depressed expectations, not a beat.
The quarter that matters is what management said about the path forward. Revenue guidance for the three-quarter period through Q2 FY2027 was quietly worsened -- now “down low to mid single digits” versus the prior “down low single digits” -- reflecting a mid-April deceleration in sell-through that management attributed to consumer pressure on discretionary spending. Simultaneously, gross margin expansion was pulled forward to Q1 (from Q2), creating a composition shift: less revenue, but tighter cost management. The CFO departure after 17 years, announced during the call, adds execution risk to an already-fragile turnaround.
The stock is near a four-year low and the forward P/E of 17-18x looks compressed. But cheap relative to history is not cheap in absolute terms when underlying EPS sits at $1.58 and the recovery catalyst -- Nike Sportswear and Jordan Streetwear returning to growth -- remains unquantified and contingent on product launches that do not arrive until H2 FY2027. The street is being asked to value a $42 stock on what Nike could earn in FY2028, not what it will earn in FY2027.
What Was New This Quarter
1. The tariff refund is the entire P&L story -- and it was not in guidance. The $986 million IEEPA recovery was disclosed for the first time on this call. Management explicitly stated it was “not included in our previous financial guidance.” The recovery boosts Q4 gross margin by ~900 basis points and EPS by $0.52. Without it, Q4 EPS was $0.20 on 40.2% gross margin -- in-line versus the prior year Q4.
2. Revenue guidance worsened. When NKE guided the cumulative Q4 FY2026 through Q2 FY2027 period last quarter, the language was “revenues down low single digits.” On this call it became “down low to mid single digits.” That is not a reaffirmation. It is a downgrade, driven by a mid-April deceleration in retail sales across geographies.
3. Gross margin inflection pulled forward to Q1 FY2027. The prior guide had gross margin turning positive in Q2. Now expected positive from Q1. This is a legitimate improvement -- driven by less discounting in North America and supply chain restructuring actions taken in Q3/Q4. But the mechanism is lower revenue (tighter buys, moderated sell-in), not volume recovery.
4. CFO Matthew Friend departure. After 17-plus years, Friend announced his departure during prepared remarks with no successor named. Hill offered an effusive send-off and pledged a “seamless transition.” The timing -- mid-turnaround, with an Investor Day scheduled for November 16-17 -- adds uncertainty to the most operationally complex moment in Nike’s recent history.
5. Mid-April demand deceleration confirmed across geographies. Management confirmed a “strong start in March” followed by a “deceleration in retail sales trends” from mid-April onward. They explicitly linked it to consumer pressure on traffic and discretionary spending. This is new -- prior quarters had not identified a within-quarter inflection with this specificity.
6. NA wholesale growth of 10% was not real sell-in growth. The CFO explicitly stated: “We didn’t sell in up 10%. There was a meaningful amount of that revenue growth that was associated with lower returns or sales-related reserves and returns, lower discounts and lower cancellations.” This accounting improvement makes the NA wholesale headline look far better than the underlying demand reality.
7. Converse collapse is accelerating. Revenue declined 32% reported and 34% currency-neutral in Q4. Full year was down 31%. This is a brand in freefall, not a managed wind-down. EBIT was $18 million for the full year (down from $240M in FY2025 = -93%). Converse is becoming an immaterial contributor while consuming real management bandwidth.
8. EMEA inventory still elevated; EMEA Digital down 24%. Off-price was cut 50%+ in EMEA, which drove full-price realization improvements but created a structural Q2 FY2027 headwind (Friend called out the tough compare explicitly). Inventory is up low double digits in EMEA with “actions in place to reduce supply.”
9. China profitability expected to bottom before sales. The CFO said: “We continue to believe that profitability will bottom before sales in this market.” This is an explicit warning that China EBIT erosion has further to run even as sell-through stabilizes. China EBIT was $1.278B in FY2026 vs $1.602B in FY2025 = -20% -- one of the most significant drags in the business.
10. World Cup creating real June momentum, but it is event-driven. Hill described “1.5 billion views” of Nike football content and a Mercurial shoe launch that was “the fastest-selling 24-hour launch for cleated footwear in the history of Nike Direct.” Management noted a demand bounce in June. This is legitimate signal -- but it is tournament timing, not a sustainable category inflection.
Call / Filing Nuggets That Matter
The tariff recovery was recorded to accounts receivable, not all cash. Of the $986 million benefit, Nike had collected only ~$300 million in cash by May 31. The remaining ~$686 million sits in accounts receivable. This explains why AR jumped 26% year-over-year ($5,931M vs $4,717M) and it means the “cash from operations” in FY2026 was partially inflated by $300M of government refund receivables converted to cash. The AR balance normalization will be a FY2027 tailwind or drag depending on collection timing.
North America EBIT ex-tariff was down 1%, not up 91%. The reported North America EBIT of $2,000M (up 91%) includes $965M of the tariff refund. Ex-tariff, North America EBIT was approximately $1,035M vs $1,045M prior year = -1%. All the apparent North America profit improvement was the tariff refund. The underlying segment is barely treading water.
Nike Sportswear + Jordan Streetwear represent approximately half of total revenue and are declining double digits. Hill stated this explicitly: “together they represent approximately half of our revenue.” Double-digit decline on ~$23B of revenue is approximately a $2-3B annual revenue headwind from these two categories alone.
The “12 new footwear styles” for Sportswear in H2 FY2027 are the recovery catalyst -- and they have never been consumer-tested at this stage. The brief-to-market cycle started when Hill arrived. Spring 27 will be “the first time you’re going to see the fruits of those teams’ efforts.” Management is effectively asking investors to wait until mid-FY2027 to find out whether the new Sportswear product cadence works.
Greater China inventory is improving but revenue declines are deepening. China inventory was down double digits in Q4 -- positive. But China revenue was -17% CN and wholesale was -19% in Q4. The inventory clean-up is going well but the business is shrinking faster than inventory is being cleared. EBIT of $243M in Q4 vs $304M prior year (-20%) -- and Friend said “profitability will bottom before sales.”
FX was a tailwind in Q4 but management explicitly said FX will not help in Q1 FY2027. The prior period revenue declines look worse in CN than reported terms; the reverse will apply in Q1. Friend: “Q1... no expected benefit from foreign exchange and currency-neutral revenue growth” -- meaning reported and CN growth rates converge lower.
Capex has been cut sharply. FY2025 capex was $430M vs $812M in FY2024 = -47%. Management is operating in capital conservation mode. This could limit the pace of store elevation and supply chain upgrades that are central to the recovery thesis.
The $18B share buyback program remains authorized but spending has nearly stopped. FY2026 share repurchases were only $123M (1.8M shares) vs $2,985M in FY2025. Cash is being conserved. With a $2B debt maturity in FY2027 (current portion of LT debt on the May 31 balance sheet), the company is managing liquidity carefully.
Q&A Tension: The two most direct challenges on the call were: (1) Anisha Sherman (Bernstein) asked whether FY28 would be the first “normal” year and pushed on margin recovery drivers “excluding operating leverage.” Hill deflected with the Knicks analogy; Friend said to wait for the Investor Day in November -- i.e., no quantified path to double-digit margins was provided on this call. (2) Matthew Boss (JP Morgan) asked about North America wholesale cadence in FY27, specifically whether any quarters would show declines. Friend acknowledged Q2 has a “tough compare” but declined to give quarter-level guidance. The unwillingness to commit to any forward-year quarterly outlook, despite guiding for the 3-quarter EPS cumulative, is notable and likely reflects the team’s own uncertainty about sell-through stabilization.
What the Market May Be Missing
1. The NA wholesale number is a channel quality improvement, not demand.
Friend’s admission that North America wholesale growth was “not sell-in up 10%” is buried in the Q&A and will not make the headline summaries. What happened: Nike reduced sales-related reserves, cancellations, and discounts -- which flows through as higher recognized revenue. This is a good thing for channel health but it is not evidence of demand acceleration. The sell-in to Footlocker and other wholesale partners did not grow 10%. Investors anchoring on “+10% NA wholesale” as a green shoot are measuring the wrong thing.
2. The FY2027 earnings picture is worse than guidance implies.
The three-quarter “flattish earnings” guidance implies EPS of roughly $1.50-1.70 over Q4 FY2026 + Q1/Q2 FY2027. But Q4 FY2026 included $0.52 of tariff benefit. So Q1 + Q2 FY2027 combined earnings must be flat with Q3 + Q4 FY2025 (the prior-year comp period) on an underlying basis. The tariff refund elevated the Q4 base; the underlying trajectory of the business is that FY2027 H1 earnings could be down meaningfully year-over-year in GAAP terms even if they are “flattish” on the management-defined cumulative basis. The consensus EPS of $2.40 for FY2027 looks optimistic given this composition.
3. Converse is becoming a liability, not just an underperformer.
Full-year FY2026 Converse EBIT was $18M on $1.174B of revenue -- essentially break-even. That is down from $240M on $1.692B in FY2025. This is not a business that is being repositioned slowly; it is collapsing. Converse accounted for roughly 2.5% of NKE revenue in FY2026 and will be under 2% in FY2027. The brand requires its own management team, marketing resources, and retail relationships. The question of whether NKE should retain Converse is not being asked on this call, but it should be.
4. The recovery requires every element to work simultaneously.
The NKE bull case requires: (a) Sportswear/Jordan to inflect positive in H2 FY2027, (b) China to stabilize and stop declining, (c) EMEA to clear inventory without further margin damage, (d) supply chain cost savings to offset macro/tariff headwinds, and (e) a new CFO to be hired and integrated without disrupting execution. None of these are improbable individually, but the conjunction problem is real. If any one element delays by one fiscal year, the NTM earnings continue to disappoint.
2nd-Order Implications
Chain 1 -- Revenue trajectory:
Nike Sportswear + Jordan Streetwear declined double digits in Q4 and sell-through “remains challenged” per Hill. These categories represent ~50% of revenue, or roughly $23B. A sustained double-digit decline implies a $2.5-3B annual revenue headwind from these categories alone -- roughly 5-7% of group revenue. Even if performance sports (running +$1B over 5 quarters, football/basketball/training all growing mid-to-high single digits) continue their trajectory, performance is only ~$15B and growing mid-single digits (+$750M annually). Net of these offsets, NKE revenue continues declining until Sportswear inflects. The management guidance of “down L-MSD” for Q1/Q2 FY2027 is consistent with this math. Estimate revision direction: revenue estimates for FY2027 and FY2028 should come down following this call -- the widened guidance range and softer Q2 framing (multi-point headwinds) imply the full-year consensus of ~$48.5B for FY2027 is at risk. A realistic FY2027 estimate may be $44-46B.
Chain 2 -- Margin structure:
Gross margin improvement is being driven by less discounting (full-price realization improving in NA, EMEA Digital off-price down 50%+) rather than volume leverage. This is structurally better than cost-cutting, but it creates a ceiling: you can only improve full-price realization so much before product scarcity and shelf presence become problems. Meanwhile, demand creation (marketing) is growing in FY2027 due to World Cup investment. The supply chain restructuring -- smaller distribution network, changed factory mix, reduced workforce -- should deliver gross margin benefits starting FY2027 per management. But if revenue comes in at the low end of guidance, operating leverage on S&A will be negative despite cost discipline. Net: gross margin should modestly improve in H1 FY2027 as guided, but operating margin improvement may be limited if revenue lands at -5%.
Chain 3 -- Cash conversion and balance sheet:
FY2025 operating cash flow was $3.7B on $3.2B net income -- good conversion. But FY2026 contained the $986M tariff refund flowing through OCF (partially as cash received: $300M, remainder in AR). The underlying OCF picture is weaker. Capex has been cut to $430M (from $812M in FY2024), which means store elevation and supply chain investment is being rationed. With $2.0B in LT debt maturing in FY2027 (appearing in current liabilities on the May 31, 2026 balance sheet), and share buybacks essentially halted at $123M for the full year, the balance sheet flexibility that Nike historically enjoyed is being managed more defensively. This is not a distress signal but it is a constraint: any acceleration in capex or marketing investment requires either earnings recovery or debt refinancing. Second-order: the cost-reduction actions in FY2026 generate margin benefit in FY2027, but the capex cut-back may slow the physical retail elevation that is central to the premium channel strategy in China and EMEA.
Chain 4 -- Competitive dynamics:
Nike Running gained 5 points of running market share in statement footwear in North America and Western Europe per Hill. This is meaningful -- it implies On Running, Hoka (owned by Deckers), and New Balance are not accelerating their share gains at Nike’s expense in performance running. However, Sportswear and lifestyle, where Nike’s share has declined, are exactly where Adidas, New Balance, and On compete. Nike’s brand equity in sport is holding; its brand equity in street-style is the contested zone. The World Cup is a genuine competitive moment: Nike controls 9 of 32 national team kits at the 2026 World Cup (as market leader) and is using it aggressively. But Adidas also holds major kit sponsorships and has a strong lifestyle position. Second-order: if the World Cup succeeds in driving halo demand for NikeSportswear (as management hopes), it could pull the inflection forward; if not, the Sportswear reset is pushed to FY2028.
Chain 5 -- Estimate revision direction and magnitude:
Post-print, sell-side will likely: (a) reduce FY2027 revenue estimates by 1-3% given the widened guidance range and Q2-specific headwinds; (b) modestly raise FY2027 gross margin estimates given the earlier-than-guided inflection; (c) be forced to address the underlying EPS picture stripped of the tariff refund benefit. The yfinance FY2027 consensus EPS of $2.40 vs the $1.58 underlying FY2026 base implies 52% EPS growth -- achievable only if revenue recovers and margins expand simultaneously. More realistic FY2027 underlying EPS may be $1.80-2.10. The consensus likely needs to come down ~10-15% for FY2027, which creates estimate risk for the next 1-2 quarters if sell-through does not improve.
Chain 6 -- Sentiment and positioning:
The stock has de-rated from $80 in February 2026 to $41-42 in late June -- a 48% decline in four months. The April 2 tariff shock drove a single-day 16% decline on 114M shares (3-4x average daily volume). The stock is near its 52-week low ($40.00). At these levels, forced selling and momentum selling has likely occurred -- the shareholder base is probably more concentrated in long-term holders and value-oriented funds at this point. A positive development (Sportswear volume acceleration, China stabilization, or a new CFO hire) could re-rate the stock quickly given depressed positioning. But the path of least resistance is continued earnings pressure and muted stock performance until H2 FY2027 results prove the recovery.
Net thesis effect: Thesis weakens modestly. The revenue guidance downgrade and the CFO departure are negative deltas. The tariff refund is a one-time item that does not change the underlying trajectory. The gross margin pull-forward is a genuine positive but is being achieved through lower volumes, not recovery. The World Cup momentum is real but temporary. On balance, FY2027 shaping up worse than the prior guide implied. Estimates likely need to be reduced. The stock may find a floor around $40-42 given the net cash balance sheet and long-term brand equity, but a re-rating above $50 requires evidence of Sportswear/Jordan inflection that is not yet available.
Valuation
Where the multiple sits vs history. At 17.7x forward P/E, NKE is at the low end of its 5-year historical range. But the denominator is a consensus EPS ($2.40) that requires ~52% EPS recovery from the FY2026 underlying base ($1.58) -- a very large lift within 12 months. On FY2026 underlying EPS, NKE trades at 26.9x -- not cheap. The stock’s 3-year P/E range (trailing) has been 14x-50x; the current forward multiple of 17.7x looks reasonable if you believe the EPS recovery materializes, but demanding if it does not.
Business trajectory and exit multiple rationale. In a base case, Nike’s 2-3 year trajectory involves: Sportswear/Jordan stabilizing and returning to low single-digit growth by FY2028, running and performance continuing mid-single-digit growth, China bouncing off a trough, and supply chain restructuring delivering 100-150 bps of gross margin expansion. This gets you to FY2028 revenue of $49-51B and EPS of $2.50-2.80. An exit P/E of 18-20x is appropriate for a global consumer brand with durable brand equity, net cash balance sheet, and moderate growth. At those parameters, fair value in the base case is approximately $45-56, implying a ~6% annualized return from today’s price (including the $1.64 dividend yield). This does not clear a 10% hurdle.
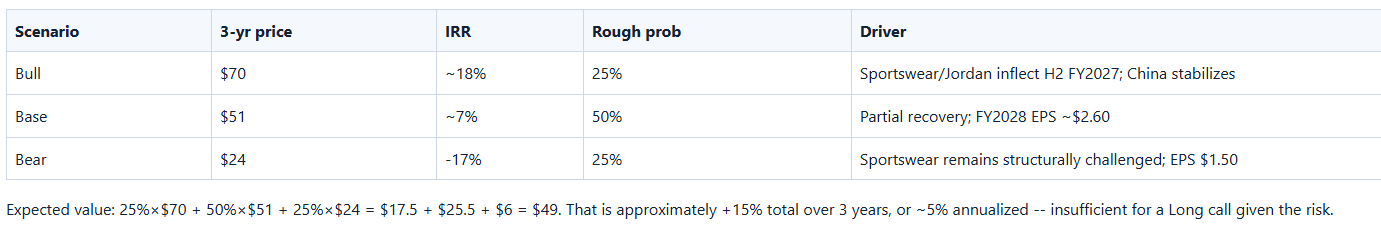
The 10% return hurdle requires EPS of $2.85-3.14 in FY2028, implying 80-100% recovery from the FY2026 underlying base of $1.58. That requires Sportswear and Jordan to genuinely recover, China to stabilize, and supply chain savings to materialize on schedule -- simultaneously. It is achievable but it is not the most likely single path. The IRR math for the 3-year return is not compelling in the base case. The bull case (EPS $3.20+, P/E 22x) produces a $70+ price target and ~18% annualized IRR. The return is asymmetric only if you place a meaningful probability on the bull scenario.
What durability is priced in today. At $42.49, the market is pricing approximately $2.20-2.40 of earnings power on a ~18x multiple. That is a 35-52% recovery from the FY2026 underlying ($1.58). The market is not pricing in “peak Nike” earnings but is paying for a material recovery that the next 2 quarters of guidance will not deliver. The single variable the return is most sensitive to is not margin (which management is improving) but revenue growth -- specifically Sportswear and Jordan returning to growth, which drives both the top line and the earnings level. If Sportswear/Jordan inflect in H2 FY2027, the bull case opens. If they do not, the base case IRR is unattractive.
Bull/Bear -- Key Variable
Single most important variable: Nike Sportswear and Jordan Streetwear sell-through velocity in H2 FY2027 (Q3-Q4 fiscal calendar, calendar H1 2027).
This one variable determines everything: direction of revenue, whether the GM improvement is real (full-price selling) or defensive (volume suppression), whether China and EMEA can clear inventory without perpetual discounting, and what NTM earnings look like going into FY2028. The market currently has no ability to forecast this variable -- NKE has not disclosed order book data for the new Sportswear line, and the product arrives at retail in spring 2027 before which consumer response is unknowable. This is not a case of difficult forecasting; it is structural uncertainty about whether the reorganized product teams’ first meaningful output will resonate. That is why the question matters: it controls the multiple expansion/compression pivot, estimate trajectory, and narrative regime shift.
Bull path -- Sportswear/Jordan inflects in H2 FY2027. Management launches 12+ new Sportswear silhouettes in H2 FY2027. Consumer response is positive -- running’s “flywheel” (community events, athlete storytelling, dedicated sales reps in stores) serves as the template and it replicates in Sportswear. Jordan Streetwear finds new silhouettes that are genuinely coveted outside the collector community. Sell-through improves from negative double digits to flat or positive by Q4 FY2027. This causes: (a) NKE’s order books for FY2028 to recover materially, (b) full-price realization to improve further, (c) gross margin to reach 43-44% on higher volumes (vs 42.9% today at lower), and (d) management to provide confident FY2028 growth guidance at the November Investor Day. EPS converges to $3.00-3.50 by FY2028. At 22x P/E: implied price $66-77. Annualized IRR from $42.49 over 3 years: ~16-22%.
Bear path -- Sportswear/Jordan remains under pressure through FY2028. The new silhouettes do not gain traction -- either consumer taste has evolved away from Nike Sportswear toward New Balance and Adidas, or the product execution misses on design. Jordan Streetwear remains promotional and saturated. This means the 50% of revenue continues to contract at mid-to-high single digits even as performance sports grow. Revenue declines accelerate to -6 to -8% in FY2027 and are -3 to -5% in FY2028 as the base is established lower. Simultaneously: China EBIT bottoms at sub-$1B (from $1.28B in FY2026), EMEA remains promotional, and the NA margin improvement is insufficient to offset volume loss. EPS is $1.40-1.70 in FY2028. The narrative shifts from “turnaround is working” to “structural brand erosion” -- P/E compresses to 13-15x. Implied price: $20-26. Annualized IRR from $42.49 over 3 years: approximately -15 to -17%. This is how an investor loses money even if Nike remains a fundamentally good business -- the stock re-rates on a lower EPS base at a lower multiple, driven by a sentiment regime change from “premium brand in a rough patch” to “brand losing relevance in its core category.”
Why it is hard to call. The Sportswear inflection is structurally difficult to forecast because: (a) consumer taste in lifestyle footwear is trend-sensitive and non-linear; (b) the new products have never been consumer-tested at retail scale; (c) Nike has not disclosed any leading indicators (early reads from key retail partners, pre-orders, digital engagement for new silhouettes) that would allow external monitoring; and (d) the competitive dynamics in lifestyle footwear (Adidas Samba cycle, New Balance 1906R, On Cloud) are themselves trend-driven and may or may not be in digest phase by H2 FY2027. Leading indicators to watch: weekly NBA merchandise and running shoe sell-through data from NPD/Circana, Nike’s own full-price digital sell-through rate (not disclosed on calls but referenced directionally), and the Q1/Q2 FY2027 earnings calls for any inflection in Jordan Streetwear commentary from “declining double digits” toward “declining single digits.”
A second variable worth flagging: the new CFO hire. If Nike appoints an external CFO with a background in supply chain transformation (vs internal promotion), it signals a more aggressive restructuring posture -- potentially accelerating the margin recovery path. If the appointment is delayed past the November Investor Day, execution uncertainty around guidance and modeling will increase.
Position Verdict (1-3 Year View)
Call: NEUTRAL | Conviction: Low | Horizon: 1-3yr | One-line thesis: The risk/reward is balanced -- the bull case (brand recovery + EPS normalization) and bear case (Sportswear structural erosion) are roughly symmetric around current price, and the swing variable is genuinely unforecastable before H2 FY2027 product results.
A. Business and Industry Trajectory (1-3yr)
Nike is the dominant global performance sports brand with no credible challenger to its position in running, basketball, and global football. The institutional assets -- athlete relationships, innovation capability (Air, ZoomX, Aerofit), and global distribution -- are intact. The consumer is not abandoning Nike in performance sports: running grew $1B+ over 5 quarters, gained 5 points of market share in statement footwear. The industry trajectory in performance sports is positive (participation trends, premiumization, wearable/tech integration).
The problem is that ~50% of Nike’s revenue is Sportswear and Jordan Streetwear -- categories where brand relevance in lifestyle/fashion is contested and where Nike has lost share to Adidas, New Balance, and smaller challengers over the past 2-3 years. These are not performance sports; they are fashion. Fashion is trend-dependent and non-linear. The 12 new Sportswear silhouettes scheduled for H2 FY2027 represent the first genuine product renewal attempt in these categories under the reorganized structure.
Earnings power in ~3 years: If Nike executes the recovery as management describes -- Sportswear returning to growth, supply chain savings delivering 150-200bps of GM improvement, China stabilizing at a lower base -- FY2028 earnings power is in the range of $2.80-3.50, depending on Sportswear timing. This represents a 75-120% recovery from the FY2026 underlying base. It is achievable but requires sustained, correct execution over multiple seasons.
B. What’s Priced In vs Our View (Variant Perception)
The current price of $42.49 with forward P/E of 17.7x on consensus EPS of $2.40 implies the market is pricing approximately a 50% EPS recovery within 12 months and then moderate growth thereafter. Given the guidance calling for continued revenue declines in Q1 and sequential deterioration in Q2, FY2027 consensus EPS of $2.40 is almost certainly too high. Our view is that FY2027 underlying EPS will come in at $1.80-2.10 -- 12-25% below current consensus.
The gap: Our trajectory view is neutral/negative for 12 months and open-ended for 24-36 months, while the market appears to be pricing a smoother recovery. The mispricing -- if there is one -- is that the market is discounting the 2-quarter guidance downgrade and the CFO departure too lightly, while still using consensus EPS that has not been adjusted downward. However, this is not a clear variant perception opportunity: the counterargument is that the market is already pricing a turnaround over 18-24 months, and at 52-week lows the downside may be limited by the net cash balance sheet and floor valuation of Nike’s brand.
The mispricing persistence mechanism is weak. There is no structural reason why the market would systematically underestimate how bad FY2027 will be -- this is a widely-covered mega-cap. Forced sellers (momentum funds, growth funds) have already largely exited based on the 48% selloff. The remaining holders are likely already patient value investors who understand the turnaround thesis. This limits the expected value skew that would justify a strong directional view.
C. Valuation Cross-Check (not the driver)
At the base case EPS of $2.50-2.80 in FY2028 and an 18-20x exit P/E, implied price is $45-56 in 3 years. Including the $1.64/year dividend, total return is approximately $49-62 vs current $42.49 = roughly +15% to +46% total return, or 5-14% annualized. The base case does not clear a 10% annual hurdle. The bull case (EPS $3.20, 22x P/E = $70 price) produces 18%+ annualized IRR and would be a strong long. The bear case ($25 price) produces -15% annualized return. The expected value calculation with rough probabilities:
D. Positioning and Catalysts
Sentiment is depressed. The 48% selloff, 52-week low proximity, and heavy sell-side downgrade cycle suggest the shareholder base has been largely cleansed of growth/momentum holders. Short interest has likely increased. The stock is not a consensus short either -- the Street mean PT is $55 (33 analysts), implying 30% upside from current levels. There is a valuation floor argument.
The dated catalysts over the holding period: (1) New CFO announcement (near-term; can be positive or negative); (2) Q1 FY2027 results (September/October 2026) -- the first test of whether the GM inflection is real and whether sell-through stabilizes; (3) November Investor Day (November 16-17, 2026) -- the first comprehensive strategic and financial framework since Hill’s arrival; (4) H2 FY2027 Sportswear product reads (spring/summer 2027 retail season); (5) FY2027 Q3/Q4 results (January-April 2027) which will confirm or deny the Sportswear thesis.
The catalyst path exists. But it is 12-18 months away in its most important form (Sportswear sell-through data). Without a clear catalyst forcing the gap to close, a LONG position requires significant patience through continued earnings pressure.
F. What Breaks the Call / Too-Hard Honesty Check
What breaks a Long call: (1) Sportswear product launches in H2 FY2027 gain no traction at retail -- sell-through remains negative in this category through FY2028; (2) China revenue declines accelerate to -20%+ CN on a sustained basis rather than stabilizing; (3) New CFO disrupts the turnaround path through strategy changes or execution gaps; (4) Macro recession that hits the aspirational consumer spend hard. Any of these individually pushes the stock toward the bear case.
What breaks a Short call: (1) The November Investor Day is received as credible and forward-looking -- management frames a path to $4+ EPS in FY2029, the stock re-rates sharply; (2) Sportswear Inflects earlier than expected (Q1 FY2027 orders improve materially due to World Cup halo); (3) China partnership restructuring delivers a real channel change that stabilizes revenue in FY2027.
Honesty check: the correct call here is closest to Too-Hard. The swing variable (Sportswear/Jordan sell-through trajectory) is genuinely unforecastable before H2 FY2027 retail reads, and the expected value calculation is close enough to symmetric (+5% annualized in the base case, +18% bull, -15% bear) that a manufactured directional conviction would be false. NEUTRAL with Low conviction is the honest call. The risk/reward in the bull case is attractive, but getting there requires the investor to carry significant uncertainty through at least 2-3 more quarters of below-consensus earnings -- and the 10% required annual return hurdle demands EPS of $2.85-3.14 in FY2028, which requires successful execution of a product-led turnaround in the company’s hardest strategic challenge.
The single highest-conviction sentence: Nike’s performance sports recovery is real and durable, but the company cannot re-rate until Sportswear and Jordan inflect, and that inflection depends on untested product decisions made over the last 18 months that will not reach retail until spring 2027 -- making this a fundamentally forecasting-limited situation until then.