

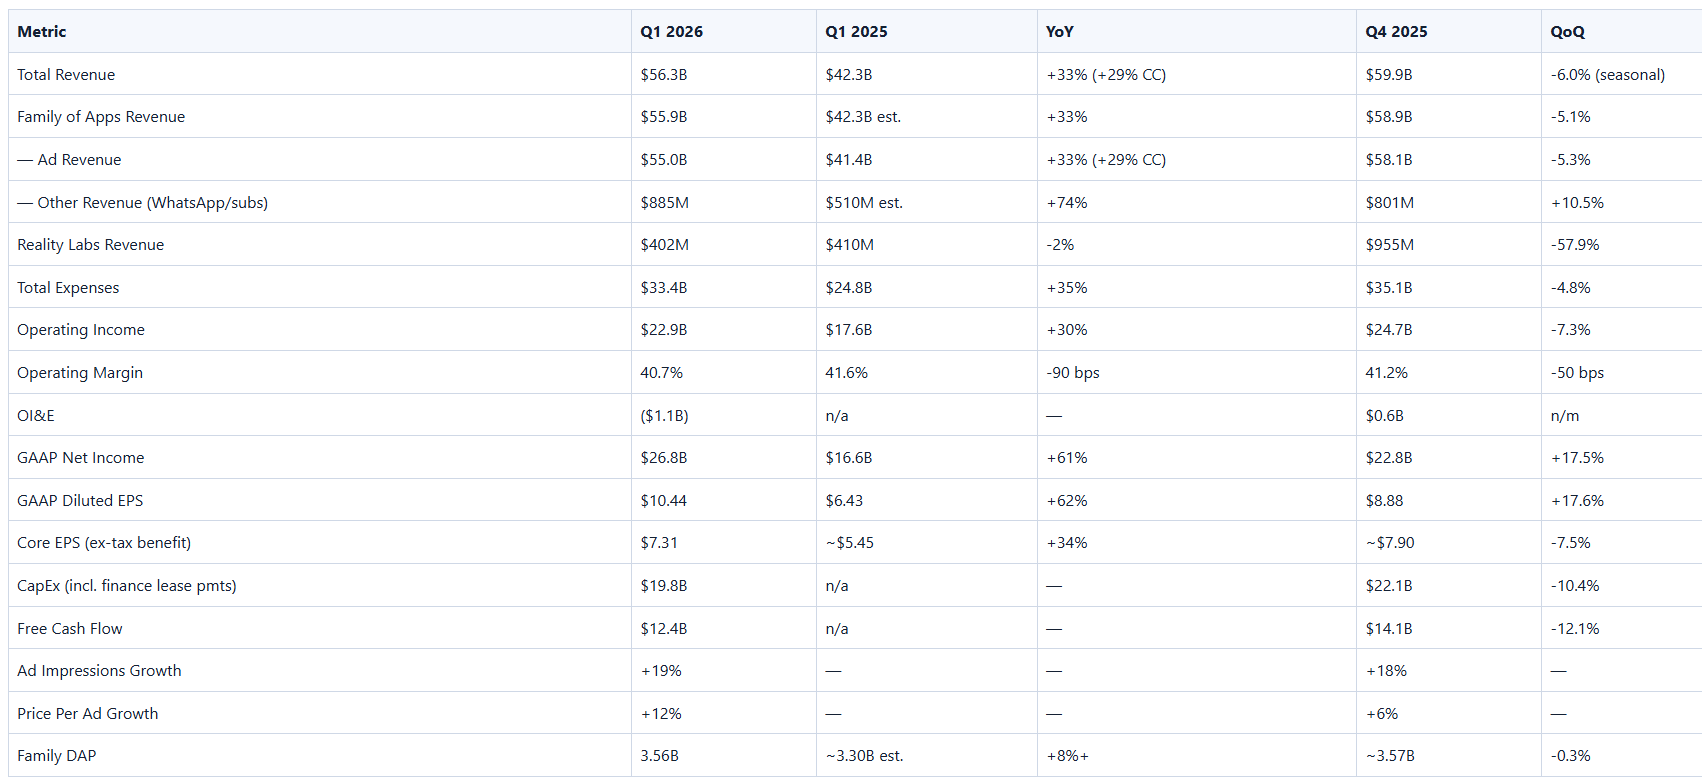
This was the quarter where Meta proved its AI infrastructure spend is compounding into the core business, not just building option value. Revenue of $56.3B hit the top of the $53.5-56.5B guidance range and grew 33% YoY — the fastest quarterly growth rate in four years. Advertising impressions grew 19% and price per ad grew 12% simultaneously, a rare combination that signals real advertiser ROI improvement rather than yield management. Instagram time spent grew 10% from ranking improvements alone in a single quarter. Business AIs went from 1 million to 10 million weekly conversations since the start of 2026. The value optimization suite crossed a $20B annual revenue run rate. Against all of this, the company raised its FY2026 CapEx guide by $10B at the midpoint (to $125-145B), primarily due to memory component price inflation, and announced a headcount reduction in May.
The headline EPS of $10.44 is not the operating number. It embeds an $8.03B one-time tax benefit (partial reversal of Q3 2025’s $15.93B noncash tax charge). Core EPS is $7.31. Even that contains -$1.1B OI&E from unrealized equity investment losses. True operating EPS is approximately $7.68.
The investment question at $669: you are buying a 3.56B-daily-user attention machine operating at 41% margins in its current quarter, growing 33% YoY, at approximately 18.3x forward earnings (18-19x NTM operating income) — a multiple that has barely moved in twelve months while the underlying earnings power grew 21%. The bull case is a compounding flywheel: more engagement → more impressions → higher pricing through AI-optimized ad matching → expanding contribution margins from WhatsApp/Business AI eventually monetized. The risk is the FY2026 margin compression is larger and more persistent than guided as D&A accelerates on the CapEx ramp, and that personal superintelligence remains vaporware through most of the year.
Headline Financials
What Was New This Quarter
CapEx Raised — Third Consecutive Quarter of Escalation
FY2026 CapEx guide moved from $115-135B (Q4 2025 guide) to $125-145B — a $10B midpoint increase. The stated reason is specific: “higher component costs, particularly memory pricing.” To a lesser extent, additional data center costs to support future-year capacity.
This matters because it is not demand-driven; it is cost-inflation driven. Memory is a commoditized input. If DRAM prices normalize in H2 2026, the CapEx rationale for the $10B increase disappears and FCF could recover. Conversely, if memory stays elevated (NVIDIA HBM allocation constraints, SK Hynix/Micron capacity), the inflation persists.
The FY2026 CapEx range of $125-145B compares to FY2025 actual CapEx of approximately $44B (Q4 2025 was $22.1B; H1 2025 was lower). The YoY increase is roughly 200%+. This is the single largest CapEx escalation in Meta’s history, funded by OCF plus the Q4 2025 bond issuance.
Full-year expense guide unchanged at $162-169B despite the CapEx raise — because CapEx is a balance sheet item; the expense impact flows through depreciation (D&A), which lags CapEx by 12-24 months. The D&A acceleration hits income statements in Q3-Q4 2026 and especially FY2027.
Muse Spark and Meta Superintelligence Labs — First Operational Quarter
MSL launched ~10 months ago (mid-2025). Muse Spark is its first model, now powering Meta AI across all apps. Measurable traction:
“Double-digit percent increases in Meta AI sessions per user” since Muse Spark rollout
“Large increases” in Meta AI use overall
Meta AI app “consistently near the top of the app stores”
Health, shopping, visual understanding, local, and social content named as leading areas
The critical question is: does Muse Spark represent a genuinely world-class model (as Zuckerberg claims) or is this Meta-grade spin? The external evidence available: meta AI app store rankings, and the engagement metrics (+double-digit sessions per user on a 3.56B daily user base) suggest real product-market fit improvement. Zuckerberg’s framing — “now that we have a strong model, we can develop more novel products” — signals the team views Spark as an unlock, not an endpoint. More advanced models are already in training.
Business AI Scale — 10x Growth in 4 Months
Business AIs weekly conversations: 1 million at start of 2026 → 10 million in Q1 2026. This 10x increase occurred entirely within a single quarter. The AIs are on WhatsApp (expanded to Latin America, Indonesia), Messenger (Asia Pacific), and being expanded globally in Q2.
Key detail often missed: Business AIs are currently free for most businesses on messaging apps. The monetization model is not established. When it is, Susan Li’s framing — “we’ll work towards establishing a longer-term monetization model” — is deliberate understatement. At 10M+ weekly conversations with millions of SMBs, a subscription model of even $10-25/business/month represents billions of ARR. The conversations per week metric is the right leading indicator to track.
Value Optimization Suite and Partnerships Ads — Hidden Scalers
Two product lines that are growing faster than the core ad business and deserve model attention:
Value Optimization Suite: Annual revenue run rate now >$20B, doubled YoY. This product helps advertisers optimize for highest-value conversions rather than volume. High-value customers in automotive, luxury, financial services are willing to pay premium CPMs for conversion quality. As more advertisers adopt value optimization, Meta’s average revenue per ad increases without needing more inventory.
Partnerships Ads (creator commerce): Annual revenue run rate now $10B, more than doubled YoY in Q1 2026. This product allows brands to amplify creator content as ads. Meta is now extending this into an affiliate commerce model where creators tag products and earn commissions — testing on Facebook, beginning to test on Instagram. This is a different business model than standard display advertising: it creates a creator-Meta-brand three-way relationship with higher engagement and conversion than cold ads.
Combined, these two products represent a $30B run-rate that is growing faster than the 33% YoY revenue base rate. If both continue doubling, they could represent $55-60B combined by end of FY2026 — roughly 22% of projected total revenue from products that barely existed in 2024.
Adaptive Ranking Model — The Trillion-Parameter Ad Engine
Susan Li disclosed that the adaptive ranking model — launched H2 2025 and now expanded to cover off-site conversions — uses 1 trillion parameter model complexity for ad inference. This is technically remarkable because historically Meta couldn’t use LLM-scale models for inference due to latency requirements. The breakthrough: co-designed silicon architecture that maintains sub-second ad delivery at trillion-parameter scale.
Effect in Q1 2026: +1.6% conversion rate across major Facebook and Instagram surfaces. That doesn’t sound impressive until you scale it: on a $55B annual ad revenue base, 1.6% conversion improvement that flows through to higher CPMs and ROAS is worth approximately $800M-1B in annual incremental revenue. And this is Q1 application only — coverage will expand throughout 2026.
The combination of adaptive ranking model expansion + GEM scaling + Lattice model unification is not a one-time conversion lift — it is a compounding infrastructure that continues to improve as it is trained on more data and expanded to more surfaces.
Headcount Reduction in May — Operating Efficiency Signal
Susan Li: “We recently shared internally that we plan to reduce the size of our employee base in May.” Meta ended Q1 with 77,900 employees, down 1% from Q4’s 78,800. The May reduction is on top of this. She framed it as enabling “a leaner operating model” to “move more quickly.”
Contextually, this is a meaningful signal on two fronts: (1) Meta believes AI coding tools and agentic workflows are reducing the marginal productivity cost per engineer (she cited 30% output increase per engineer since 2025 start); and (2) headcount costs are the second-largest expense line after infrastructure. Any reduction creates operating leverage against the revenue growth.
What the Market May Be Missing
The Engagement Math Has Changed Structurally
Instagram +10% time spent from Q1 ranking improvements. Facebook video +8% globally, +9% in US/Canada. Same-day posts now >30% of recommended reels (doubled YoY from AI freshness improvements). At 3.56B daily users, a 10% engagement improvement on Instagram alone represents a material inventory expansion.
The mechanism: Meta doubled the “user interaction sequence length” used for training on Instagram in Q1. Longer sequences = the model understands each user’s interest profile with more depth = better recommendations = more time spent = more ad impressions served. This is not a one-time improvement — doubling the sequence length is a foundational model change that continues to compound as more data flows through the longer context window.
Susan Li’s response to the Ron Josey question on whether diminishing returns have set in was unambiguous: “there is still a lot of room to continue improving recommendations over the rest of the year.” She specifically cited: (1) redesigning the content retrieval system for better diversity/personalization; (2) scaling up model complexity further; (3) deeper LLM incorporation for fresh content understanding. The engagement roadmap is multi-year, not mature.
FY2026 Margin Compression Is a D&A Artifact, Not a Business Deterioration
Operating margin in Q1 2026: 40.7%. Full-year 2026 implied operating margin (revenue ~$240B, expenses $165.5B midpoint): ~31%. That is a 950-basis-point full-year margin compression vs. Q1. Where does it come from?
The answer is almost entirely depreciation. Meta is putting $125-145B of CapEx to work in FY2026. Assets from this spend depreciate on 3-7 year schedules depending on type (servers vs. buildings). As FY2025’s massive CapEx ramp ($44B+) begins depreciating in H2 2025 and FY2026, and FY2026’s even larger CapEx adds to the base, D&A will step up from ~$22-24B in FY2025 to potentially $35-40B in FY2026 and $50B+ in FY2027. This is a non-cash charge that temporarily compresses GAAP margins while the physical infrastructure is being used to generate revenue.
EBITDA margins are a cleaner signal: Q1 2026 EBITDA (~$22.9B OI + ~$6B D&A = ~$28.9B) / $56.3B = 51.3% EBITDA margin. This is essentially flat with prior quarters and shows no fundamental business deterioration. The P&L margin compression is an accounting artifact of CapEx timing.
Investors who sell META on “margin compression” are pricing in permanent impairment when the actual mechanism is temporary accounting absorption of infrastructure investment.
WhatsApp Monetization Is Being Priced at Zero Against 2B Daily Users
WhatsApp crossed $2B annual paid messaging run rate in Q4 2025. Status ads now reach hundreds of millions daily viewers and are being rolled out to all remaining markets (UK, EU, Brazil) in Q1 2026. Business AIs are reaching 10M+ weekly conversations and will be globally expanded in Q2.
At 2B+ daily users (meta cited 2B daily WhatsApp actives on Q4 2025 call), WhatsApp is the second-largest daily social platform in the world after Facebook. Yet WhatsApp contributes a negligible fraction of Meta’s $55B quarterly revenue.
The monetization gating: ad format development and user experience preservation. Meta historically applies its standard approach — optimize formats and performance before scaling inventory. WhatsApp status ads are at “low levels” for now. But the infrastructure is built. The advertiser demand is demonstrated. The business AI conversations are scaling 10x per quarter. The path from ~$2-3B WhatsApp revenue run-rate to $10-15B by FY2027-2028 is more credible today than it was six months ago — and none of this is in consensus estimates.
The Valuation Multiple Has Been Essentially Unchanged While Earnings Grew 21%
One year ago (April 30, 2025), META closed at $547.29. Today it is $669.12, up 22%. But LTM operating income grew from ~$73B to ~$88.6B, or 21%. The EV/LTM OI multiple has barely moved: ~18.3x in April 2025 vs. ~19.1x today.
The stock has “earned into” its current price without any multiple expansion. A business growing operating income at 21% without multiple expansion — and with a $30B product suite doubling YoY and WhatsApp monetization not yet material — is an interesting setup. The market appears to be pricing the FY2026 CapEx escalation and D&A acceleration correctly (suppressing the multiple), but may be underpricing the FY2027 operating leverage as D&A growth plateaus and the AI ad stack generates higher monetization per impression.
Call / Filing Nuggets That Matter
“More than a 6% increase in conversion rate for landing page view ads” — from Lattice modeling + GEM architecture improvements combined in Q1. Combined with the adaptive ranking model’s +1.6% off-site conversion improvement, Meta’s ads delivered meaningfully better ROI to advertisers in Q1. Higher ROAS → advertisers bid more aggressively → higher CPMs → revenue growth without volume needing to increase. This is the mechanism behind the simultaneous 19% impression growth + 12% price growth.
“Over half a billion users on each of Facebook and Instagram are now watching AI-translated videos weekly.” That is 1+ billion users engaging with AI-translated content. This is the single most concrete evidence that AI is expanding the content consumption surface rather than cannibalizing it. Content that was inaccessible due to language barriers is now monetizable. This is a $3-5B revenue opportunity over 3-5 years that is not in any model.
Manus acquisition: “We’re still working through the details, so we don’t have an update right now.” Manus is an agentic AI startup that Meta had reportedly approached. Susan Li explicitly confirmed awareness of the deal and that it’s ongoing but not complete. Manus integration into Meta’s ad/business manager would give millions of businesses a productivity agent — potentially the most direct path to Business AI monetization in 2027.
“We recently shared internally that we plan to reduce the size of our employee base in May.” This is the first explicit announcement of a layoff since the 2022 “Year of Efficiency.” Unlike 2022, this is not distress-driven — it is being framed as deliberate AI-driven productivity capture. The impact on operating expenses is meaningful: technical employee compensation averages $300-500K all-in; even 5% headcount reduction (3,895 employees) = $1.2-1.9B in annualized compensation savings, offsetting a portion of the CapEx-driven D&A increase.
“Our adaptive ranking model... LLM scale model complexity of 1 trillion parameters... maintains the subsecond speed required to serve ads at scale.” Susan Li’s technical disclosure is unusually specific. A trillion-parameter inference model for real-time ad serving is architecturally unprecedented. The co-design with silicon (NVIDIA, AMD, MTIA) to enable this at millisecond latency is a proprietary technical moat that took years to build. No other ad platform can run inference at this complexity in real-time. The performance gap between META and the industry is widening, not narrowing.
“Same day posts now representing more than 30% of recommended reels on both Instagram and Facebook, more than double the levels one year ago.” This is the freshness improvement. A year ago, 85% of recommended content was older content. Now 30%+ is same-day. This increases engagement (users see relevant current events, trends) and increases ad load optimization flexibility (more fresh content = more insertion points). It also increases creator incentive to post (faster distribution = faster monetization) — a flywheel that Meta has validated.
“These multi-year cloud deals and our infrastructure purchase agreements drove a $107 billion step-up in our contractual commitments this quarter.” Meta now has substantial long-term infrastructure commitments — unlike cloud providers who sell contracted revenue, Meta is buying contracted supply. This $107B step-up secures compute access through FY2027+ but creates a balance sheet obligation regardless of demand outcomes. It is the other side of GOOG’s $462B cloud RPO — Meta is a buyer, not a seller.
Reality Labs glasses: “daily use tripling year-over-year.” The engagement metric is strong even if revenue ($402M) is weak. Users who try AI glasses and find daily utility are the early adopter cohort who will drive the next generation of hardware. The “Ray-Ban Meta Optics” (designed for all-day wear, not just sun protection) is the first product designed specifically for daily use cases beyond fashion/sun protection — a significant positioning shift.
2nd-Order Implications
For Q2 2026
Revenue trajectory: Q2 guidance of $58-61B (midpoint $59.5B) vs. Q1’s $56.3B implies +$3.2B sequential growth. FX tailwind reduces from 4% (which benefited Q1’s YoY comparison vs. Q1 2025) to 2%. Organic revenue acceleration must carry more weight. Given impression growth (+19%) and price improvement (+12%) momentum, this is achievable if advertisers hold firm through April.
FX tailwind fading: Q1 had 4% FX benefit; Q2 guide assumes 2%. On ~$56B revenue, 2pp less FX = ~$1.1B headwind that must be replaced by organic growth. This explains why Q2 guide of $58-61B appears conservative relative to Q1’s trajectory — it is absorbing the FX fade.
GAAP EPS optics in remaining 2026 quarters: Tax rate guided 13-16% for Q2-Q4, reversing from Q1’s negative 23%. More importantly, there will be no recurrence of the $8.03B tax benefit in Q2-Q4. If Q2 core operating EPS is ~$7.50-8.00 (reasonable on $20-22B operating income), GAAP EPS appears to “decline” from $10.44 to ~$7.50-8.00. Investors who benchmark against the GAAP headline will misread this as deceleration.
Margin compression begins: Q1 was 40.7% operating margin. Q2-Q4 will see D&A step up materially as FY2025’s Q3-Q4 CapEx (very large quarters) begins depreciating. Expect Q2-Q3 2026 operating margins in the 33-38% range. The H2 margin trajectory depends on whether headcount reduction savings, model efficiency gains, and revenue acceleration offset D&A.
For the Next 12 Months
The engagement compound is accelerating into the ad engine. Q1 2026 showed that ranking model improvements directly translate to engagement, which directly translates to impression supply, which the adaptive ranking model monetizes more efficiently. This is a compounding three-stage flywheel that is just entering its most powerful phase as LLM-scale inference models reach all major surfaces (GEM covering all major surfaces + adaptive ranking at 1T parameters + longer sequence training). The impression×price matrix in FY2027 could drive 20-25% revenue growth even with flat user count.
WhatsApp’s monetization clock is accelerating. Paid messaging at $2B+ run rate (Q4 2025). Status ads expanded globally. Business AIs at 10M weekly conversations. These are sequential milestones, not parallel initiatives. The status ads monetization is the highest-scale opportunity: Meta is explicitly managing ramp speed to preserve user experience, but the inventory exists and advertisers are already testing. WhatsApp revenue could be $5-8B by end of FY2026 and $12-15B by FY2027. This is essentially zero in consensus.
Estimate revisions will be two-sided through the year. Buy-side will: (a) raise FY2026 revenue by $3-5B on Q1 beat; (b) raise FY2026 operating income above $83B floor; BUT ALSO (c) raise CapEx by $10B at midpoint; (d) lower FY2026 FCF materially (from ~$30-40B expectations to potentially $15-25B); (e) push back on multiple expansion given FCF compression. The revenue/OI revision is up; the FCF revision is sharply down. The valuation debate will increasingly center on whether you pay for EV/OI or EV/FCF.
The “AI replacing workers” narrative has first confirming evidence at Meta. +30% output per engineer since Q1 2025, with power users at +80% output. Headcount reduction announced in May. This is not theory — it is Meta’s operational data. If engineering output per head continues increasing at this rate through FY2026, Meta can grow its product surface area without proportional headcount increases. The operating leverage implications for FY2027-2028 are significant: revenue scaling at 20%+ YoY while headcount grows 2-3% implies dramatic expansion in OI per employee.
RL losses trajectory matters for the FY2027 margin outlook. Zuckerberg said at Q4 2025 that RL losses in 2026 would be “similar to last year” and that “this will likely be the peak as we start to gradually reduce our losses going forward.” FY2025 RL losses were approximately $17-18B. If FY2026 is also ~$17-18B and FY2027 begins declining, the margin headwind from RL reverses into a tailwind for the first time in five years. The compound effect: Family of Apps margin expansion (from AI efficiency) + RL loss reduction = potential 37-40% consolidated margin in FY2027 vs. ~33% in FY2026.
Regulatory risk is real and underappreciated by bulls. Susan Li’s closing remarks mentioned “youth-related issues” with “additional trials scheduled for this year in the US, which may ultimately result in a material loss.” The EU continues to create headwinds. The less-personalized ads offering being rolled out in Europe is a direct monetization constraint — personalized ads command 3-5x higher CPMs than generic ads. If the EU framework spreads geographically (GDPR-style export), the monetization ceiling for international markets lowers. This is the single risk not adequately captured in consensus revenue models.
What Matters Next
Q2 2026 revenue within the $58-61B guidance range — specifically whether growth ex-FX accelerates or decelerates. If Q2 revenue exceeds $61B (top of range), the engagement + ad performance flywheel has broken above what management modeled. If it comes in below $59B (miss vs. midpoint), it signals either FX headwinds were underestimated or advertiser budgets cracked in April.
Operating margin in Q2-Q3 — the first two quarters of the D&A acceleration phase. If margins hold above 35% despite the D&A step-up, it indicates revenue outpacing cost inflation. If margins compress to 30-32%, the EV/EBITDA argument for the stock weakens as the non-cash expense drag is larger than expected.
WhatsApp status ad ramp quantification — management has been deliberately vague on WhatsApp revenue composition. The next concrete milestone would be disclosure of a WhatsApp ad revenue run rate (currently embedded in “other revenue” which was $885M in Q1 2026, up 74%). A $1.5-2B quarterly run rate on WhatsApp ads alone would be a meaningful catalyst.
MSL / Muse Spark follow-up model release — Zuckerberg said “we are already training even more advanced models.” The next MSL model release (potentially by mid-2026) and its performance vs. frontier models (Gemini, GPT-5, Claude) will determine whether Meta’s “personal superintelligence” thesis is credible or aspirational. Model quality is the gating factor for Meta AI becoming a monetizable product.
May headcount reduction scope — the size of the reduction (not yet disclosed) will be revealed through Q2 press coverage and the Q2 results. A 5-10% reduction (4,000-8,000 employees) would produce $1.5-4B in annualized cost savings and demonstrate management conviction in AI productivity replacement. A smaller reduction (<2-3%) would suggest it was more symbolic than structural.
Manus acquisition completion — if and when announced, the integration strategy for Manus (agentic AI platform) into Meta’s ad/business ecosystem will clarify how quickly Business AI can transition from free conversations to paid professional tier.
EU regulatory developments — any ruling on the less-personalized ads offering’s scope or expansion will move the stock. A favorable ruling (Europe accepts personalized ads with consent) removes the EU overhang. An adverse ruling (forced generic ads for all users) would require revenue model estimates for Europe to be cut by 30-50%.