

Call: LONG | Conviction: Med
Q3 FY2026 was the quarter that settled the most important debate about FactSet: whether AI is disrupting the business or powering it. The answer this quarter is unambiguously the latter. Organic ASV growth accelerated for the fifth consecutive quarter to 7.1% -- the highest rate since Q1 FY2024 -- while 90%+ of the top 50 clients now use four or more AI products, enterprise contracts extended 30% in duration with no price concessions, and management said on the call it is tracking toward the high end of FY2026 guidance. These are not defensive-hold metrics. They are growth re-acceleration metrics.
The complexity is the margin line. Adjusted operating margin fell to 34.0% (vs. 36.8% a year ago and 35.0% in Q2 FY2026), partly from structural investments, partly from performance incentives tied to ASV outperformance, and partly from an FX hedging program that swung from a gain to a loss (60bps drag alone). These are real expenses but most are non-recurring or cyclical. The 10% tech workforce reduction completed in early Q4, combined with data operations productivity (50% reduction in operator touch time for table extraction) and AI-assisted coding (27% of committed code now AI-authored), lays the groundwork for FY2027 margin recovery that the Street has not yet fully priced in.
The stock is cheap. At 12.6x FY2027 consensus adj. EPS and approximately 9x forward EV/adj. EBITDA, FDS is priced for steady but unexciting results -- not for re-acceleration. The re-rating from here depends on one variable: whether the Q3 ASV momentum is the beginning of a sustained 7-9% growth cycle or a peak that moderates as the investment banking renewal cycle normalizes. If it sustains, the stock is worth $320-360 in three years. If growth softens back to 4-5%, the stock likely re-tests $200.
Position Verdict (1-3 Year View)
Call: LONG | Conviction: Med | Horizon: 1-3yr | One-line thesis: FactSet’s AI-enabled data infrastructure position is re-accelerating ASV growth while the market still prices the stock as a seat-count business facing disruption -- the mispricing closes via estimate revisions and a multiple re-rate as margin recovery materializes.
A. Business and Industry Trajectory (1-3yr)
FactSet operates in the institutional financial data and analytics segment, a market with structural growth driven by increasing data complexity, regulatory reporting demands, and now AI adoption at financial institutions. The segment is oligopolistic (Bloomberg, Refinitiv/LSEG, FactSet, MSCI, S&P Global Intelligence) with high switching costs and long tenure relationships -- FactSet’s 16-year average client relationship and 95%+ ASV retention are structurally high barriers.
Over 1-3 years, the most important industry trajectory is the shift from terminal/seat-based access to data-API/machine-readable delivery for AI workflows. This transition is creating a bifurcation: incumbents with high-quality, connected, and governed financial data (FactSet, Bloomberg) gain as AI demand for clean, auditable, entity-resolved data grows. Pure terminal players face headwinds as analyst headcount is reduced in favor of AI agents. FactSet is positioned in the favorable cohort: 90%+ of clients’ AI agents consume FactSet data as primary fuel.
The industry is not at peak cycle -- AI adoption in financial services is early innings. Large institutions are consolidating their AI experiments (FactSet management noted clients coming back to consolidate after exploring multiple horizontal AI solutions). This consolidation dynamic typically accrues to the most embedded, trusted provider. FactSet’s MCP server, portfolio analytics APIs, and workstation access to frontier models position it as the default consolidation destination.
Earnings power in 3 years (FY2028-2029): At 8-9% organic ASV growth, $2.85-3.0B revenue, and 37% adj. operating margin, adj. EBITDA reaches $1.25-1.3B. On 34.5M diluted shares (continuing buybacks), adj. EPS reaches $23-26. This is the realistic bull case, not an aggressive scenario.
B. What’s Priced In vs. Our View (Variant Perception)
What current price requires: At $246.77 and 12.6x FY2027 consensus adj. EPS of $19.54, the market is pricing approximately 3-5% compound adj. EPS growth from today’s base, perpetually, with no multiple expansion. The reverse 10% hurdle requires only $20.55 adj. EPS in FY2028 at a 16x exit multiple -- that is 5.2% compound growth, lower than the consensus 10% FY2026-to-FY2027 step. The market is pricing a business that grows modestly and never earns back its prior-peak multiple.
Our view: At 7%+ organic ASV growth with clear AI monetization evidence and structural productivity improvements building, FDS should deliver 10-12% adj. EPS growth in FY2027-28, not 5%. The margin recovery story (34% -> 36-38%) has quantitative underpinnings (tech headcount reduction, AI-assisted coding, data ops automation) that are in train but not yet visible in the P&L.
The gap: Divergent -- we are more constructive on both earnings power and multiple. The market is priced for “steady but unexciting”; we see “re-acceleration with margin recovery.”
Why the mispricing persists: Two mechanisms. First, the 20% stock decline from June highs to June 25 lows was driven by technical/positioning dynamics (hedge funds likely short the stock as a “AI disrupts financial terminals” thesis) rather than fundamental deterioration. These sellers have not yet fully covered. Second, the headline GAAP results (operating income -14%, GAAP EPS -9.6%) obscure the underlying adj. performance, and investors anchoring to GAAP remain skeptical until 2-3 quarters of adj. margin recovery are visible in the trend. The revenue-ASV lag is also a structural mismatch: the best-forward-looking indicator (ASV) has been accelerating for five quarters, but revenue lags, so the reported numbers look softer than the underlying business.
C. Valuation Cross-Check
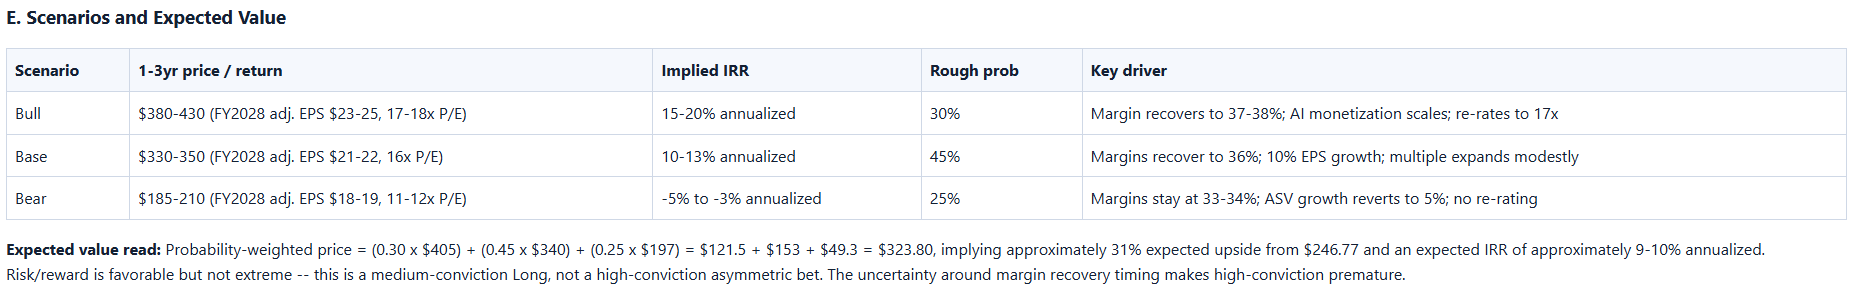
Base case IRR of 11.7% at 16x FY2028 adj. EPS. The return is modestly leveraged to both EPS growth AND multiple expansion -- neither alone is sufficient. The risk/reward is asymmetric: the downside at 12-13x (value trap) = flat to -3% IRR; the upside at 17-20x (re-rating) = 16-22% IRR. The skew is 3:1 to the bull case if the margin recovery thesis is correct. For 10% hurdle clearance, the required EPS of $20.55 in FY2028 is modest and well within the consensus trajectory.
D. Positioning and Catalysts
Positioning is relatively washed-out after the June selloff -- short interest was likely elevated leading into Q3 earnings (consistent with the sharp intraday reversal on July 1) and may be partially covering post-print. The stock is no longer a consensus “safe compound” long (as it was at $430+ peak in 2022) and is not a widely loved growth stock. It is an under-covered recovery situation in the financial data sector.
Dated catalysts over the holding period:
Q4 FY2026 earnings (late September 2026): Primary catalyst -- will Q4 adj. operating margin demonstrate the recovery step-change? If yes, the thesis accelerates.
FDS Investor Day (expected FY2027): Medium-term margin and growth targets. If management commits to 36-38% adj. op margin by FY2028, the stock re-rates meaningfully on the day.
FY2027 H1 earnings (Q1 in December 2026, Q2 in March 2027): Progressive evidence of margin recovery from the tech workforce reduction and productivity initiatives.
Potential M&A (low probability but not zero): New CFO with BlackRock strategy background; “surgical” acquisition philosophy. Any M&A that deepens data capabilities without materially impairing FCF would be positive.
Without Investor Day timing visibility, the key risk is that the re-rating trade requires patience over 2-3 quarters before the margin evidence is visible.
F. What Breaks the Call
Disconfirming evidence to watch:
Q4 FY2026 adj. operating margin below 35% -- implies the cost reductions are not flowing through and performance incentives are permanently embedded.
Organic ASV growth reverting below 6.5% in Q4 FY2026 or Q1 FY2027 -- signals the Q3 acceleration was driven by deal-timing rather than secular demand improvement.
Announced material M&A at a price that significantly impairs FCF yield -- new CFO looking to make a mark.
A significant new client churn event among top-20 clients -- would shake the 95%+ retention narrative.
Too-Hard honesty check: The margin recovery variable is uncertain and has a 3-year horizon. However, the evidence base (tech headcount cuts, AI coding productivity, data ops efficiency) is concrete and the direction is clear. The expected value calculation shows a positive skew. This is not a symmetric “coin flip” situation -- it is a fundamentally improving business at a compressed multiple with a real catalyst (margin recovery + Investor Day).
What Was New This Quarter
The following items were genuinely new, not repeats of prior-quarter narrative:
1. Fifth consecutive quarter of ASV acceleration -- and it is broadening. Organic ASV growth reached 7.1%, up from 6.7% in Q2 FY2026 and from approximately 4.6% in Q3 FY2025. This represents more than 250 basis points of acceleration vs. the prior-year comparable. Crucially, growth was positive and accelerating across all three geographies (Americas +7.2%, EMEA +5.6%, APAC +10.0%) and all four client categories. Prior prints showed pockets of weakness in institutional buy-side; this quarter the buy-side accelerated to 6% organic ASV growth.
2. Management explicitly said it is tracking to the high end of guidance. This is a meaningful language shift. Prior quarters were “reaffirm guidance.” This quarter: “On revenue and EPS in particular, we are tracking toward the high end of those ranges based on our business trajectory.” At the high end, FY2026 adj. EPS is $17.75 vs. consensus at $17.72 -- but the signal is directional, not quantitative.
3. Google Cloud partnership announced, expanding distribution and cutting token costs. FactSet will embed Gemini capabilities in its workstation, bring financial intelligence into Gemini Enterprise, and receive preferential token pricing as part of the arrangement. New CFO Warren confirmed the Google deal reduces token costs, which had been a growing expense line. The partnership is both a product enhancement and a cost-structure improvement.
4. New CFO Joshua Warren’s first earnings call. Warren (effective April 13; formerly CFO of Envestnet and senior strategy at BlackRock) framed three priorities: client franchise durability, operating leverage, and balance sheet flexibility. His opening framing was more capital-allocation-forward than Helen Shan’s historic style -- he explicitly mentioned the capital allocation framework and the discipline around excess free cash flow. This is worth monitoring for M&A signaling.
5. Completed a 10% technology workforce reduction and began data operations streamlining. Previously announced, now completed. This removes a future restructuring-charge risk and gives Q4 and FY2027 the benefit of a lower tech headcount run-rate. The coding agent rollout (27% of code AI-authored) enabled this reduction without cutting capacity.
6. Disclosure change: client count and user count removed from standard metrics. Stifel analyst Shlomo Rosenbaum flagged this on the call. Management disclosed that user count is +12% YoY (available in the 10-Q) but explicitly deprioritized this as a leading indicator going forward. The shift from seat-count to enterprise-agreement metrics is a deliberate strategic pivot -- but it also removes a historically visible headwind indicator.
7. Contract terms extended 30% in duration with no price concessions. The majority of ASV renewed in Q3 was in enterprise agreements or 3-year-or-longer deals. Management confirmed no price compression in exchange for longer terms. This is structurally significant: it locks in the 95%+ retention dynamic for longer forward periods and reduces churn risk.
8. Over 10% of Q3 ASV growth directly attributable to AI SKUs. From near-zero a year ago. Management also noted that when MCP is part of a client deal, contract value improves ~90% of the time, and that ASV growth among AI-adopting clients runs 50% higher than for the rest of the book.
Call / Filing Nuggets That Matter
Current portion of debt is $499.2M as of May 31, 2026. This is a large current liability, almost certainly the revolving credit facility, likely maturing in FY2026. This will need to be refinanced or repaid. Management said in the call it is “continuing to assess opportunities for optimizing our debt maturity profile” and that Fitch reaffirmed investment grade with stable outlook. Gross leverage is 1.5x, net leverage 1.2x -- manageable but not immaterial against a $288M cash position. Watch for refinancing terms, especially given the high-rate environment.
GAAP operating margin fell to 26.7% -- a 650bps gap to adjusted at 34%. The gap is unusually wide. The non-recurring items in Q3 FY26 include $19.6M in restructuring/severance, $4.3M in CEO one-time compensation make-whole awards (recognized over service periods), and $0.75M in client bankruptcy charges. Most of these are genuinely non-recurring, but the CEO compensation item will continue to appear each quarter throughout its vesting schedule. This distorts GAAP comparisons for several more quarters.
Performance incentives tied to ASV outperformance are compressing near-term margins but confirm management credibility. The CFO explicitly stated: “Compensation related expenses were driven by performance incentives linked to the ASV acceleration delivered, not additional headcount.” This is pay-for-performance discipline, not cost-control failure. The counter-argument -- that margins will only recover if and when ASV growth eventually slows -- is worth holding.
FX hedging program swung from a gain to a loss, creating approximately 60bps of margin drag in Q3. This is an accounting/timing effect, not an operating deterioration. It will eventually normalize. It partially obscures the true operating margin trend.
Revenue of $622.9M reflects a 1-2 quarter lag behind ASV. New ASV bookings hit revenue only after contracts commence, spread over their term. With ASV having accelerated each quarter for five straight quarters, the strongest revenue tailwind is in front of FactSet, not behind it. Q4 FY26 consensus is $628.9M and Q1 FY27 consensus is $642.6M -- both would represent sequential acceleration consistent with the ASV curve.
MCP API call volume in Q3 was 13x the Q2 level. This is an extraordinary metric. 450+ clients on MCP contracts or trials. The compounding nature of API volume growth (each new data product added to MCP expands the addressable call volume) suggests this metric has not plateaued. Importantly, this is not seat-count expansion -- it is a genuinely new consumption channel generating incremental ASV on top of existing subscriptions.
Share count declined 6% YoY. Q3 FY26 diluted weighted-average shares = 36,191K vs. 38,344K a year ago. The company bought back 926K shares for $203M in Q3 at an average of $219.21 -- approximately 12% below the current price. YTD buybacks through Q3 total ~$506M. At current pace, the share count will exit FY2026 around 35.5-35.8M, providing meaningful per-share EPS tailwind even in flat-earnings scenarios.
Q&A Tension:
The two most probing exchanges on the call:
Jason Haas (Wells Fargo) on the Q4 margin math: Haas noted that if FDS tracks to the midpoint of FY2026 guidance, Q4 adj. operating margin would need to improve “pretty nicely” relative to Q3’s 34.0%. He asked specifically whether there was a comp pull-forward from Q4 into Q3. Management’s answer was evasive: Viswanathan said “we have a big quarter ahead of us” and that they’re retaining “flexibility in the margin range” if ASV momentum continues. Warren added a “clear path to expanding margins” but gave no quantification. The honest read: Q4 margin improvement requires either a step-down in performance incentives (possible if ASV growth normalizes toward quarter-end) or a step-up in operating leverage that hasn’t yet fully materialized. The math implies Q4 adj. operating margin needs to reach approximately 36-37% for FDS to hit the guidance midpoint -- a large sequential improvement from 34%.
Shlomo Rosenbaum (Stifel) on the metric disclosure change: Rosenbaum directly called out the removal of client count, user count, and employee count from standard disclosures. Warren said user count is in the 10-Q and is +12% YoY but that seat-count “tends to be in the long tail and not really flows through to revenue or profitability.” This is management signaling a deliberate move to enterprise-agreement framing where aggregate client count matters less than total ASV per client. The bear case on this: if growth does soften and management no longer reports these indicators, the early-warning signals for deterioration disappear from the public data set.
What the Market May Be Missing
1. The ASV-to-revenue lag makes the fundamental improvement look worse than it is. Organic ASV of $2,485.6M grew 7.1% YoY. Revenue of $622.9M grew 6.4% -- approximately 70bps slower. This gap is structural: revenue is recognized over the subscription term, so new bookings appear in revenue over the coming 3-12 months (or longer for multi-year deals). With ASV having accelerated for five consecutive quarters, the revenue recognition tailwind is compounding into FY2026 Q4 and FY2027. The market is anchoring on the trailing revenue rate, not the forward ASV pipeline. At 7%+ organic ASV growth, FDS’s FY2027 revenue consensus of $2.61B (5.7% growth) is likely conservative and will be revised upward as ASV data through Q4 is reported.
2. The shift from seat-based contracts to enterprise agreements with consumption upside is a structural upgrade in the business model, not a risk. The market appears to discount enterprise agreements as “soft” commitments. In practice: (a) minimum commitments preserve the subscription base; (b) consumption-based tiers capture upside from AI-driven data usage, which is real and growing (MCP API volume 13x in one quarter); and (c) longer contract durations reduce annual renewal risk. This transition should command a higher multiple over time, not a lower one.
3. Token cost inflation is real but is being partly offset by the Google partnership economics. The CFO explicitly cited growing token costs as a margin headwind but also confirmed the Google Cloud partnership provides “preferential pricing” on Gemini models. The net token cost trajectory is not visible in current reported margins, but the benefit of the Google deal should materialize in Q4 FY2026 and into FY2027. Token costs are being treated by the market as a permanent margin headwind; they may prove to be a pass-through cost as clients pay for AI-enhanced outputs.
4. The multiple is at or near historical lows relative to business quality. FDS at ~14x FY2026 adj. EPS and ~12.6x FY2027 consensus is near the lowest valuation the stock has traded at on an earnings power basis since the post-2008 period. MSCI -- a comparable B2B financial data business -- trades at 25-30x forward earnings with 53-59% EBITDA margins. FDS’s margin structure is lower (34-38% adj. operating margin), but the 95%+ ASV retention, 16-year average client tenure, and 7%+ growing ASV base are not structurally inferior to MSCI’s analytics subscription business. The 50-60% multiple discount to MSCI may be appropriate at 4-5% ASV growth; at 7-9% growth with margin recovery, it is not.
2nd-Order Implications
Chain 1: ASV acceleration + 50% higher growth among AI clients -> revenue revision cycle
Reported fact: Organic ASV grew 7.1%; clients using AI solutions grow ASV 50% faster than non-AI users.
Immediate implication: As AI adoption penetrates from 90% of top-50 clients to a broader share of the 9,100-client base, the incremental ASV growth rate compounds.
2nd-order consequence: Street consensus for FY2027 revenue ($2,607M, +5.7%) will need to be revised upward as Q4 FY2026 ASV data arrives and the high-end guidance signal firms up. First estimates for FY2027 were built when ASV growth was 4-5%; the Street is running roughly 1-2 quarters behind the true underlying growth rate.
Thesis relevance: Upward estimate revisions are the catalyst that closes the gap between FDS’s current multiple and what the business should earn. This chain makes FDS an estimate-revision story, not just a valuation-discount story.
Chain 2: Enterprise contract term extension + minimum commitment structure -> retention stability floors
Reported fact: Contract terms extended 30% in Q3, majority renewed as enterprise agreements, no price concessions.
Immediate implication: Clients who signed 3+ year enterprise deals in Q3 are contractually locked in with minimum commitments through 2029. These deals are largely immune to near-term seat-count reduction risk from AI automation.
2nd-order consequence: The risk that AI automates analysts out of their seats (reducing FDS’s seat-based revenue) is partially neutralized for the enterprise cohort. The remaining risk migrates to mid-market and small-firm clients who are on shorter-term contracts. But deal-maker clients (banks, PE, corporates) already grew 9% ASV -- suggesting AI is increasing, not reducing, financial data consumption at large firms.
Thesis relevance: The bear case requires re-running the “AI disrupts financial data demand” argument specifically against a client set that just extended its relationship by 30%. That is increasingly difficult to sustain.
Chain 3: Tech workforce -10% + AI coding at 27% of committed code -> structural cost base reduction in FY2027
Reported fact: 10% technology workforce reduction completed; AI-authored code at 27% of committed lines; data table extraction operator touch time reduced by 50%.
Immediate implication: FY2027 will start with meaningfully lower compensation costs (the #1 cost item at ~60% of total costs) than FY2026 annualized run-rate, before any further productivity gains.
2nd-order consequence: Management’s 3-year payback on structural investments starts to flow through the P&L in FY2027-28. If the adj. operating margin can recover from 34% back to 36-38%, FY2027 adj. EPS estimates ($19.54 consensus) may also prove conservative. At even 36% adj. op margin and $2.61B revenue, adj. operating income is ~$940M vs. the $855M midpoint in FY2026 -- a $85M or ~10% incremental swing.
Thesis relevance: The margin recovery trade is the most important valuation catalyst. At 34% adj. op margin, the stock deserves its current 12-14x multiple. At 36-38%, the multiple should expand toward 16-18x, and the combined earnings growth + multiple expansion drives IRR well above 15% from current levels.
Chain 4: MCP API volume 13x QoQ + Google partnership -> consumption-revenue optionality not in current ASV
Reported fact: MCP API call volume grew 13x QoQ; 450+ clients in contracts/trials; 20%+ of net new MCP users are net new to FactSet.
Immediate implication: Volume growth of this magnitude (13x in one quarter) implies a compounding adoption curve that is likely to continue as more data endpoints are added and clients integrate FactSet data into AI agent workflows.
2nd-order consequence: The current ASV base does not fully capture consumption-oriented upside, since most consumption tiers are structured as “minimum + upside.” As clients’ AI agent usage scales, FactSet benefits from consumption overages above the minimums -- revenue that does not yet appear in the $2.49B organic ASV figure. This is an underappreciated optionality premium.
Thesis relevance: The market is valuing FDS as a static subscription business. There is genuine optionality embedded in the consumption tier structure that is worth something beyond the base ASV value. How much is uncertain -- but it is not zero, and the market is treating it as zero.
Chain 5: Estimate revision direction and magnitude
With FY2026 guidance tracking to the high end ($17.75 adj. EPS) and the FY2027 consensus at $19.54 ($19.54/$17.75 = ~10% growth), the Q3 print suggests the FY2027 consensus should drift upward toward $20-21 as: (a) the high-end FY2026 EPS becomes the new base, (b) share count continues declining from the aggressive buyback program, and (c) margin recovery contributes even modestly. Over the next two quarters, the Street will likely revise FY2027 EPS from $19.54 toward $20.50-21.00 -- a 5-7% upward revision that flows directly through to target prices.
Net thesis effect: Thesis strengthens -- this quarter did not just reaffirm the thesis, it provided new quantitative evidence (AI SKU % of ASV growth, MCP volume, enterprise contract length) that supports re-acceleration. The single prior-model assumption change: FY2027 adj. EPS floor moves from $19.54 (consensus) to $20.25-21.00 (our estimate after accounting for high-end FY2026 base and continued buyback benefit). Thesis strengthens -- moderate magnitude.
Valuation
The current multiple is at the lower bound of where FDS has traded in the post-rate-hike period (2023-2026). During the zero-rate period (2019-2022), FactSet routinely traded at 30-40x forward earnings. Post-rate-hike compression pushed the range to 13-22x, with the stock trading near the low end of that range as margin concerns peaked in mid-2026. At 12.6x FY2027 consensus adj. EPS, the stock is discounting a business facing structural headwinds -- the opposite of what the Q3 data shows.
Base case (16x exit P/E, $21.50 FY2028E adj. EPS): Implied 3yr price of $344, for an annualized IRR of approximately 11.7%. This assumes modest EPS growth of ~10%/yr and a modest re-rating from 12.6x to 16x. The 16x exit multiple is conservative by the standards of B2B financial data businesses that sustain 7%+ revenue growth and 35%+ operating margins. MSCI, the closest comparable, trades above 40x forward earnings. The required EPS for the 10% hurdle at 16x exit is only $20.55 in FY2028 -- approximately 5.2% compound EPS growth from the FY2027 consensus -- a very low bar.
The most important variable for return is the exit multiple, not the EPS growth rate. If the market re-rates FDS to 18-20x FY2028 adj. EPS (still a meaningful discount to MSCI) on $21.50 earnings, the stock reaches $387-430, for an IRR of 16-20%. If the multiple stays at 12-13x (implying the structural-headwind narrative persists), the IRR is approximately 5%. The margin recovery narrative is the transmission mechanism for a multiple re-rating: at 34% adj. op margin, the market refuses to pay more than 13-14x. At 37-38%, the market will pay 16-20x.
Bull/Bear -- Key Variable
The single most important variable: Whether adjusted operating margin recovers from the current 34% trough back toward 36-38% in FY2027-2028.
This variable is the swing factor for three reasons: (1) it directly controls FY2027-28 adj. EPS, which is the numerator for the multiple; (2) margin recovery is the mechanism that forces multiple re-rating from 12-13x to 16-20x, multiplying the impact; and (3) the “margin recovery” narrative is the frame the market will use to shift sentiment from cautious to constructive. Without it, FDS is a “show me” story at 12-13x. With it, the stock is cheap at 13x on the way to 16-18x.
Bull path: The 10% tech headcount reduction, AI-assisted coding productivity, and data ops automation translate into 150-200bps of adj. margin improvement per year in FY2027-28. FY2027 adj. op margin reaches 36.0% and FY2028 reaches 37.5-38.0%. Combined with 10%+ adj. EPS growth from revenue acceleration and share count decline, FY2028 adj. EPS reaches $23-25. At 18x (modest re-rating), the stock reaches $414-450 -- an IRR of approximately 19-22% from today.
Bear path: The productivity investments take longer than expected. Ongoing AI model investment (token costs, new agent development) offsets engineering headcount savings. FX hedging continues to create timing distortions. Management keeps spending aggressively each time ASV grows (pay-for-performance becomes structurally embedded). Adj. op margin stays at 33-35% through FY2028. FY2028 adj. EPS reaches only $19-20 (near-flat real growth), and the multiple remains at 12-14x given no re-rating catalyst. Stock trades at $228-280 in 3 years -- a return of approximately -3% to +4% annualized from today, or effectively a value trap.
Why it is hard to call: The margin trajectory is genuinely uncertain because: (a) management has elected to pay-for-performance as ASV accelerates, which means high-ASV quarters automatically trigger higher compensation expense, creating a structural ceiling on near-term margin expansion; (b) token costs for AI products are growing exponentially (13x API volume QoQ) and the offset from the Google partnership is not yet quantified; (c) the ~$500M of professional services and infrastructure investments management references are targeted at “delivering operating leverage” but the timeline is 2-3 years, making near-term evidence sparse. The leading indicators to watch: Q4 FY2026 adj. op margin (should jump if comp accruals normalize from the Q3 performance-incentive build) and the H1 FY2027 cost trajectory after the full benefit of the tech workforce reduction flows through.
If there is a close second variable, it is the durability of the “deal maker” ASV growth (banks + PE + corporates at +9% organic). This segment is the most cyclically sensitive. If capital markets activity slows in FY2027, deal-maker ASV could revert toward 4-5% and drag the overall ASV growth rate back below 6%.
What Matters Next
Near-term (weeks):
Q3 FY2026 10-Q (filed after-market July 1, 2026): Read the risk factors section for any disclosure change vs. Q2, verify the balance sheet details on the $499M current debt maturity and debt covenant status, check segment data for any changes in user count or revenue concentration metrics.
Google Cloud partnership economics: Watch for any supplemental press release or 8-K disclosure on commercial terms, particularly the token pricing structure.
Rating agency watch: Fitch confirmed investment grade; watch for S&P Global Ratings / Moody’s actions as debt matures.
Next print (Q4 FY2026, expected late September 2026):
Q4 adj. operating margin: Management’s guidance implies approximately 36-37% for Q4 to reach guidance midpoint. If it comes in at 34-35% again, the full-year margin guidance misses, and the market will question whether margin recovery is happening at all.
Q4 ASV bookings: This is described as the largest quarter of the year (”our largest quarter ever” last year). Momentum has “continued into Q4” per management’s comment that “at the end of June, early July, we are ahead of last year in terms of bookings.” A Q4 ASV growth print above 7.5% would confirm acceleration is broadening.
CFO communication cadence: Warren’s first solo analyst interactions (non-earnings) will reveal his communication style and whether he signals M&A.
Longer-term (6-18 months):
Investor Day: Management referenced an upcoming Investor Day to share “strategy and medium-term business plan.” This is expected to include FY2027-2028 adj. margin targets. If they commit to 36-38% by FY2028, the multiple re-rating trade activates.
FY2027 margin trajectory: The critical question. Monitor: (a) quarterly comp expense per FTE (should decline as performance accruals normalize if ASV growth moderates slightly); (b) token cost per MCP API call (structural efficiency from Google deal); (c) data operations headcount (target of 5% reduction in fundamentals team is one data point; what are the other data operations efficiency targets?).
MSCI and SPGI relative performance: Both growing faster (14% and 10%+ revenue growth vs. FDS at 7%). If peers re-rate upward on AI tailwind narratives while FDS’s margin story remains “show me,” the relative multiple gap may widen before it narrows.
Threshold: A reversion in organic ASV growth below 6.5% for two consecutive quarters, or adj. operating margin remaining below 35% through Q2 FY2027, would be disconfirming evidence requiring a thesis re-evaluation.
Elliot, thanks for sharing your analysis on FactSet Research Systems Inc. (FDS US).
(1) Short interest very high at ~15%. It seems like the bears are betting on generative AI lower the barriers to entry for public financial data.
What do you think of this terminal risk?
(2) Around Mar 2026, I heard rumours that FactSet is a PE target.
What do you think of the likelihood of PE takeover?
Thanks!
Great write-up, and the Q3 results bolster the thesis. I researched FactSet in November, and I landed in a similar place: the discount to MSCI and S&P Global was hard to justify for a 95%-retention franchise, with margin recovery as the variable that decides whether its re-rates. My timing was early and the stock sharply derated after I published, so it's good to see the ASV acceleration and AI monetization showing up in the numbers now.
One thing I'd add: Viswanathan's comp is built around a performance option that only vests if the stock reaches 150% of its VWAP within five years, weighted heavily toward margin discipline. That lines up with the margin-recovery-into-re-rating path you're laying out. He is paid to deliver the specific outcome the bull case needs, which is why I lean toward reading this quarter's pay-for-performance comp build as a moderate timing effect that eases as ASV growth normalizes.
That said, it's also where I get stuck, and I'd love your read. The Wells Fargo question on whether Q3 pulled comp forward points at the counterargument you flagged: performance comp scales with ASV outperformance, so a strong Q4 bookings number is exactly what the re-acceleration thesis wants, and it also feeds the comp line that keeps margins down. How do you see both landing together, sustained 7-9% ASV and a climb to 36-38% margins, when the structure seems to trade one against the other?
Thank you!