

New skill alert. I’ve built a standalone skill to automate quarterly earnings summaries and KPI tracking. It's most powerful when layered onto names where an existing workflow has already run and it has a lot more context to work with from those outputs, but it also handles cold names impressively well using just the latest 8K and transcript. Attached is the output for a cold run on a name I haven’t run the full workflow on (BLK).
BlackRock, Inc. (BLK) — Q1 2026 Quarterly Results Deep Dive
Memo Date:**Memo Date:** April 14, 2026
Quarter:**Quarter:** Q1 2026 (reported April 14, 2026, 7:30 AM ET call)
Current Price:**Current Price:** $1,057.44 (verified via yfinance, April 14, 2026)
Framework:**Framework:** Asset Manager / Alternative Manager Hybrid
Executive Summary
BlackRock delivered a clean, broad-based Q1 2026 beat that the market immediately rewarded. EPS of $12.53 vs. $11.50 consensus (+9%) and 8% organic base fee growth — the seventh consecutive quarter at or above 5% — came against a backdrop of the worst March for broad markets since September 2022. That context matters: the business grew fee revenue through a material equity market drawdown, which is precisely what the bull thesis says should happen with BlackRock’s diversified, all-weather platform. The stock gapped up 2.6% at the open and closed +3.3%, validating the reaction.
The one number worth stress-testing is organic base fee growth stepping down from Q4’s 12% to Q1’s 8%. Management framed this correctly — March was brutal for equities, spot AUM finished lower than the average AUM that drives fees, and the deceleration from 12% to 8% is math, not share loss. The 8% print is well above the 5% target and the LTM rate of 10% provides the better comparison. The DOL proposed rule on private assets in 401(k) is the quarter’s biggest structural catalyst and received less attention than it deserves.
Verdict: Strong beat with high-quality drivers. Stock reaction was right. The structural narrative accelerated.**Verdict: Strong beat with high-quality drivers. Stock reaction was right. The structural narrative accelerated.**
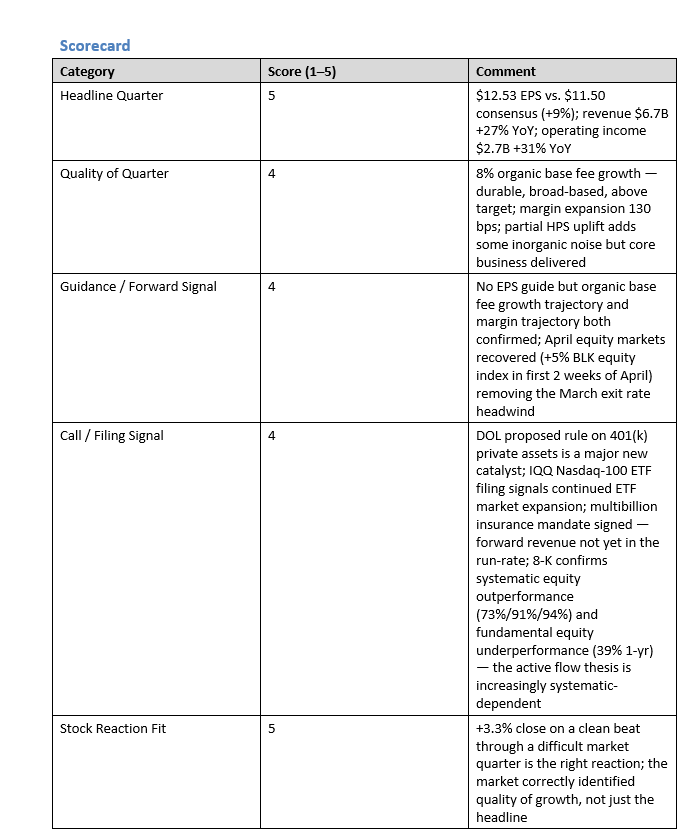
Overall: 4.4 / 5 — One of the cleaner beats of the reporting season. Quality of growth matched the quantity.**Overall: 4.4 / 5 — One of the cleaner beats of the reporting season. Quality of growth matched the quantity.**
1. Setup Into the Print
The bar was high but well-defined.**The bar was high but well-defined.** Q4 2025 was the strongest quarter in BlackRock’s history by net inflows ($342B) and organic base fee growth printed at 12%. Full year 2025 saw ~$700B in net inflows. Management entered 2026 describing the platform as having a “base fees run rate 35% higher than 2024” and increased the 2026 buyback plan to $1.8B (~$450M/quarter). The dividend was raised 10%.
What investors were specifically watching entering Q1 2026:**What investors were specifically watching entering Q1 2026:**
· Organic base fee growth sustainability after two consecutive double-digit quarters (10% Q3, 12% Q4 2025). Would 8% feel like a deceleration or a normalization?
· HPS integration and contribution — Q1 2026 was only the third quarter with HPS in the results (closed July 1, 2025) and the first full quarter of both HPS and Preqin together
· Private credit headline risk — BDC redemption concerns were active in the market; HLEND had seen Q4 2025 redemptions of 4.1%, elevated vs. prior quarters
· Fee rate trend — Q4 2025 saw a small sequential fee rate decline from securities lending specials; would underlying fee rate compress or hold?
· Operating margin tracking toward the 45%+ target ex-performance fees
The bar the company had to clear:**The bar the company had to clear:** demonstrate organic base fee growth above 6%, show fee rate stability, defend the private credit narrative, and deliver margin at or above the 45% threshold. Against a brutal March market (-7% to -10% equities, -2% to -3% bonds), doing all four was not obvious.
2. What Actually Happened
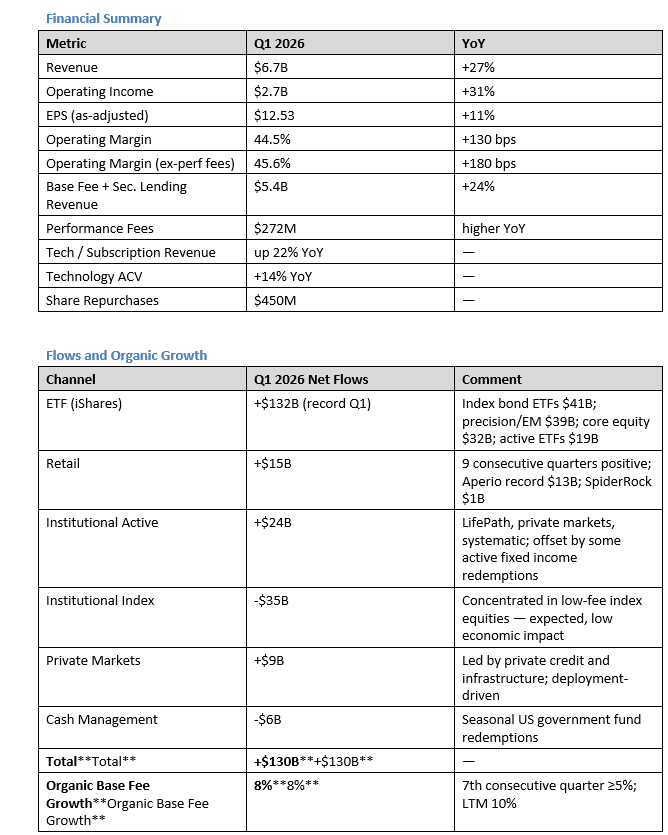
The quality of flows is high.**The quality of flows is high.** ETF flows skewed toward higher-fee international and active categories (+$19B active ETF inflows, industry-leading). Institutional index outflows of $35B are low-fee and strategically irrelevant — management has consistently guided investors to weight organic base fee growth, not gross AUM growth.
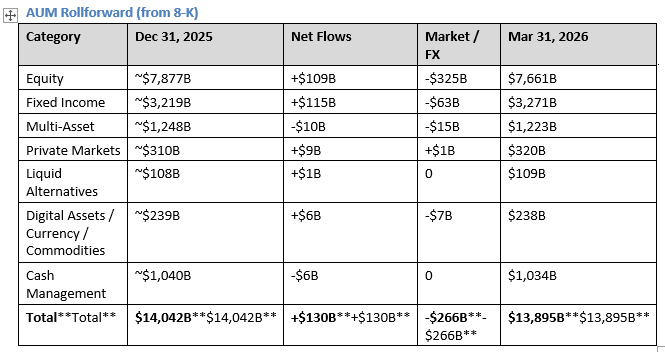
Ending AUM of $13.89T vs. $14.04T at Dec 31, 2025 — the decline is entirely market and FX (-$216B market, -$50B FX), not net outflows. Average AUM of $14.24T in Q1 was above both the beginning and ending spot AUM, reflecting the pre-March drawdown AUM level that drove the base fee calculation.
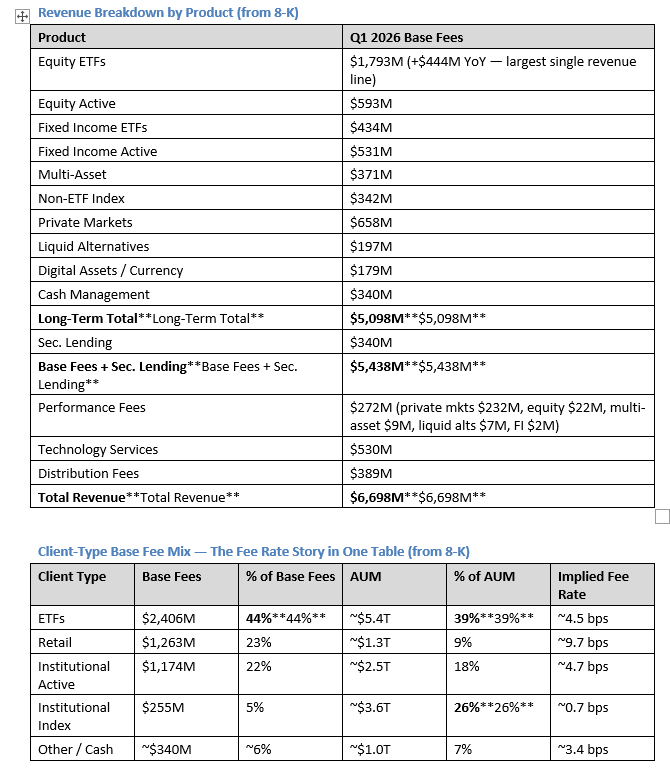
Read:**Read:**premium ETFs generate 44% of base fee revenue on only 39% of AUM — a fee rate *premium* to the overall book average. Institutional index is the reverse: 26% of AUM generating only 5% of revenue. This table is the single clearest refutation of the “AUM growth dilutes fee rate” bear case — the mix is structurally fee-rate accretive, and the new-flow mix running at 6-7x the 2023 fee yield is showing up in reported numbers.
Revenue Composition
Base fees of $5.44B ($5,098M long-term + $340M cash management) included ~$230M from HPS and ~$65M from Preqin. Performance fees of $272M were dominated by private markets ($232M from HPS). Fee rate was up 0.2 bps sequentially — confirmed by the product mix table above — driven by ETF fee rate premium, international equity outperformance, and the structural shift toward higher-fee categories (systematic equities, private markets, Aperio, active ETFs). This is the first sequential fee rate increase in recent quarters.
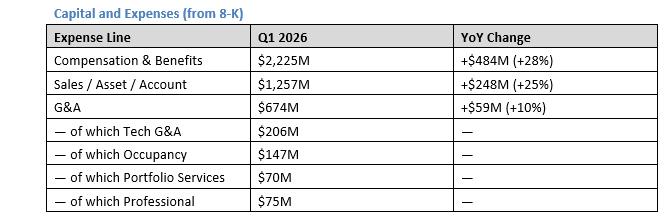
G&A ex-acquisitions grew mid-single digits; the $59M increase is predominantly HPS/Preqin integration costs. Share repurchases of $450M in Q1 with guidance for ≥$450M/quarter for the rest of 2026. Tax rate 23% in Q1 (includes $57M SBC-related discrete benefit); guided to 25% for remainder of 2026 — the discrete benefit inflated Q1 EPS by roughly $0.40.
3. What Was New This Quarter
1. DOL proposed rule on private assets in 401(k) — the biggest structural development of the quarter.**1. DOL proposed rule on private assets in 401(k) — the biggest structural development of the quarter.**
The Department of Labor released a notice of proposed rulemaking that establishes a process-based framework for plan sponsors to include private assets in target date funds. Martin Small described it as “better than we expected” and said BlackRock will launch a LifePath with privates product with Great Gray in 2026 to build a track record before the rule takes effect in the back half of the year. This is not in any model yet. The $14 trillion 401(k) market routing even 5% of new flows into private market TDFs would be a structural step-change. BlackRock — with a $600B LifePath franchise, top five alternatives platform, and Preqin for benchmarking — is uniquely positioned.
2. IQQ registration filed — Nasdaq-100 ETF for US investors.**2. IQQ registration filed — Nasdaq-100 ETF for US investors.**
BlackRock filed for IQQ, a Nasdaq-100 index ETF targeting the US market. Due to regulatory constraints, management offered limited detail, but the read-through is clear: BlackRock is moving to compete directly with QQQ (Invesco) and QQQM in one of the highest-AUM ETF categories. BlackRock already manages $25B in Nasdaq-100 ETFs outside the US. This is a fee rate-positive product and, if successful, would give BlackRock a competing offer in a large category where it has been absent.
3. Multibillion-dollar insurance mandate signed — future revenue not yet in the run-rate.**3. Multibillion-dollar insurance mandate signed — future revenue not yet in the run-rate.**
Fink disclosed a multibillion-dollar rotation from an existing insurance client into high-grade private credit. The mandate will generate revenue as capital is deployed over future quarters. A second multibillion-dollar insurance pipeline was described as “notified” for a similar mandate. These are not captured in Q1 base fees — they represent forward revenue visibility that the market is not modeling explicitly.
4. Fee rate moved UP sequentially for the first time in several quarters.**4. Fee rate moved UP sequentially for the first time in several quarters.**
The 0.2 bps sequential improvement in fee rate is a meaningful shift. Client rotation into international markets and higher-fee product categories (EM iShares, systematic equities, active ETFs, Aperio, private markets) improved mix. Management’s structural argument — that the mix of new flows is running at 6-7x the fee rate of 2023 flows — is beginning to show up in the reported fee rate. If this trend holds, it eliminates a long-standing bear case (AUM growth through low-fee index diluting the fee rate).
5. April market recovery removes the exit-rate headwind from March.**5. April market recovery removes the exit-rate headwind from March.**
Small disclosed that the BLK equity-weighted index was up ~5% in the first two weeks of April, essentially recovering the March drawdown. The base fee entry rate at end of March was ~2% below the Q1 average — that gap has been recovered. This was a forward signal that Q2 base fees start from a stronger AUM base than the March 31 spot level implied.
6. Private credit narrative defended with specific data — not just deflection.**6. Private credit narrative defended with specific data — not just deflection.**
Rather than generic reassurance, Small cited HLEND’s 10.4% annualized returns since inception, described it as “one of the only funds among major peers with positive performance in 2026,” and pointed out that the HPS portfolio’s weighted average EBITDA is ~$250M (upper-end direct lending, not stressed small-cap). This is substantive differentiation that is relevant to the bear case on private credit quality.
4. Why the Stock Moved
BLK opened April 14 at $1,050 vs. the prior close of $1,023.65 — up +2.6% at the open. It closed at $1,057.21 (+3.3%). The reaction was sustained, not faded.**BLK opened April 14 at $1,050 vs. the prior close of $1,023.65 — up +2.6% at the open. It closed at $1,057.21 (+3.3%). The reaction was sustained, not faded.**
The call was at 7:30 AM, so the gap open directly reflects the pre-market read of the print. The sustained close near the high of the day suggests no meaningful intraday reversal from the initial reaction.
What drove the rally:**What drove the rally:**
1. The beat was clean.**The beat was clean.** $12.53 vs. $11.50 consensus (+9%) with no obvious quality issues that would be reversed — the main noise is the $57M discrete tax benefit, which inflated Q1 by roughly $0.40 EPS; normalizing for that still leaves a solid beat.
2. Organic base fee growth at 8% beat the implicit buy-side fear.**Organic base fee growth at 8% beat the implicit buy-side fear.** Given March’s brutal market (-7% to -10% equities), investors entered the print worried that organic base fee growth could print at 5-6% or below. 8% above a difficult market is a quality result. The framing — 7th consecutive quarter at or above 5%, LTM 10% — reinforced durability.
3. The fee rate turned positive sequentially.**The fee rate turned positive sequentially.** For a stock whose multiple is partially supported by a “fee rate holds or improves” narrative, a +0.2 bps sequential improvement is a direct multiple-support data point.
4. April recovery news removed the exit-rate overhang.**April recovery news removed the exit-rate overhang.** The disclosure that the BLK equity index recovered ~5% in the first two weeks of April, erasing the March exit-rate headwind, effectively told investors that Q2 is starting from a stronger base than March 31 implied.
5. DOL news was incremental positive not in prior estimates.**DOL news was incremental positive not in prior estimates.** The proposed rule on 401(k) private assets is a legitimate multi-year option that the market is not fully pricing — Fink treated it as a new growth vector, not a reiteration.
Was the reaction sized correctly?**Was the reaction sized correctly?** +3.3% on a 9% EPS beat through the worst market month since September 2022 is a measured, reasonable reaction. It is not an overreaction. If anything, the DOL catalyst and the multibillion-dollar insurance mandate pipeline were not fully digested on the day. The stock may have further room if those catalysts convert in H2 2026.
5. What the Market May Be Missing
The DOL proposed 401(k) rule is being treated as a long-dated option. It may be closer than the market implies.**The DOL proposed 401(k) rule is being treated as a long-dated option. It may be closer than the market implies.**
The proposed rulemaking framework was described by management as “better than expected” and establishes a specific six-factor ERISA-based process for plan sponsors (performance, fees, liquidity, valuation, benchmarking, complexity). This is not a conceptual framework — it is a specific procedural pathway. If the rule is finalized in H2 2026 (as Small indicated), plan sponsors can begin including private assets in TDFs under the new framework as early as 2027. BlackRock is the only firm that simultaneously has: (a) the largest target date franchise ($600B LifePath), (b) a top-five alternatives platform with GIP, HPS, and private credit, (c) Preqin for benchmarking and data, and (d) an established DCIO relationship base. The addressable opportunity — even assuming 5% of 401(k) flows go into privates-inclusive TDFs — is orders of magnitude larger than any individual product launch. This is not in the consensus model.
The fee rate inflection is underweighted because it happened in a bad market quarter.**The fee rate inflection is underweighted because it happened in a bad market quarter.**
A fee rate improvement in a quarter when international equities outperformed US equities can be dismissed as cyclical. But the underlying mix shift — $19B in active ETF inflows (industry-leading), record Aperio flows, private markets inflows, systematic equities demand — is structural. These are higher-fee categories growing faster than the firm’s overall AUM base. Small stated that the fee yield on new flows is running 6-7x the 2023 level. If that cadence continues, the overall fee rate continues to ratchet up regardless of market beta. The market is not modeling fee rate expansion; it is modeling stability.
Insurance private credit mandates are multibillion-dollar pipeline items that convert to recurring fees on deployment — and management gave specific, quantified detail.**Insurance private credit mandates are multibillion-dollar pipeline items that convert to recurring fees on deployment — and management gave specific, quantified detail.**
Fink cited: (a) one mandate already signed and beginning deployment, (b) a second “notified” multibillion pipeline for a similar mandate, and (c) 20+ late-stage conversations to migrate ~10% of existing general account assets from public fixed income to private high-grade (a $700B base × 10% = ~$70B potential). These are not soft comments — they are operationalized pipeline items. At HPS fee rates (~50-60 bps), even $10-15B of additional AUM conversion represents $50-90M in incremental annual base fees that are not in the run-rate.
The institutional active flow thesis rests almost entirely on systematic equity — and the 8-K confirms it.**The institutional active flow thesis rests almost entirely on systematic equity — and the 8-K confirms it.**
8-K investment performance data shows systematic equity at 73% above benchmark 1-year, 91% 3-year, 94% 5-year — genuinely strong multi-period alpha. Fundamental equity is at 39% 1-year, 51% 3-year, 42% 5-year — mediocre and not an argument for institutional active allocation. The $24B in institutional active net inflows is going to systematic equity, not to fundamental stock-picking. This concentration is not visible from the transcript, which aggregates active inflows. The implication: if systematic strategies hit a regime where factor momentum or quant approaches underperform (mean-reversion, value cycle, low-correlation regime), the active inflow engine stalls. The market is pricing diversified active capability; the data shows concentrated systematic delivery.
6. Call / Filing Nuggets That Matter
From the transcript:**From the transcript:**
· Small on the March market context: “March 2026 was the worst month for broad markets since September 22. In September 22, broad stocks were down 10%. Broad bonds were down 4% to 5%. In March 26, stocks were down 7% to 10%. Brought bonds traded down 2% to 3%.”*”March 2026 was the worst month for broad markets since September 22. In September 22, broad stocks were down 10%. Broad bonds were down 4% to 5%. In March 26, stocks were down 7% to 10%. Brought bonds traded down 2% to 3%.”* — This is the most important contextual anchor for interpreting the 8% organic base fee growth. Delivering 8% through that environment is not a deceleration story; it is a durability validation.
· Small on the April recovery: “At the end of March, our base fee entry rate was approximately 2% lower than the first quarter base fees. But that’s basically been recovered with the April market performance.”*”At the end of March, our base fee entry rate was approximately 2% lower than the first quarter base fees. But that’s basically been recovered with the April market performance.”* — This is the most actionable forward signal on the call. Q2 base fees start from a recovered AUM base, not the March trough.
· Small on private credit (HPS): “HLEND is one of the best performing non-traded BDCs in the market. It’s logged 10.4% annualized total returns since inception. It’s one of the only funds among major peers with positive performance in 2026.”*”HLEND is one of the best performing non-traded BDCs in the market. It’s logged 10.4% annualized total returns since inception. It’s one of the only funds among major peers with positive performance in 2026.”* — Concrete performance data rather than management reassurance. In a quarter where BDC concerns dominated asset manager sentiment, outperformance data is high-signal.
· Small on insurance pipeline: “This quarter, we signed a multibillion dollar rotation into high-grade private credit from an existing insurance client. This will drive revenue growth as is deployed over future quarters. We have a multi-billion notified insurance pipeline for a similar mandate.”*”This quarter, we signed a multibillion dollar rotation into high-grade private credit from an existing insurance client. This will drive revenue growth as is deployed over future quarters. We have a multi-billion notified insurance pipeline for a similar mandate.”* — This is explicit forward revenue not in any model. The deployment cadence across future quarters makes this a multi-quarter earnings tailwind.
· Small on margin path: “We’ve run the company at 47%. So I don’t see 45% or 46% as a ceiling.”*”We’ve run the company at 47%. So I don’t see 45% or 46% as a ceiling.”* — The 45% floor language has been consistent; the explicit reference to 47% as a prior high (in 2021, before GIP/HPS) combined with the claim that both acquired businesses had 50%+ FRE margins is a direct signal that structural margin is above the 45% floor target, not at it.
· Fink on IQQ (Nasdaq-100 ETF): Not able to disclose details due to regulatory constraints, but confirmed the filing and described BlackRock as “already the largest manager of Nasdaq-100 ETFs outside the United States.” — Signals intent to compete in a very large market, fee-rate accretive vs. core equity ETF mix.
From the 8-K filing (Q1 2026 Reg FD financial statements):**From the 8-K filing (Q1 2026 Reg FD financial statements):**
Investment performance as of March 31, 2026 — this is the data point that explains why institutional demand for BLK active strategies held up despite a difficult market:
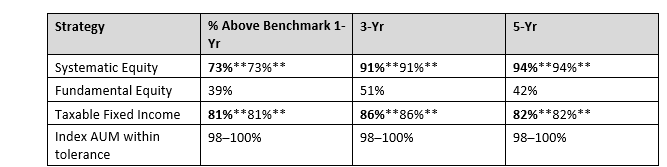
Read:**Read:** Systematic equity is a standout — 73% beating over 1-year, 91% over 3-year, 94% over 5-year. This explains the $24B institutional active net inflows directionally — flows are going to the high-performing systematic book, not to fundamental equity (39% 1-year beat rate is weak). Fixed income is also strong across periods. The divergence between systematic and fundamental equity is not acknowledged explicitly in the transcript but matters for the quality and sustainability of active inflow thesis.
The fundamental equity underperformance (39% 1-yr above benchmark) is a yellow flag: active equity demand at BLK may be increasingly systematic-dependent. If systematic alpha compresses in a regime change — e.g., a mean-reversion or value-outperformance environment — the institutional active flow tailwind could moderate materially. This is the clearest bear-case data point in the 8-K and is not visible from the transcript alone.
7. Second-Order Implications
For the margin trajectory:**For the margin trajectory:**
Q1 margin of 44.5% (45.6% ex-performance fees, +180 bps YoY) was achieved in a quarter where AUM finished lower on a spot basis than the average (due to March). This means the revenue that supported the margin was slightly suppressed relative to the AUM trajectory entering Q2. If April’s market recovery holds and Q2 begins from a higher AUM base, the operating leverage embedded in the model should produce further margin expansion in Q2. The headcount-flat guidance for 2026 and mid-single-digit G&A growth (after fully annualizing HPS/Preqin) caps expense growth below the revenue growth rate — margin expansion is mathematically likely in Q2 and Q3 if markets cooperate.
For the fee rate:**For the fee rate:**
The 0.2 bps sequential fee rate increase is small in absolute terms but directionally significant. Client rotation into international markets and higher-fee products was the driver. If tariff/geopolitical uncertainty continues to push US investors toward international diversification (a reasonable scenario given the macro environment described on the call), international iShares demand persists, and the structural growers (systematic equities, private markets, Aperio, active ETFs) continue to take disproportionate share, the fee rate continues to ratchet up. This is a multi-quarter tailwind the market is not pricing.
For the private credit competitive dynamics:**For the private credit competitive dynamics:**
The bifurcation Small described — institutional demand for private credit strengthening while retail BDC flows moderate — is the right structural read. The bear case for BDCs has been retail redemption risk (lock-up friction, NAV volatility perception). The institutional market doesn’t face that dynamic. If BDC redemption concerns continue to slow retail flows into competitors’ structures while BlackRock captures more institutional allocation (where HPS’s 85%+ institutional mix is a durable advantage), BlackRock may actually gain private credit share in the environment that is supposed to hurt it. This is the second-order consequence of private credit market turbulence that the market is pricing as uniformly negative for BLK.
For the ETF competitive landscape:**For the ETF competitive landscape:**
Record Q1 ETF flows of $132B in a volatile market quarter demonstrates that BLK’s ETF franchise is counter-cyclical, not pro-cyclical. When clients rotate (from US to international, from equities to bonds, from passive to active), iShares is structurally positioned because it covers “virtually every slice of global equities and bond markets.” The IQQ filing adds a high-AUM category that BLK has been absent from. If successful, it adds both AUM and fee revenue in one of the most widely-tracked indexes. The pie-vs.-cannibalization question from Brennan Hawken (BMO) was not definitively answered, but the S&P 500 experience (multiple competing products coexisting at scale) is the more likely analog.
For Preqin as a long-term platform:**For Preqin as a long-term platform:**
Small outlined four phases for Preqin: distribution, data/model buildout, data factory scaling, and private market indexation. The fourth — building investable private market indices that ultimately power iShares equivalents for private markets — is the largest and furthest out. But the DOL rule accelerates the timeline because plan sponsors need benchmarking data for fiduciary compliance. Preqin’s data becomes a regulatory necessity, not just an analytics option. This transforms Preqin’s addressable market from buy-side discretionary analytics spend to a compliance-critical institutional data feed.
8. What Matters Next
The 3 things that will define Q2:**The 3 things that will define Q2:**
1. Organic base fee growth vs. the 8% Q1 print.**Organic base fee growth vs. the 8% Q1 print.** The 8% in Q1 was against the worst March since September 2022. Q2 starts with a recovered AUM base (April +5% BLK equity index). If organic base fee growth prints at 8%+ in Q2, the deceleration-from-12% narrative is definitively put to rest. If it falls below 7%, the market will ask whether Q4 2025’s 12% was the outlier and 6-7% is the new regime. The difference matters for multiple.
2. Insurance mandate deployment commencement.**Insurance mandate deployment commencement.** Fink cited specific multibillion-dollar mandates signed and notified. Q2 is when the first of these should begin deployment and show up in private markets base fees. If management mentions “initial deployment activity” from these mandates in the Q2 call, it validates the pipeline is real and accretive to the run-rate. No update would be a yellow flag.
3. DOL rulemaking progress.**DOL rulemaking progress.** Management guided the rule to take hold in the back half of 2026. If the DOL finalizes the proposed rule and plan sponsors begin evaluating LifePath-with-privates products, this triggers a multi-year earnings ramp that would require material model revisions. Any regulatory acceleration or deceleration in the comment period is significant.
Secondary watch items:**Secondary watch items:**
· Fee rate in Q2 — does the sequential improvement hold, or was it a one-quarter rotation effect?
· HLEND subscriptions vs. redemptions in Q2 — April window showed $150M in subscriptions; continuation or deceleration tells the institutional-vs.-retail dynamic story
· IQQ ETF launch timeline — if BlackRock clears the registration period and launches in Q2 or Q3, fee rate impact and initial flows matter
· Margin path — does the 45.6% ex-performance-fee margin expand further in Q2 with higher AUM base?
· GIP V deployment pace — already “majority committed” through TCR, AES, Aligned; Q2 deployment update matters for carry potential
· Aladdin ACV trajectory — +14% YoY in Q1; management targeting low-to-mid-teens long-term; any acceleration from the DOL/401(k) data requirement narrative would be material
9. Bottom-Line Analyst View
Thesis status: Intact and strengthening.**Thesis status: Intact and strengthening.**
Q1 2026 validated three elements of the BLK bull case simultaneously: (1) organic base fee growth is durable above the 5% target through bad market environments, not just tailwind quarters; (2) the fee rate can improve as the mix of new flows is structurally richer than the legacy base; and (3) the platform architecture (public markets + private markets + technology) creates multiple independent growth engines that do not all require the same macro environment to perform.
The DOL catalyst is the highest-conviction incremental development in the quarter and is not being priced with appropriate urgency. BlackRock is the only asset manager that can credibly offer a plan sponsor a complete solution: target date history, private market scale (GIP, HPS), data and benchmarking (Preqin), and technology (Aladdin). The 401(k) market is $14 trillion. Even a modest penetration of private assets into target date vehicles creates a recurring fee stream that compounds over decades as new contributions enter. This is not a 2026 earnings story — it is a 2027-2030 earnings story — but it justifies a premium multiple today.
The bear case is not thesis-breaking but is worth monitoring: (1) if the DOL rule is delayed or weakened, the option expires; (2) if private credit retail BDC redemptions accelerate, HLEND flows slow and the private markets narrative needs to be sustained entirely by institutional demand; (3) if international market outperformance reverses and US equities re-assert, the fee rate tailwind reverses and mix reverts to lower-fee US index flows. None of these is the base case, but all are visible from the Q1 data.
At $1,057/share, BLK is not cheap on near-term earnings, but the 2027-2030 platform optionality — DOL/401(k), insurance mandates, private market indexation via Preqin — represents incremental value that a standard earnings multiple does not capture.**At $1,057/share, BLK is not cheap on near-term earnings, but the 2027-2030 platform optionality — DOL/401(k), insurance mandates, private market indexation via Preqin — represents incremental value that a standard earnings multiple does not capture.** The stock deserves a premium to asset manager peers, and Q1 reinforced why.
Quick Take (TL;DR)
BLK Q1 2026: $12.53 EPS vs. $11.50 consensus (+9%), 8% organic base fee growth through the worst market month since Sep 2022, fee rate up sequentially for the first time in recent quarters. Stock rallied +3.3% on the day — the right call. The DOL proposed rule on 401(k) private assets is the quarter’s most underappreciated development. The insurance mandate pipeline (multibillion-dollar, signed and notified) is forward revenue not in the model. Watch: Q2 organic base fee growth vs. the 8% bar, first deployment revenue from the insurance mandates, and DOL rulemaking progress in the back half of 2026.
Sources: BLK Q1 2026 Earnings Call Transcript (April 14, 2026); BLK Q4 2025 Earnings Call Transcript (January 15, 2026) for setup context; yfinance earnings history (consensus EPS $11.496, actual $12.53, verified); yfinance price data (prior close $1,023.65, April 14 open $1,050.00, close $1,057.21); current price $1,057.44 (verified April 14, 2026); BLK Q1 2026 8-K (Reg FD financial statements, April 14, 2026, 4MB XBRL Inline HTML — parsed via Python regex tag-stripping to extract AUM rollforward, revenue by product, client-type base fee mix, investment performance, and expense detail).*Sources: BLK Q1 2026 Earnings Call Transcript (April 14, 2026); BLK Q4 2025 Earnings Call Transcript (January 15, 2026) for setup context; yfinance earnings history (consensus EPS $11.496, actual $12.53, verified); yfinance price data (prior close $1,023.65, April 14 open $1,050.00, close $1,057.21); current price $1,057.44 (verified April 14, 2026); BLK Q1 2026 8-K (Reg FD financial statements, April 14, 2026, XBRL Inline HTML — parsed via Python regex tag-stripping to extract AUM rollforward, revenue by product, client-type base fee mix, investment performance, and expense detail).*
Thanks for sharing your progress on this stuff. Would you be willing to share details on how you're getting the SEC docs? Currently I'm using this: https://sec-edgar-mcp.amorelli.tech/introduction
And, I'm using "standard" output from Value Line and Morningstar to help fill out my rubric. But, interested in what's emerged in the last six months as an alternative.