

Following up on the FND AI workflow note, I’ve made several adjustments and added new skills to the equity research process. The output has improved marginally and is now comparable to, if not better than, the majority of sell-side notes I’ve read historically. There are still a few areas I’m refining to further improve quality and this is obviously no panacea for investment returns as one still needs to judge the future of a business and its appropriate multiple, however, it certainly enhances the initial ramp period on a new company or industry allowing an individual investor to turn over more rocks and decide more quickly if an opportunity is worth pursuing.
I’ve pasted in the text a few examples of the AXON output below, but here is the full list of outputs that come with a complete run:
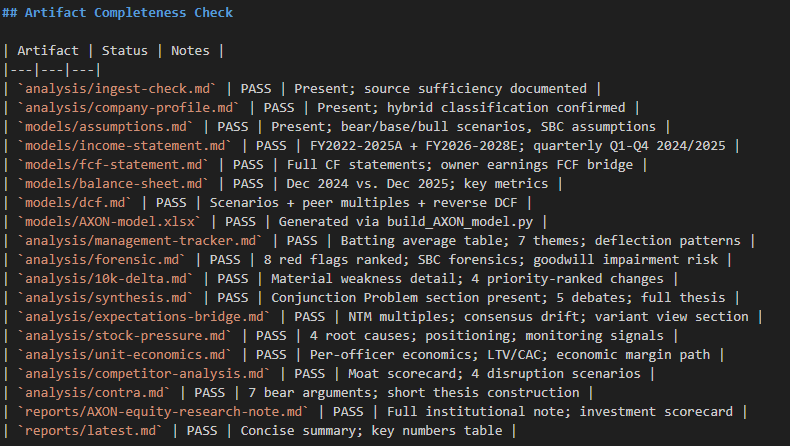
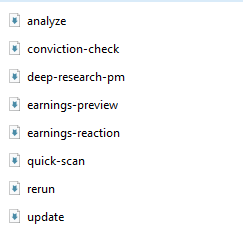
Here is a list of the skills I have the agent run through in a specified order:
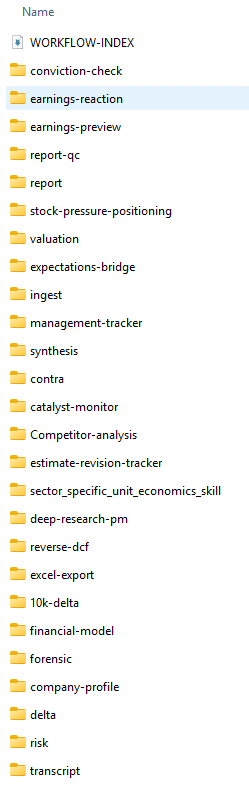
And you can create custom commands as you add more data so you don’t have to run the entire workflow and can gear it towards a specific purpose:
Consolidated Research Note Output:
# AXON Enterprise, Inc. (NASDAQ: AXON)
## Full Equity Research Note
**Date: April 9, 2026 | Rating: Monitor | Price: $393 | Price Target: $450 (base) / $220 (bear) / $620 (bull)**
**Market Cap: ~$31.5B | EV: ~$31.6B | FY2025 Revenue: $2.78B | FY2025 Adj EBITDA: $706M**
---
## Investment Scorecard
| Question | Answer | Confidence |
|----------|--------|------------|
| Is the core business growing at/above thesis? | Yes — revenue +33.5%, bookings +46% in FY2025 | High |
| Is FCF quality improving (SBC-adjusted)? | No — owner earnings FCF -$276M in FY2025 | High |
| Is management guidance credible? | Mixed — revenue 100% hit rate; FCF 50% hit rate | Medium |
| Is the stock debate primarily fundamental or sentiment? | Both — fundamental (FCF quality) + sentiment (AI premium) | High |
| Does the valuation imply a scenario we disagree with? | No (fairly priced to base; bull priced in at $393) | Medium |
| Is the thesis intact since last update? | Conditionally — bookings intact; FCF/SBC concern widening | Medium |
**Rating: Monitor** | **Base Price Target: $450** (+14%) | **Bear: $220** (-44%) | **Bull: $620** (+58%)
**Conviction: Medium** | **Risk/Reward: Approximately symmetric at current price**
---
## Executive Summary
Axon Enterprise has built the most defensible infrastructure stack in public safety — an integrated hardware-software-data platform that serves as the operational backbone for law enforcement globally. The FY2025 results were operationally excellent: $2.78B of revenue (+33.5%), $7.4B of bookings (+46%), ARR exceeding $1.3B (+35%), and NRR recovering to 125%. The business is structurally superior to the market’s periodic willingness to pay for it.
The investment problem is not the business — it is the price. At $393 (35x NTM adj EBITDA, ~44x FY2025A adj EBITDA), the stock requires:
1. Bookings growth sustained at 25%+ through FY2028 → $6B revenue
2. SBC declining from 23% to 12% of revenue → owner earnings FCF inflecting to $730M by FY2028
3. AI Era Plan penetrating from 30% to 70% of eligible customers → ARPU expanding from $600 to $900-1,200/officer
4. No goodwill impairment on $1.37B of acquired businesses (Dedrone, Fusus, Prepared; Carbyne closes Feb 2026)
5. Revenue recognition material weakness remediated without additional revisions to ARR/NRR metrics
All five must hold simultaneously. Three are well-evidenced by current data (bookings, NRR, international diversification). Two carry genuine uncertainty (SBC normalization, material weakness). This is an approximately fairly priced risk/reward, not a screaming opportunity.
**The preferred entry range is $300-$330** (15-17x FY2028E adj EBITDA) where the risk/reward improves meaningfully. At current levels, the position is appropriate for existing holders to maintain; new positions carry thin margin of safety.
---
## Section 1: Business Overview
### What Axon Does
Axon Enterprise is an integrated public safety platform company. Its core products:
**Hardware (57% of FY2025 revenue, ~49% gross margin):**
- **TASER Conducted Energy Devices (CEDs):** TASER 10 (current generation), dominant market share (~85% US CED market). Approaching $1B annual revenue. Cartridge consumable creates recurring revenue (”fired every 30 seconds in the US”).
- **Body Cameras (AXON Body 4, Fleet cameras):** Standard equipment for law enforcement; connected to evidence.com
- **Dedrone:** Drone detection systems for airports, prisons, critical infrastructure (acquired FY2024)
- **Sky-Hero:** Tactical drone systems (acquired FY2023)
**Software / Services (43% of FY2025 revenue, ~74% gross margin):**
- **evidence.com:** Cloud-based digital evidence management. The core SaaS product; holds years of legally authenticated body camera footage, case files, and investigative data. The primary switching cost generator.
- **AI Era Plan:** Premium AI overlay including Axon Assistant (report writing, evidence summarization), real-time transcription, automated notifications. $750M of bookings in first full year.
- **Axon Records:** Records management system replacing legacy RMS (Computer-Aided Dispatch)
- **Fusus:** Real-time intelligence for command centers and dispatch (acquired FY2025)
- **Prepared:** School safety platform (acquired Q4 2025)
- **Carbyne:** AI-powered 911 call handling (closing Feb 2026)
**The flywheel:** TASER contracts (5-10 years) create physical presence → body cameras create daily data generation → evidence.com becomes the system of record → AI overlays monetize the data and workflow at premium prices → each contract renewal upsells a higher-priced plan.
### Scale and Reach
- Coverage: ~85% of US federal law enforcement agencies; deployed in 100+ countries
- Sworn officers on AXON platform: estimated 2M+ globally
- ARPU: from $250/officer (FY2022 peak) → $600/officer (FY2025 current premium)
- Future contracted bookings: $7.4B of new bookings in FY2025; substantial multi-year backlog
---
## Section 2: Investment Thesis
### The Long Case
**1. Revenue is substantially pre-determined through FY2026**
The bookings-to-revenue conversion model is AXON’s most important financial mechanic. CFO Brittany Bagley (Q4 2025): “20-25% of future contracted bookings converts to recognized revenue in the following year... you can actually roll that all the way forward to 2028 and sort of keep a consistent math philosophy.”
At $7.4B of FY2025 bookings (cumulative backlog likely $11-15B), 20-25% converts to ~$2.8-3.75B of FY2026 revenue. Management guided $3.5B; internal model: $3.45B. The revenue is contractually committed — the “growth” debate in FY2026 is about bookings growth rate (which determines FY2027 revenue), not current-year execution.
**2. NRR of 125% means existing customers fund the growth**
At 125% NRR, AXON’s existing customer base grows revenue by 25% annually without any new customer wins. This compounding effect means:
- A cohort of customers generating $1B of ARR in FY2025 generates ~$1.56B by FY2027 from the same customers
- The company’s sales force is effectively amplified — every dollar of prior bookings generates future expansion revenue without re-selling
NRR of 125% is near a 3-year high (trough was ~120% in late 2024). The AI Era Plan is the primary driver of recovery — customers upgrading from base OSP to premium plans.
**3. The hardware moat is genuinely underappreciated**
Critics argue AXON is overvalued because it’s “half a hardware company.” The correct analytical frame is the opposite: the hardware is what makes the software defensible.
Evidence.com holds years of legally discoverable body camera footage. This data cannot be migrated:
- Chain-of-custody requirements make video migration legally complex
- Prosecutors’ offices rely on the evidence.com interface for case preparation
- Reformatting and re-indexing terabytes of video requires departmental IT resources few agencies have
TASER is a practical monopoly with 5-10 year contracts and product liability barriers to entry that would take a new competitor a decade to overcome.
**4. AI Era Plan represents 2-3x ARPU potential from existing customers**
Only 30% of AXON-equipped departments have adopted the AI Era Plan. At $200-400/officer/year incremental ARPU on the AI layer (above the base $600 plan), the total addressable ARPU expansion is:
- 40% incremental penetration × 2M+ officers × $300 average incremental = ~$240M of new annual recurring revenue from upsell alone
- This is equivalent to adding a 2025-scale mid-market SaaS company from existing customers
Management framing: “Bottom of the first, top of the second.” The AI monetization runway is real and measurable.
**5. Four-market diversification reduces concentration risk**
FY2025 demonstrated simultaneous momentum in all four target markets:
- US state/local: continued TASER 10 upgrades; AI Era Plan initial wave
- International: crossed $1B bookings for the first time; two nine-figure EU cloud deals in Q4 alone
- Corrections: “Largest single customer booking in Axon company history” in FY2025
- Federal/Enterprise: “Some of our largest opportunities in front of us for 2026 could come from federal”
This diversification means no single vertical disappointment breaks the thesis.
---
## Section 3: The Bear Case
### Why You Can Lose Money Without the Business Failing
At $393, there are four distinct mechanisms by which a long position loses money without any fundamental deterioration in AXON’s core competitive position:
**Mechanism 1: SBC normalization fails (probability: 40%)**
The base case requires SBC declining from $634M (23% of revenue) to $720M (12% of revenue) by FY2028. This is $86M of absolute dollar increase on revenue that grows from $2.78B to $6.0B — requiring no reduction in dollar-value grants while more than doubling revenue.
If SBC instead stays at 20% of revenue in FY2028 (i.e., management keeps granting at the same relative rate): SBC = $1.2B (vs. $720M modeled), adj EBITDA margin = 22-23% (vs. 28-31% modeled), owner earnings FCF barely turns positive by FY2028. The base case intrinsic value drops to $250-280/share.
**Mechanism 2: FY2026 FCF recovery fails (probability: 35%)**
Management has predicted “returning toward 60% FCF conversion” after each of two FCF misses (FY2023: 42%, FY2025: 11%). If FY2026 reported FCF comes in at $250-350M instead of $540M (60% of $900M adj EBITDA guidance), market confidence in management’s cash generation narrative permanently degrades. Multiple compresses from 35x to 25x NTM adj EBITDA. Price → ~$270.
**Mechanism 3: Goodwill impairment on acquisitions (probability: 25-30%)**
$1.37B of goodwill from Dedrone, Fusus, Prepared (plus ~$400-500M from Carbyne post-close) must generate sufficient ARR to pass annual impairment tests. If any acquired business misses its target:
- A $300M goodwill write-down creates a $300M GAAP loss (non-tax-deductible)
- This turns a profitable year into a GAAP loss quarter with headlines
- Multiple compresses on combined business despite core TASER/camera performance remaining intact
**Mechanism 4: Revenue recognition material weakness persists (probability: 20-25% for meaningful impact)**
The revenue recognition weakness affects evaluation of contract terms that determine ARR and bookings recognition. If the remediation requires re-evaluation of any portion of the $7.4B bookings or >$1.3B ARR, the underlying financial metrics that drive the valuation could be revised downward. Even a 5% revision to reported ARR ($65M reduction) would reduce reported NRR trajectory materially.
---
## Section 4: Financial Analysis
### Revenue Quality
Revenue of $2.78B (+33.5% YoY) is high quality. It is driven by a contractually committed bookings base, verified by NRR metrics, and confirmed by the deferred revenue and contract asset balances on the balance sheet.
**Revenue confirmation tests:**
1. Deferred revenue + contract assets = $1.84B — substantial pre-sold pipeline
2. NRR 125% — existing customers expanding at an above-revenue-growth rate
3. Bookings $7.4B — 2.7x current annual revenue already contracted
4. Services revenue at 43.3% mix and 74.0% gross margin — clean SaaS economics
**Revenue risk items:**
- Revenue recognition material weakness still open
- Q4 2025 gross margin dip to 57.9% (hardware-heavy seasonality; watch Q1 2026 recovery)
- ARR growth decelerating from 47% → 35% (expected base effect; but must stabilize above 25%)
### Cash Flow Quality
This is AXON’s most significant analytical challenge. Three metrics tell three different stories:
| Metric | FY2025 | Interpretation |
|---|---|---|
| Adj EBITDA | $706M | Operating performance; before SBC, D&A |
| Reported FCF | $75M | After operations and CapEx; before SBC taxes |
| Owner Earnings FCF | -$276M | After net-settle SBC taxes; true economic cash |
The $631M gap between adj EBITDA and reported FCF is driven by:
1. SBC $634M (non-cash add-back): real economic cost paid in equity dilution + tax settlement
2. Working capital: -$482M from contract asset growth (structural, not manipulative)
3. CapEx: -$136M (data center + manufacturing investment)
The $351M gap between reported FCF and owner earnings FCF is the net-settle SBC tax payment — cash paid by AXON on employees’ behalf at RSU vesting. This is classified in financing activities, not operations, and is invisible in standard FCF screens.
**FY2025 owner earnings FCF was negative $276M. The business is not currently generating economic free cash flow.**
This does not mean the business is failing. It means AXON is in an investment and compensation cycle where adj EBITDA significantly overstates near-term economic returns. The bull case requires this to invert by FY2027-28.
### Balance Sheet
Liquidity is strong: $1.73B cash + investments vs. $81M current notes = ample runway.
The critical balance sheet risk is goodwill ($1.37B, +81% YoY from acquisition pace). This is 42% of total equity and represents the cumulative acquisition premium paid for strategic additions. Each acquisition must generate sufficient ARR to justify its carrying value.
Capital structure post-FY2025 refinancing: $1.75B of senior notes (2030/2032 maturity) replaced convertible notes. Interest expense ~$100M/year. Coverage: 7x adj EBITDA. Net leverage near zero. Capital structure is not a near-term concern.
---
## Section 5: Management Assessment
### Credibility Tier: Medium (67% overall batting average)
| Guidance Type | Hit Rate | Assessment |
|---|---|---|
| Revenue guidance | 100% | Consistently conservative; beats by 5-15% |
| Adj EBITDA margin | 75% | Generally credible; one slight miss in FY2023 |
| FCF conversion (60% target) | 50% | Low credibility; same “returning to 60%” language after each miss |
| SBC dilution (<3%) | 33% | Low credibility; actual dilution exceeded target in FY2024 and FY2025 |
**Individual credibility assessments:**
- **Rick Smith (CEO):** Visionary, long-term oriented, candid on risks (”privacy and data handling is #1 failure mode”). High credibility on product vision and competitive strategy; lower on financial discipline
- **Brittany Bagley (CFO/COO):** Sets conservative revenue guidance that the company consistently beats. High credibility on revenue delivery. Low credibility on FCF conversion commitments — uses identical “low point / returning to 60%” language after each miss
- **Josh Isner (President):** Most operationally specific; tracks market dynamics carefully; most useful earnings call commentary. High credibility
- **Jeffrey Kunins (CTO/CPO):** Most specific on product differentiation; rarely over-promises. High credibility
**Key management deflection patterns to watch:**
1. Bookings guidance: “We probably want to stay away from any bookings guidance” — only qualitative sentiment given
2. FCF miss attribution: Working capital timing/inventory investment framing; structural SBC drag downplayed
3. SBC dilution math: <3% claim counts only compensation grants, not equity offering dilution
4. AI Era Plan unit economics: Bagley deflects on per-seat ARPU and standalone penetration economics
---
## Section 6: Valuation
### EV/Adj EBITDA Scenario Analysis
| | Bear | Base | Bull |
|---|---|---|---|
| FY2028 Revenue | $4.8B | $6.0B | $7.0B |
| Adj EBITDA margin | 22% | 28% | 32% |
| FY2028 Adj EBITDA | $1,056M | $1,680M | $2,240M |
| EV/Adj EBITDA exit | 15x | 18x | 22x |
| Implied price per share | $173 | $343-$450 | $560-$620 |
| vs. $393 | -56% | -13% to +14% | +42% to +58% |
> Base case range reflects: $343 = strict 18x FY2028 EBITDA PV; $450 = 20x NTM EBITDA in FY2027 when business inflects. Market is currently pricing approximately 20x FY2028E adj EBITDA ($393 ≈ $31.6B EV / $1.68B base FY2028 EBITDA ≈ 18.8x).
### Owner Earnings FCF Valuation
At $393, the market is paying:
- 102x FY2027E owner earnings FCF ($245M)
- 36x FY2028E owner earnings FCF ($730M)
The 36x FY2028E owner earnings is demanding but not irrational for a 30%+ grower if FY2028 is mid-cycle, not peak. The assumption that must hold is SBC declining to 12% of $6B revenue ($720M) — flat in dollar terms from FY2025.
### Peer Comparison
AXON at 35x NTM adj EBITDA is in-line with Tyler Technologies (government software, ~35x), above Motorola Solutions (22x), and below Palantir (~60x). The premium over Motorola reflects AXON’s superior growth rate and AI monetization potential. The discount to Palantir reflects AXON’s FCF quality issues. On a pure Rule of 40 basis (~59 for AXON vs. ~50 for Palantir), AXON arguably deserves the premium to Palantir — but the market is not granting it given the FCF miss history.
### Preferred Entry: $300-$330
At $300-$330 (15-17x FY2028E adj EBITDA):
- Bear scenario requires -27% to -37% additional downside (vs. -44% from current)
- Bull scenario provides +88% to +107% upside (vs. +58% from current)
- Risk/reward skews 2:1 positive vs. negative — a meaningfully more attractive starting point
The entry range is achievable if Q1/Q2 2026 FCF disappoints, if the revenue recognition weakness creates additional negative headlines, or if the broader growth stock multiple compression continues. A patient investor can wait for this opportunity.
---
## Section 7: Key Risks
### Top 5 Risks Ranked by Expected Impact on Stock Price
**1. FCF fails to recover in FY2026 (probability 35%, impact -20-30%)**
Same outcome/language as FY2023 miss. If $250-350M vs. $540M guided recovery.
**2. Revenue recognition material weakness leads to ARR/bookings revisions (probability 20%, impact -10-20%)**
Trust discount on primary valuation metrics; auditor critical audit matter designation.
**3. Goodwill impairment on acquired businesses (probability 25-30%, impact -5-15%)**
Headline risk even if core TASER/camera economics intact. Most likely target: Carbyne or Fusus.
**4. AI Era Plan ARPU fails to expand from 30% penetration (probability 40%, impact -10-20%)**
Services mix stays at 43%, blended GM stays below 61%, margin expansion thesis delayed 2 years.
**5. Multiple compression if broader growth-to-value rotation continues (probability 30%, impact -15-25%)**
AXON is a long-duration asset; at 4.5%+ risk-free rate, any sustained risk-off environment re-prices terminal value.
---
## Section 8: Catalyst Monitor Summary
### Near-Term Catalysts (Next 1-3 Quarters)
| Catalyst | Timeline | Implication if Positive | Implication if Negative |
|---|---|---|---|
| Q1 2026 earnings (May 2026) | ~4-6 weeks | Revenue beat + FCF recovery signal → +15-20% | FCF miss again → -15-25% |
| Revenue recognition weakness remediation announcement | Mid-2026 | Trust restored; 5-10% relief rally | Ongoing → persistent discount |
| AI Era Plan penetration disclosure above 40% | Q1/Q2 2026 call | ARPU expansion thesis supported | Stall at 30% → -5-10% |
| Federal bookings: named contracts with federal agencies | FY2026 | New TAM unlocked; bookings growth surprise | Delay → guidance risk |
### Thesis-Testing Events (FY2026)
**The single most important number in Q1 2026:** Reported FCF
- If Q1 2026 reported FCF > $150M (annualizing toward the 60% target): bull thesis supported; stock likely +10-15%
- If Q1 2026 reported FCF < $75M (repeating FY2025 quarterly pace): bear thesis strengthened; stock likely -10-20%
**The second most important number:** FY2026 full-year bookings update (reported in Q4 2026 earnings, Feb 2027)
- If FY2026 bookings grow 30%+ → base case FY2028 revenue fully confirmed
- If FY2026 bookings decelerate to 15-20% → FY2028 revenue $5B not $6B → bear case
---
## Section 9: Investment Conclusion
**AXON is an excellent business at an approximately fair price.** The case for owning it is straightforward: the business is compounding at 30%+, the moat is real and multi-layered, management has an unbroken streak of beating revenue guidance, and the four-market expansion (international, corrections, enterprise, federal) reduces concentration risk. The bookings-to-revenue bridge provides unusually high forward visibility for a company at this growth rate.
The case against owning at $393 is equally real: owner earnings FCF was negative $276M in FY2025, the SBC normalization required for the bull case has not started, an unresolved revenue recognition material weakness creates a persistent trust discount on the primary KPIs, and $1.37B of goodwill must perform without impairment across four newly acquired businesses.
**Rating: Monitor.** For existing long holders, the thesis remains intact and trimming is not warranted absent the red light signals described in the catalyst monitor. For new positions, patience at the preferred entry range ($300-$330) produces a materially better risk/reward.
---
*This note was built from AXON’s FY2025 10-K (filed Feb 25, 2026), the FY2024 10-KA (filed May 7, 2025), Q4 2025 earnings transcript (Feb 24, 2026), Q4 2023 earnings transcript (Feb 27, 2024), and FactSet financial tables through FY2025. All dollar figures in thousands unless noted.*
Competitive Analysis Output:
# AXON — Competitive Analysis & Moat Assessment
**As of April 9, 2026 | Built: April 9, 2026**
---
## Market Structure Overview
AXON operates across three overlapping competitive markets:
1. **Conducted energy weapons (CED) / TASER** — near-monopoly; no credible alternative at scale
2. **Body camera + digital evidence management** — dominant market share; primary challenger is Motorola Solutions (Vigilant/Zetron/WatchGuard)
3. **AI-powered public safety software** — early stage; multiple entrants; AXON’s moat is distribution, not model quality
The competitive analysis below addresses each market and the cross-market moat dynamics.
---
## 1. Conducted Energy Weapons (TASER)
### Competitive Position: Near-Monopoly
AXON holds **80-90% market share** in the US CED market. There is no credible domestic or international competitor at volume:
| Competitor | Position | Status |
|---|---|---|
| Axon (TASER 10) | ~85% US market | Dominant |
| Wrap Technologies (BolaWrap) | Non-CED device (entanglement); different use case | Niche; <1% of relevant budget |
| PhaZZer Electronics | Minor CED brand; sold to small departments | Sub-1% market share |
| Karbon Arms | Early stage; raised limited funding | No commercial scale |
| International competitors | Stun batons, low-voltage devices | Not approved for US law enforcement |
**Why no credible TASER competition exists:**
1. **Regulatory moat:** TASER is regulated as a firearm product in many states. The compliance burden for a new entrant (product liability insurance, DOJ/OSHA testing certification, state-by-state approval) takes 5-10 years
2. **Liability moat:** Any new CED entrant inherits catastrophic product liability risk. AXON has over 20 years of deployed product data showing safety profile. A new entrant has no such record — and one serious injury incident could bankrupt a small company
3. **Procurement inertia:** Law enforcement procurement cycles are 5-7 years. Departments that recently purchased TASER 10 will not evaluate alternatives until the next cycle
4. **Training infrastructure:** TASER training programs are embedded in police academies nationally. Switching requires retraining entire departments
**Implication for thesis:** The TASER market is not at competitive risk. The risk is market saturation (most major US departments already equipped) and international approval velocity (country-by-country approval is slow). Apollo cartridge (next-gen, in lab testing) represents the next hardware revenue catalyst.
---
## 2. Body Camera + Digital Evidence Management
### Competitive Position: Market Leader, Challenged
AXON’s primary competitor in body cameras and evidence management is **Motorola Solutions** (following its acquisition of WatchGuard in 2019 and integration of Vigilant Solutions).
| Competitor | Body Camera | Evidence Management | TASER Equivalent | Scale |
|---|---|---|---|---|
| **AXON** | Yes (dominant) | evidence.com | TASER 10 (monopoly) | $2.78B revenue |
| **Motorola Solutions** | Yes (WatchGuard) | CommandCentral | No | ~$10B total revenue (all products) |
| **Digital Ally** | Yes (small scale) | DEMS | No | ~$30M revenue |
| **Genetec** | Limited | Genetec Security Center | No | Private (~$500M est.) |
| **Cellebrite** | No | UFED Analytics | No | ~$350M revenue |
**Motorola Solutions is the most important competitor:**
- Scale: Motorola is the dominant radio/communications provider in law enforcement; every major department has an existing Motorola relationship
- Strategy: Motorola is building an integrated “land mobile radio + body camera + software” stack; evidence management through CommandCentral competes directly with evidence.com
- Advantage: Motorola can bundle body cameras with radio contracts (existing 5-10 year radio deals)
- Disadvantage: Motorola lacks a TASER equivalent; its software is less AI-native than AXON’s; CommandCentral is not as widely deployed as evidence.com
**Where AXON wins the competitive battle:**
1. **Feature velocity:** AXON ships AI features (auto-transcription, evidence.com Assistant) faster than Motorola’s enterprise procurement cycle allows
2. **Data moat:** Departments using evidence.com for 5+ years have terabytes of indexed, legally discoverable video that cannot be migrated without major operational disruption
3. **TASER integration:** AXON’s entire suite is designed around the officer wearing both a TASER and a body camera connected to evidence.com; Motorola cannot replicate this single-vendor integration
4. **NRR 125%:** A 125% NRR in a contested market is very strong evidence of durable competitive position; Motorola’s body camera NRR is not public but is almost certainly lower
**Where Motorola has advantages:**
1. **Radio relationship:** Every major department is already paying Motorola for radios; body cameras can be added to existing purchase orders
2. **IT procurement comfort:** Government IT departments are familiar with Motorola as a prime contractor; AXON is still perceived as a startup in some IT procurement contexts
3. **International:** Motorola has deeper international relationships in Commonwealth countries (UK, Canada, Australia) where AXON is still developing
---
## 3. AI-Powered Public Safety Software
### Competitive Position: Early Mover Advantage, Not Yet Moat
The AI public safety market is in its early innings. Competitors:
| Competitor | Product | Competitive Angle |
|---|---|---|
| **AXON** (Axon Assistant, AI Era Plan) | Evidence transcription, report writing, intelligence | Native hardware integration; 500+ agencies live |
| **Palantir** (Gotham for LE) | Predictive analytics, crime mapping | Data analytics for command centers; not officer-level |
| **SoundThinking** (formerly ShotSpotter) | Gunshot detection + AI dispatch | Sensor network; competes with Fusus/Dedrone for real-time crime center |
| **Carbyne** (AXON-acquired Feb 2026) | AI-powered 911 call handling | Now inside AXON ecosystem |
| **Microsoft (Azure AI)** | General AI tools; potential evidence management | Not public safety-specific; partnership opportunity or threat |
| **Open AI / General LLMs** | Underlying model layer | Risk: commoditization of the model; AXON’s moat must be application layer + data |
**AXON’s key competitive insight on AI (from Q4 2025, Jeff Kunins CTO):**
> “The grounding... is really, one, having the right physical sockets. That’s why hardware plays such a big role... We are marrying [AI] up with a clear and present, very real, specific need for our customers all day, every day in their real job.”
**Translation:** AXON’s AI moat is NOT the LLM. The moat is:
1. **Physical distribution** (body camera = always-on AI endpoint in the field)
2. **Data provenance** (evidence.com data is legally authenticated, chain-of-custody-protected — a specific data type that general LLMs cannot replicate from public training)
3. **Workflow integration** (AI Assistant accessed directly from the camera, not a separate login)
**The risk AXON is not moat-proof against:** If Microsoft or a major cloud provider offers AI-on-top-of-any-camera as a service, AXON’s camera hardware loses some exclusive advantage. However, the evidence.com data moat and TASER integration remain.
---
## 4. Emerging Threats: What Could Disrupt AXON
### Threat 1: AI Commoditization Undermines Software Premium
**Scenario:** AI capabilities (transcription, report writing, evidence summarization) commoditize rapidly. A small startup offers equivalent AI features for $50/officer/year vs. AXON’s AI Era Plan at $400+/year.
**AXON’s defense:** Physical sockets (hardware), data provenance (legally-required chain of custody), and workflow embedding. The AI feature itself is less differentiated than the AI-in-context-of-a-law-enforcement-workflow.
**Probability: Medium.** AI transcription commoditizes fast. AI for evidence analysis with legal-grade provenance does not commoditize as quickly because it requires the specific data (body camera footage, authenticated metadata) that AXON’s ecosystem generates.
### Threat 2: Motorola Bundles Body Cameras into Radio Contracts at Zero Marginal Cost
**Scenario:** Motorola offers free body camera upgrades to departments renewing radio contracts, undercutting AXON’s camera pricing.
**AXON’s defense:** Evidence.com lock-in (years of stored video), TASER-camera integration, and superior AI features. A department would still need to pay for cloud storage and analytics even if cameras are “free.”
**Probability: Low-Medium.** This tactic would require Motorola to subsidize cameras (gross margin hit) and build parity software — neither is easy.
### Threat 3: Federal Government Mandates Open Standards for Body Camera Data
**Scenario:** DOJ or NIST mandates open data formats and data portability for body camera evidence, breaking the evidence.com lock-in.
**AXON’s defense:** Limited. If data portability is mandated, the switching cost advantage erodes. AXON would still have the hardware relationship and AI feature lead, but the software moat weakens.
**Probability: Low in 2-3 years.** Government data standards move slowly; interoperability mandates would be politically complex given law enforcement union preferences. This is a 5-10 year risk, not a near-term threat.
### Threat 4: Privacy Regulation Limits AI Evidence Analysis
**Scenario:** GDPR-equivalent US privacy law prohibits AI analysis of footage without explicit consent, limiting Axon Assistant’s use in criminal investigations.
**AXON’s defense:** Rick Smith explicitly identified privacy and data handling as the #1 failure risk. AXON’s legal and policy team is active in law enforcement AI governance. The risk is real but manageable if AXON stays ahead of regulation rather than being caught reactive.
**Probability: Medium (3-5 year horizon).** State-level AI regulations (California, Illinois, New York) are the most likely near-term constraint.
---
## 5. Moat Scorecard
| Moat Type | Strength | Durability | Evidence |
|---|---|---|---|
| Switching costs (evidence.com) | **High** | **High** | NRR 125%; multi-year legal data storage creates near-permanent relationship |
| Regulatory barriers (TASER) | **High** | **High** | 5-10 year approval process; liability insurance barrier |
| Scale advantages (SaaS) | **Medium** | **Medium** | 74% services GM; marginal cost near zero; but not truly network-effect-driven |
| Network effects | **Low-Medium** | **Medium** | Some (shared intelligence in Fusus/real-time crime centers); not classic two-sided network effects |
| Hardware integration | **High** | **Medium** | TASER + camera + software bundle; risk if cameras commoditize |
| Brand/trust | **High** | **High** | AXON is the trusted name in law enforcement technology; 20+ year track record |
| Data moat | **High** | **High** | Evidence.com contains legally authenticated, chain-of-custody-protected law enforcement data; cannot be recreated by competitors |
| AI moat | **Low-Medium** | **Low-Medium** | Feature lead today; commoditization risk in 3-5 years for basic AI; workflow integration is the durable component |
**Overall moat rating: HIGH.** AXON has a genuine, multi-layered competitive moat. The combination of switching costs, regulatory barriers, data provenance, and hardware integration is not replicated by any current competitor. The risk is AI commoditization and Motorola bundle tactics in a 3-5 year horizon.
---
## 6. Competitive Position Implications for the Thesis
**What the competitive landscape confirms:**
- Revenue durability is high: NRR 125% and 5-10 year contract locks are genuine
- TASER monopoly is a floor on downside: even in a bad scenario, TASER alone approaches $1B of revenue at ~50% GM
- AI Era Plan is genuinely differentiated for 2-3 years: the workflow integration (camera → AI → report writing → evidence.com upload) is not easily replicated
**What the competitive landscape challenges:**
- The services gross margin expansion to 76-77% requires AI inference costs to remain low — competitive pressure on AI model costs could work in AXON’s favor (cheaper models) or against it (competitors matching features at lower price points)
- International expansion faces Motorola’s radio relationships in key markets; AXON must win on AI and camera quality, not existing relationships
**Competitive conclusion for valuation:** The moat supports a premium EV/Adj EBITDA multiple relative to un-moated gov-tech peers (Motorola at 22x; Tyler at 35x). AXON at 35x NTM adj EBITDA is in-line with the moated peer (Tyler), which is appropriate given AXON’s higher growth rate but worse FCF quality. The stock would deserve 40-50x NTM adj EBITDA if FCF quality improves — this is the re-rating scenario.
Contra Output:
# AXON — Bear Case / Contra Memo
**As of April 9, 2026 | Price: $393 | Market Cap: $31.5B**
**This memo represents the strongest case against owning AXON at the current price. It is not a prediction — it is an adversarial analysis.**
---
## The Central Claim
AXON is an excellent business trading at a price that requires multiple simultaneously optimistic assumptions to be correct. You can lose money on AXON without the company failing, without a recession, and without a competitor winning a single customer. The bear case is almost entirely a valuation and cash quality story: at $393, the margin for error is thin enough that even modest disappointment in SBC normalization, ARR growth, or goodwill performance creates a stock that trades to $200-250 before the business itself has materially deteriorated.
---
## Bear Argument 1: The Economics Are Structurally Worse Than They Look
### What Management Reports vs. What the Company Earns
| Metric | Management View | Economic Reality |
|---|---|---|
| FY2025 Adj EBITDA | $706M (25.4% margin) | After $634M SBC add-back; not cash |
| FY2025 Reported FCF | $75M (2.7% margin) | After working capital drag; before SBC taxes |
| FY2025 Owner Earnings FCF | — | **Negative $276M** after $351M net-settle SBC taxes |
| FY2025 Economic EBIT | — | **Negative $147M** (EBIT minus CapEx reinvestment requirement) |
The company generated $706M of adj EBITDA and negative $276M of economic free cash flow. This is not a “transitional year” narrative — it is a structural reality that the company’s compensation model consumes more cash than it generates.
**The math that the bull case requires:**
- SBC must decline from $634M (23% of revenue) to $720M (12% of revenue by FY2028)
- This means SBC grows in absolute terms but revenue grows faster
- But SBC is driven by grants, not revenue — if the stock stays above $350, unvested awards continue to generate large tax bills at vesting
- If the stock falls to $250-300 during the bear scenario, SBC grant value per share declines, reducing net-settle taxes — an ironic self-healing mechanism — but this also means shares are cheaper while the thesis requires a premium multiple
The SBC normalization story is circular: it requires AXON’s stock to decline enough to reduce grant values, which contradicts the bull case stock price that makes the grants large. Management has not outlined a concrete plan to reduce grant sizes in absolute dollar terms.
---
## Bear Argument 2: The FCF Credibility Gap Is Structural, Not Cyclical
Management has predicted “returning toward 60% FCF conversion” twice:
1. After FY2023 miss (42% actual): “FY2024 will recover toward 60%.” Actual: 67%. The prediction proved right.
2. After FY2025 miss (11% actual): “FY2026 will recover toward 60%.” Same language.
**The bull response:** FY2024 was a real recovery, so the pattern holds. FY2025 was distorted by the PSU vesting ($351M net-settle taxes) — a large, one-time cohort.
**The bear response:** FY2025 PSU vesting was predictable from the stock price milestones management set in 2021-2023. The “one-time” distortion is actually the result of management’s own compensation design. Nothing has changed in that design:
- PSU milestones remain in place for future grants
- Stock price is still $393 — any new milestone hit creates another large SBC tax bill
- FY2026 guidance of “back toward 60%” ($540M reported FCF on $900M adj EBITDA) requires working capital to provide $400M+ of tailwind — this is optimistic given that bookings growth of 25%+ generates new contract assets (which consumed $505M in FY2025)
**If FY2026 reported FCF is $250-350M instead of $540M (a plausible scenario):** The FCF miss narrative becomes permanent. Management’s credibility on cash generation targets falls from Medium (current) to Low. Multiple re-ratings from 35x to 25x adj EBITDA are possible. At 25x FY2026E adj EBITDA ($900M × 25x = $22.5B EV, minus net cash ~$0 → ~$22.5B equity / 83M shares = **$271/share**). This is a ~31% decline from $393 without any revenue disappointment.
---
## Bear Argument 3: The Goodwill Is a Time Bomb
### The Goodwill Math
| Acquisition | Approximate Goodwill | Year Acquired | Revenue Track Record |
|---|---|---|---|
| Dedrone | ~$427M | FY2024 | Pre-acquisition; not yet proven in AXON ecosystem |
| Fusus | ~$200-300M (est.) | FY2025 | Early; integrated Q3-Q4 2025 |
| Prepared | ~$75-100M (est.) | Q4 2025 | Very early; school safety market |
| Carbyne | ~$400-500M (est. FY2026) | Closes Feb 2026 | Emergency communications; not yet consolidated |
| **Total** | **~$1.37B (FY2025) + ~$400M Carbyne** | | |
**Impairment test:** Goodwill is tested annually for impairment. If any reporting unit’s fair value falls below carrying value, the difference is written off as an impairment charge.
**What could trigger impairment:**
1. **Dedrone** ($427M goodwill): Drone security market is competitive (Skydio, DJI enterprise products); drone detection regulation varies internationally; failure to achieve expected ARR growth within the AXON ecosystem
2. **Carbyne** (~$400-500M estimated goodwill): Emergency communications is a fragmented market; Carbyne competes with Motorola, Zetron, and Frequentis for 911 technology; success depends on winning large-city 911 contracts
3. **Fusus**: Real-time crime center intelligence is new and politically sensitive (surveillance concerns); cities are canceling surveillance programs; failure modes include political opposition and privacy legislation
4. **Prepared**: School safety market is driven by tragedy-response procurement (purchases spike after mass shootings, then slow); sustainable recurring revenue from school districts is unproven
**The impairment scenario:**
- Carbyne fails to win a major city 911 contract by FY2027; goodwill write-down ~$200-400M
- Fusus faces surveillance backlash in 2-3 major cities; contract cancellations; goodwill write-down ~$100-200M
- Total impairment: $300-600M before tax
At 21% tax rate, a $500M goodwill write-down creates a $500M non-cash charge to GAAP net income (goodwill impairment is not tax-deductible in most cases). This would:
- Wipe out 4+ years of GAAP net income in one quarter
- Trigger technical covenants in credit agreements (net worth tests)
- Create headlines that overwhelm the operating narrative even if core TASER and camera business is fine
**Probability:** Not high in any single year, but the cumulative probability of at least one meaningful impairment across four acquired businesses over 3 years is **meaningfully above zero** — perhaps 25-40% that at least one write-down of $100M+ occurs by FY2028.
---
## Bear Argument 4: The Revenue Recognition Material Weakness Invalidates the Primary KPIs
This is the most underappreciated risk in the consensus bullish narrative.
**What we know:**
- FY2024 10-KA revealed a material weakness in revenue recognition controls — controls did not properly evaluate contract term, cancellation provisions, termination penalties, and modification accounting
- The weakness remained unresolved as of December 31, 2025
- PwC flagged this as a critical audit matter in the FY2025 audit opinion
**What this means for the bull case:**
- ARR ($1.3B+) is calculated from multi-year contracts with specific cancellation and termination provisions
- If the revenue recognition weakness means some of those contracts were incorrectly evaluated (e.g., cancellable-without-penalty contracts were treated as non-cancellable), then ARR is overstated
- NRR (125%) is calculated as the revenue retained from existing customers including upsells — if original period revenue was overstated, the NRR calculation base is inflated
- Bookings ($7.4B) includes multi-year TCV that depends on contract term interpretation — the same weakness that affected revenue recognition in completed periods could affect the bookings count for new periods
**The worst-case scenario:** Auditors eventually require AXON to re-evaluate a portion of the $7.4B backlog and determine that 5-10% was incorrectly classified as “future contracted” (e.g., contracts with genuine cancellation rights without penalty that should be excluded from TCV). A 10% downward revision to bookings would remove $740M of future contracted revenue — reducing the bookings-to-revenue bridge for FY2026 by ~$150-180M, or roughly 4-5% of guided FY2026 revenue.
**Is this likely?** The existing restatement corrections were small (described as “immaterial”). But the weakness is specifically about the evaluation of contract terms that determine bookings recognition. Until remediated, this risk cannot be dismissed.
---
## Bear Argument 5: The Market Structure is More Competitive Than the Moat Narrative Implies
### The Body Camera War
Motorola Solutions is not a casual competitor. With ~$10B of revenue, Motorola can:
- Subsidize body cameras within radio contract renewals
- Invest $300-500M in CommandCentral evidence management improvement
- Leverage existing IT procurement relationships to embed software
If Motorola wins 30% of new camera deployments and 20% of evidence management renewals over the next 5 years, AXON’s NRR may not sustain 125%. At 115% NRR (Motorola-competition scenario), the ARR compounding math from Section 2 of unit-economics.md yields a 7-year multiplier of 2.7x (vs. 4.8x at 125% NRR) — a 44% reduction in future ARR potential.
### AI Commoditization Is Faster Than the Bull Case Assumes
Axon Assistant costs hundreds of dollars per officer per year as part of the AI Era Plan. Competitors (including Palantir, Microsoft Azure, and startups) are building AI tools for law enforcement that run on any camera system. If:
- Transcription APIs become commodity (already happening via OpenAI Whisper, Google APIs)
- Report writing becomes standard in Microsoft Copilot for Government (available at incremental cost to Microsoft 365 licenses many departments already use)
- Evidence analysis AI integrates with standard cloud storage rather than requiring evidence.com
Then the AI Era Plan’s pricing power erodes. At $50/officer/year for commodity AI (vs. $200-400/year for AXON’s plan), the AI Era Plan economics fall apart. ARPU stays near $600 rather than growing to $900-1,200, and the services mix doesn’t accelerate as modeled.
---
## Bear Argument 6: The Federal Opportunity Is Newly Risky
Management called out “some of our largest opportunities in front of us for 2026 could come from federal” at the Q4 2025 call. This is a new and substantial disclosure.
**Context:** DOGE (Department of Government Efficiency), the federal spending review body, is explicitly scrutinizing law enforcement technology spending. The FBI, ATF, DEA, and Customs and Border Protection are all potential AXON customers — but also organizations that are being reviewed for technology spending.
**Bear scenario:** Federal procurement is delayed 12-18 months due to spending reviews; the “large federal opportunities” flagged for FY2026 slip to FY2027-2028. This would:
- Create a bookings miss in FY2026 despite strong state/local and international
- Disappoint an investor base now expecting federal as an incremental growth driver
- Force management to revise the narrative on federal just as the stock needed the catalyst
Federal is high-upside, high-uncertainty — exactly the wrong type of catalyst to lean into when the stock already trades at 35x NTM adj EBITDA.
---
## Bear Argument 7: The Price Target Math — What Loss Looks Like
At 15x FY2028E adj EBITDA (bear case):
- FY2028E adj EBITDA: $1,056M (22% margin on $4.8B revenue)
- 15x × $1,056M = $15.8B EV
- Less net debt: ~$1.1B → equity value $14.7B
- 85M shares → **$173/share**
- From $393: **-56% loss**
How do you get to the bear case without business failure?
- Revenue $4.8B instead of $6.0B (20% revenue shortfall from base case) — possible if AI Era Plan doesn’t accelerate and bookings decelerate to 15-20% growth
- EBITDA margin 22% instead of 28% — possible if SBC stays at 20%+ of revenue rather than declining to 12%
- Multiple 15x instead of 18x — reflects market’s lower tolerance for elevated multiples when FCF quality is persistently poor
**None of this requires AXON to “fail.”** TASER dominance can be intact. Body camera leadership can be intact. NRR can be 120%. The company can be growing 25% per year. And the stock still falls 56%.
This is the correct bear case framing: **it is not about the business, it is about the price requiring too many things to go right.**
---
## Bear Confidence Assessment
| Bear Argument | Probability | Severity if True |
|---|---|---|
| FCF fails to recover in FY2026 | 35% | -20 to -30% multiple compression |
| Revenue recognition weakness causes further restatement | 20% | -10 to -20% (trust discount) |
| Goodwill impairment ($200-500M) | 30% | -5 to -15% direct; sentiment impact larger |
| AI Era Plan penetration stalls at 30% | 40% | -10 to -20% (ARPU growth thesis) |
| Federal opportunity delays | 40% | -5 to -10% on 2026 bookings |
| Motorola/competition erodes NRR to 115% | 25% | -20 to -30% (ARR compounding story) |
No single argument is highly probable. But these risks are not independent — a FCF miss in FY2026 would likely coincide with negative sentiment on AI Era Plan and would give bears the ammunition to push for multiple compression. The correlation between these risks is the actual bear case.
---
## What Would Invalidate the Bear Case
1. **Revenue recognition material weakness remediated by Q2 2026 announcement** — trust in ARR/NRR metrics restored; 5-10% sentiment recovery
2. **FY2026 Q1-Q2 reported FCF runs above $300M** — proves “returning toward 60%” with early data; bull narrative on cash quality strengthened
3. **AI Era Plan penetration disclosed above 50% of eligible customers** — ARPU expansion on track; services mix shift accelerating
4. **FY2026 bookings grow 30%+** — forward revenue pre-visibility improves; bull case confirmed
5. **Carbyne wins a major city 911 contract** — validates goodwill; reduces impairment risk; confirms Axon 911 strategy
If these four events occur in FY2026, the bear case is substantially invalidated and the stock’s re-rating toward 45-50x NTM adj EBITDA is justified.
---
## Short Thesis Construction
For an investor considering a short position in AXON, the thesis would be:
**Position:** Short AXON at $393; target $250-280 (35-37% downside)
**Horizon:** 12-18 months
**Trigger:** Q1 or Q2 2026 earnings showing FCF fails to recover as guided
**Catalyst sequence:** FCF disappointment → management credibility further questioned → consensus lowers FY2027-28 adj EBITDA estimates → multiple contracts toward 25x → stock declines to $250-280
**Key risks to the short:**
- Takeover premium: AXON could attract a strategic acquirer (Microsoft, Palantir, Motorola) at a significant premium
- FY2026 bookings beat: if bookings grow 40%+, the forward revenue story overwhelms near-term FCF concerns
- NRR acceleration: if AI Era Plan pushes NRR above 130%, the compounding math overwhelms the SBC concern
**Short risk/reward assessment:** -1:1 at best (target downside 35%, upside potential 30-40% if a positive catalyst hits). This is NOT an attractive short at current price levels — the fundamental business quality creates too much “squeeze” risk. The bear case is stronger as a reason to avoid ownership than as an active short.
Unit Economics Output:
# AXON — Unit Economics & Economic Margin Analysis
**As of April 9, 2026 | Built: April 9, 2026**
---
## Why Unit Economics Matter for AXON
AXON’s blended gross margin (59.7% in FY2025) is the wrong lens. The company’s economics operate at three distinct levels:
1. **Hardware unit economics** — TASER and camera COGS, upgrade cycle dynamics, cost absorption
2. **Software unit economics** — per-officer SaaS subscription, ARPU expansion, renewal mechanics
3. **Enterprise LTV economics** — lifetime value of a department contract, bookings-to-revenue conversion, NRR compounding
Standard industrial margin analysis (revenue, COGS, gross profit) completely misses items 2 and 3. This file reconstructs the economics from the unit level.
---
## Section 1: Per-Officer Economics
### 1.1 ARPU Trajectory
The fundamental unit of AXON’s business is the **sworn officer** equipped with an OSP (Officer Safety Plan) subscription. ARPU is the key driver of ARR growth beyond new department wins.
| Period | ARPU (premium plan estimate) | Source |
|---|---|---|
| FY2020 | ~$150/officer/year | Historical management disclosure |
| FY2022 | ~$250/officer/year | “Most premium offering under $250” (Bagley, Q4 2025) |
| FY2024 | ~$400/officer/year | Interpolated from ARR and estimated officer count |
| FY2025 | ~$600/officer/year | Bagley: “nearly $600” for officer-based plans |
| FY2026-28 (if AI EP reaches 70%) | ~$900-1,200/officer/year | Estimated AI Era Plan add-on of $200-400/officer |
**Officer count estimate:**
- ARR ~$1,300M at $600/officer = ~2.2M officer-equivalent subscriptions (includes multiple products per officer; some departments have TASER without camera, etc.)
- Active US sworn law enforcement officers: ~800,000 total national estimate
- AXON penetration of US officers: meaningful but well below 100% in many jurisdictions; ARPU expansion within existing customers is the primary growth lever
**Analytical implication:** AXON does not need to win many new officers to grow ARR at 25-35%. Expanding ARPU from $600 toward $900-1,200 through AI Era Plan upsell on existing 800,000+ officer base generates $240-480M of incremental annual revenue at the existing customer base alone.
### 1.2 Gross Margin Per Officer (Software Layer)
For the services (SaaS) segment, the unit economics are exceptional:
| Metric | Value |
|---|---|
| Services revenue FY2025 | $1,203M |
| Services COGS FY2025 | $312M |
| Services gross profit | $891M |
| Services gross margin | 74.0% |
At 74% gross margin, each $1 of additional services revenue generates $0.74 of incremental gross profit. The marginal cost of adding another officer to evidence.com is nearly zero (data storage and bandwidth are cloud-variable). This is true SaaS economics.
**Cost breakdown of services COGS (estimated from peer comparisons):**
- Hosting and cloud infrastructure: ~40-45% of services COGS
- Customer success / implementation labor: ~30-35%
- Data processing and AI inference costs: ~15-20% (growing as AI adoption increases)
- Third-party licenses: ~5-10%
**Key watch:** AI inference costs (GPU compute for Axon Assistant, transcription, evidence analysis) are the primary structural risk to services GM. If AI Era Plan customers heavily utilize AI features, compute costs could push services COGS toward 28-30% (services GM toward 70-72% from current 74%). Management targets “at least 75% services gross margin” — achievable only if AI cost per interaction declines with model efficiency.
### 1.3 Hardware Unit Economics (TASER 10)
| Metric | Estimate |
|---|---|
| TASER revenue Q4 2025 | $264M (~$1B run rate) |
| Product gross margin FY2025 | 48.7% |
| Implied TASER unit gross profit | ~$128M per quarter at run rate |
**TASER cartridge economics:** “TASER cartridge is fired every 30 seconds in the US” (Q4 2025). At ~$1M consumable revenue per firing cycle... this is a consumable replacement model where the device creates a recurring demand stream. Each TASER 10 deployment locks in 5-10 years of cartridge consumption.
**TASER 10 vs. TASER 7 economics:**
- TASER 10 has lower gross margin initially (manufacturing scale-up, higher precision components)
- Product GM: 54.7% (FY2022) → 48.7% (FY2025) — 600bps compression over the TASER 10 ramp
- Management indicates cost absorption is underway; automation investments should recover 200-300bps
- Apollo cartridge (next-generation, in lab testing) could reset product margins if launched at TASER 10 volume scale
---
## Section 2: Lifetime Value (LTV) Analysis
### 2.1 LTV Model for a Department Contract
**Assumptions for a mid-size department (500 officers):**
| Input | Value |
|---|---|
| Contract term | 7 years average (5-10 year range) |
| Officers | 500 |
| ARPU (year 1) | $600/officer/year |
| ARPU (year 7, at 20% CAGR) | $1,800/officer/year |
| Blended ARPU over 7 years | ~$1,000/officer/year |
| Total software revenue | $3.5M/year blended × 7 = $24.5M |
| Total hardware revenue | TASER (est.) + cameras = ~$1.5M upfront + ~$500K/year refreshes |
| **Total contract revenue** | **~$28M over 7 years** |
| Software gross profit (74%) | ~$18.1M |
| Hardware gross profit (49%) | ~$1.2M upfront + ~$245K/year |
| **Total gross profit** | **~$20M over 7 years** |
| Average annual gross profit per department | **~$2.9M/year** |
**This single department generates $28M in lifetime revenue** at current ARPU growth rates. This does not include AI Era Plan upside — if the department moves to the AI Era Plan ($900-1,200 ARPU), the LTV grows toward $40-50M.
### 2.2 NRR-Implied LTV Multiplier
NRR of 125% means every $1 of initial contract ARR becomes $1.25 in the following year from the same customer base. This compounds:
| Year | Revenue Index |
|---|---|
| Year 0 | $1.00 |
| Year 1 | $1.25 |
| Year 2 | $1.56 |
| Year 3 | $1.95 |
| Year 5 | $3.05 |
| Year 7 | $4.77 |
At 125% NRR, a cohort of customers generating $1B of ARR in year 0 should generate $4.8B by year 7 (before any new customer adds). This is the mathematical foundation of AXON’s 2028 revenue target: existing customers compound revenue faster than typically priced in.
**NRR sensitivity:** If NRR falls to 115%, the 7-year multiple is ~2.7x (from $1 to $2.7) — still compelling but materially lower. If NRR returns to 130% (above recent peaks), the multiple reaches 6.3x in 7 years. NRR is the most powerful lever in the unit economics.
### 2.3 Customer Acquisition Cost Context
AXON does not disclose CAC explicitly. Proxy from financials:
- FY2025 SG&A: $1,036M (includes SBC, field sales, marketing)
- Less: SBC embedded in SG&A (~40% of $634M = ~$254M) → cash SG&A ~$782M
- ARR added in FY2025: ~$1,300M end − ~$1,050M start = ~$250M net new ARR
- Implied S&M CAC per $1 of ARR: ~$782M / $250M = **$3.1 to acquire $1 of annual recurring revenue**
At 125% NRR, the LTV/CAC on a per-ARR basis is extremely attractive:
- LTV (7 years at 125% NRR): $4.77 per $1 initial ARR
- CAC: $3.1 per $1 initial ARR
- **LTV/CAC: ~1.5x on year 1 ARR alone** — improves dramatically as NRR compounds
This LTV/CAC analysis understates the true efficiency because SG&A includes SBC and non-sales overhead. Adjusted for pure sales productivity, the CAC is lower and LTV/CAC more favorable.
---
## Section 3: Bookings Economics and ARR Flywheel
### 3.1 The Bookings-Revenue-ARR Bridge
AXON’s business converts in three stages:
1. **Bookings** → signed contract value (TCV) committed to AXON but not yet recognized
2. **Future contracted bookings** → the unrecognized portion of all signed contracts
3. **ARR / Revenue** → what is actually recognized in the current year
Mechanics (per Bagley, Q4 2025):
- 20-25% of future contracted bookings converts to recognized revenue in the following year
- This creates a “look-through” model where FY2026 revenue is substantially determined by end-of-FY2025 contracted bookings
**The flywheel:**
- Higher bookings → more future contracted → more forward revenue certainty
- Higher NRR → existing contracts expand, adding to ARR without new CAC spend
- Higher ARR → higher recurring revenue base → adj EBITDA leverage as services margin (~74%) exceeds blended margin (~60%)
### 3.2 ARR Quality Assessment
AXON’s ARR ($1.3B+ as of Q4 2025) includes:
- Hardware subscription (TASER subscriptions, camera subscriptions): ~40-45% of ARR
- Software/SaaS (evidence.com, AI Era Plan, records): ~50-55% of ARR
- Professional services (implementation, one-time): excluded from ARR (correctly)
**ARR vs. reported services revenue (~$1.2B FY2025):** The relationship is close but not 1:1 because:
- ARR includes some hardware subscription value
- Some services revenue is non-recurring (professional services, implementation)
- Contract timing creates lag between ARR and revenue recognition
The implied ARR quality is high — NRR of 125% and 5-10 year contract structures suggest a very sticky, durable revenue stream.
### 3.3 Margin Path Analysis
**The core margin expansion thesis:**
As services mix grows from 43% (FY2025) to 51.5% (FY2028E), blended gross margin expands from 59.7% to 64%+. This 430bps of blended GM improvement falls through to adj EBITDA at nearly 1:1 (assuming opex grows slower than revenue).
**The math:**
- For every 1 percentage point of services mix shift (+1ppt), blended GM improves by ~0.25ppts
- (Services GM 74% − Product GM 49%) × 1% mix shift = 0.25ppts blended GM
- FY2025 → FY2028E: 43% → 51.5% = 8.5ppt services mix shift
- Blended GM improvement: 8.5 × 0.25 = ~2.1ppts from mix alone
- Plus: services GM improving from 74% to 77%+: adds ~1.7ppts blended
- Total blended GM improvement: ~4.3ppts ✓ (consistent with model trajectory from 59.7% → 64%)
**Risk to the margin path:** Q4 2025 blended GM was 57.9% — 180bps below FY2025 average. If hardware seasonality structurally worsens (TASER upgrade cycles, corrections deployments skewed to year-end), the mix effect could be slower than modeled. The critical test is whether Q1 2026 GM recovers to 60%+.
---
## Section 4: Economic Margin Reconstruction
Standard adj EBITDA margin (25.4% FY2025) overestimates true economic margin by the SBC cost:
| Metric | FY2025 Value | % of Revenue |
|---|---|---|
| Adj EBITDA (management) | $706M | 25.4% |
| Less: SBC (real economic cost) | -$634M | -22.8% |
| Less: D&A (approximated cash cost in CapEx) | -$83M | -3.0% |
| Plus: CapEx (reinvestment needed) | -$136M | -4.9% |
| **Economic EBIT (owner earnings)** | **-$147M** | **-5.3%** |
**Economic EBIT is negative in FY2025.** This is not a sign of business failure — it reflects a company in heavy investment mode (AI infrastructure, manufacturing scale-up, acquisition integration). But it confirms that the **current economics do not support the current price** on a stand-alone basis. The investment thesis is entirely about future economic margin expansion.
**Economic margin path to FY2028:**
| | FY2025A | FY2026E | FY2027E | FY2028E |
|---|---|---|---|---|
| Adj EBITDA | $706M | $900M | $1,324M | $1,887M |
| Less: SBC | -$634M | -$660M | -$720M | -$720M |
| Less: D&A | -$83M | -$110M | -$140M | -$170M |
| Less: CapEx | -$136M | -$175M | -$215M | -$260M |
| **Economic EBIT** | **-$147M** | **-$45M** | **$249M** | **$737M** |
| **Economic margin** | **-5.3%** | **-1.3%** | **5.5%** | **12.3%** |
The path from -5.3% economic margin (FY2025) to +12.3% (FY2028) is a 17.6 percentage point expansion over three years. This is the real investment thesis — not the adj EBITDA margin improving from 25% to 32%, but economic margin turning positive and scaling.
**This expansion requires simultaneously:**
- Revenue at $6B (bookings-dependent)
- SBC flat in absolute terms (declining as % of revenue)
- CapEx below 4.5% of revenue
- D&A absorbed by the business model
---
## Section 5: Segment Contribution Analysis
### Software-Only Economics (Services Segment)
| Metric | FY2025 |
|---|---|
| Services revenue | $1,203M |
| Services gross profit (74%) | $891M |
| Implied services contribution | $891M |
| Services as % of total revenue | 43.3% |
| Services as % of total gross profit | 53.7% |
The services segment generates 53.7% of total gross profit on 43.3% of revenue — confirming the substantial margin advantage of the software layer. Every 1% of services mix shift adds ~$8M of annual gross profit at current revenue scale (~$34M at FY2028E revenue).
### Hardware Segment Contribution and Cycle Risk
| TASER metrics | Q4 2025 |
|---|---|
| TASER revenue | $264M (annualized ~$1.0B) |
| TASER segment GM (est.) | ~50% |
| TASER gross profit | ~$132M quarterly |
TASER approaching $1B annual run rate is the single largest product revenue line. At 50% GM, each $1B of TASER revenue generates $500M of gross profit — material. The cycle risk is that TASER upgrade cycles are lumpy: departments that already upgraded to TASER 10 may not refresh for 5-7 years. The next revenue catalyst from hardware is the Apollo cartridge (in lab testing; expected to be a FY2027+ item).
---
## Section 6: AI Era Plan — Unit Economics (Partial Visibility)
The AI Era Plan is AXON’s highest-growth, highest-price product tier. The economics are partially disclosed:
| Known | Value |
|---|---|
| FY2025 AI Era Plan bookings | $750M |
| Number of agencies live | 500+ |
| Monthly messages (Axon Assistant) | >200,000 |
| % of customers on premium plan | ~30% |
| Estimated ARPU per AI-enabled officer (above base plan) | ~$200-400/year (not disclosed directly) |
**Implied per-agency economics:** $750M / 500 agencies = $1.5M average booking per agency. For a 500-officer department at a 5-year contract, this implies ~$600/officer/year for the full AI plan. This is consistent with Bagley’s “nearly $600 for officer-based subscription plans” — suggesting AI Era Plan is priced at approximately 2x the base OSP plan.
**The 30% → 70% penetration opportunity:** If AXON moves from 30% to 70% of customers on the AI Era Plan at $200-400/year incremental ARPU:
- Incremental ARPU per officer: $300 (midpoint)
- Estimated officer base: 2M+ in AXON ecosystem
- Incremental ARR from penetration expansion: 40% additional × 2M officers × $300 = ~$240M annual recurring revenue
- Plus renewing cohorts at higher ARPU: compounds this further
This math supports the claim that AI Era Plan alone has $500M+ of incremental ARR potential from existing customers.
**Risk to the AI unit economics:**
- AI inference costs (GPU compute) erode services gross margin below 74%
- Agencies don’t renew at the higher price point after initial contract term
- Competing AI-on-top-of-camera solutions (from competitors or open-source) reduce AXON’s pricing power
---
## Summary: Economic Investment Thesis in Unit Terms
The investment case at the unit level:
| Unit | Today | FY2028 Target | Driver |
|---|---|---|---|
| ARPU per officer | ~$600/year | ~$900-1,200/year | AI Era Plan upsell; plan tier migration |
| Services gross margin | 74% | 76-77% | Leverage; marginal cost near zero |
| Blended gross margin | 59.7% | 63-64% | Mix shift to services (43% → 51%) |
| NRR | 125% | 120-125% | Stable; slight normalization expected |
| LTV/CAC | ~1.5x first-year ARR | Improving | As NRR compounds over 7-year contracts |
| Economic margin | -5.3% | +12.3% | SBC normalization + revenue leverage |
**The “must win” at the unit level:** The model works only if ARPU expands from $600 to $900+ through AI Era Plan adoption by FY2028. If AI Era Plan adoption stalls at 30% of customers (current) and ARPU stays near $600, services revenue growth decelerates toward 20%, blended GM stays at 60%, and the FY2028 revenue model falls to $5B rather than $6B. The margin structure still works, but the terminal value is ~15-20% lower.
**The “must not break” at the unit level:** NRR must stay above 115%. Below 115%, existing customer expansion can no longer fund the growth model and new customer CAC must increase to compensate. There is no recent evidence of NRR deterioration (125% is at 3-year highs), but continued service quality and feature delivery (especially AI) are necessary conditions.
You are posting content in the markdown format. Please convert it to user friendly format as it's getting difficult to read your post on my mobile phone
This is awesome