

Made a webapp that is hosted on my local server which pulls the markdown output files generated by the equity research workflow and saved to my local server, converts them into a user friendly readable note with drops downs to select the company and the report I want to read. Now I can run the /analyze <ticker> command and after the run is over the output is directly fed to the webapp for reading. The only manual part that remains is feeding the primary data sources (K/Qs/transcripts) which will be hard to automate without spending money.
Date: April 15, 2026
Current Price: $1,437.03 USD / €1,217 EUR (verified via yfinance, April 15, 2026; EUR/USD 1.1804)
Prior close (April 14): $1,518.30 | Today’s open: $1,473.37 | Day change: −5.4%
Market Cap: ~€469B | Net cash (cash+ST inv. €8.4B less LT debt €2.7B): ~€5.7B | EV: ~€463B
Stock reaction: DOWN ~5.4% from prior close on earnings day — gapped lower at open ($1,473) and continued selling off to ~$1,437
Sources: Q1 2026 earnings call transcript (April 15, 2026), Preliminary Earnings Report Q1 2026 (GAAP financial statements), Q4 2025 earnings call, earnings preview (April 15, 2026), synthesis, expectations-bridge
Executive Summary
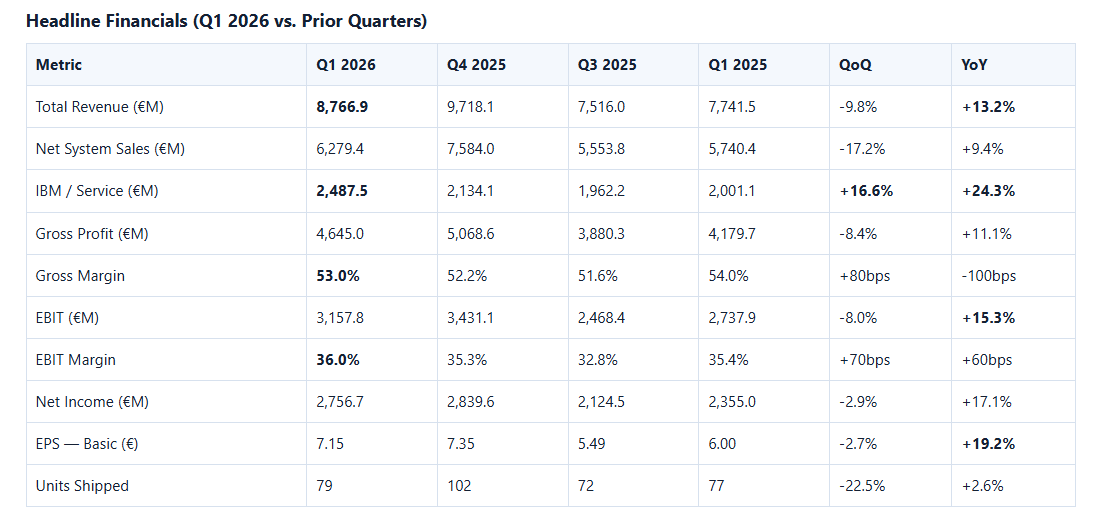
Q1 2026 was a genuine beat across the metrics that matter — revenue +13% YoY, IBM growing +24% YoY to €2.5B, gross margin at 53.0% (high end of guidance), and FY2026 raised to €36-40B from €30-35B. Despite all of that, the stock is down ~5.4% on the day. The selloff is almost entirely explained by the Q2 gross margin guide of 51-52% — below Q1’s 53% — which the market interpreted as confirmation that Q1 was a mix anomaly (high-margin software upgrades in IBM), not a new sustainable floor. The stock had also pre-run into earnings: pre-earnings positioning drove ASML from $1,478 on April 10 to $1,518 by April 14 close — before ASML reported anything. Results were released pre-market on April 15, and the Q2 GM guide in the press release was the sting; the stock opened down 3% at $1,473 before the formal call began and continued lower through the session. The read on the underlying thesis: intact and accelerating. DRAM is described as a “perfect storm” for ASML. The 2027 EUV capacity target was raised to “at least 80” systems. EUV ASP improvement in 2027 was explicitly confirmed. And management hinted that the CMD November 2024 long-term scenarios (€44-60B by 2030) will need to be revised upward at the next CMD. The down move is a Q2 margin reaction, not a fundamental deterioration — but it warrants watching whether Q2 GM lands at the high or low end of 51-52%.
Scorecard
Headline Quarter: 4/5 — Revenue +13% YoY, EBIT +15%, EPS +19%; system sales and IBM both above the Q1 implied run-rate of the old guidance
Quality of Quarter: 3/5 — GM at 53% was partly elevated by an unusual concentration of high-margin software-based IBM upgrades that management explicitly flagged as non-repeating in Q2; system unit count +2.6% YoY (79 vs. 77) is modest
Guidance / Forward Signal: 5/5 — FY2026 raised €5.5B at midpoint; 2027 EUV capacity target “at least 80”; ASP improvement in 2027 explicitly confirmed; management hinting CMD corridor likely too conservative
Call / Filing Signal: 4/5 — DRAM “perfect storm” characterization, CMD revision signal, and customer LTA visibility commentary are substantive; explicit ASP/throughput correlation confirmation for 3800F is a new disclosure
Stock Reaction Fit: 3/5 — Stock down ~5.4% on a genuine beat-and-raise; the selloff is mechanically explained (Q2 GM guide 51-52% + elevated setup from prior-day run-up), but the magnitude of the down move relative to the quality of the quarter suggests the market is penalizing near-term margin optics more than fundamentals warrant
Overall read: Mixed Positive — Genuinely good quarter with a strong guide raise; the stock reaction is a Q2 margin optics problem, not a thesis problem — but the down move is real and the near-term GM trajectory is now the market’s focal point.
1. Setup Into the Print
The setup into Q1 2026 was favorable but not aggressive. ASML entered the quarter having rallied approximately 35% from its H1 2025 lows (~$1,100-1,200) on expectations of cycle recovery, but remained well below its pre-Q3-2024-earnings peak. Key investor debates heading into Q1:
What the market was focused on:
Immersion supply chain recovery: Q4 2025 call flagged a supply chain constraint limiting DUV immersion output in 2026 — this was the key downside risk to the FY2026 guide. Investors wanted to see resolution.
Gross margin trajectory: FY2025 averaged 52.8% — management guided FY2026 at 51-53%, implying at best flat, at worst margin compression. Q1 was expected to land at the low end (~51%) given NXE:3600D deliveries still in the mix and early High NA units diluting.
Demand durability: The FY2026 guidance reinstated in Q3 2025 was deliberately conservative (€30-35B vs. CMD targets of €44-60B by 2030). The question was whether the AI-driven demand recovery was real and durable or another pause followed by a cycle turn.
China policy tail risk: With ongoing Dutch/US export control discussions, any incremental restriction on DUV services or immersion tools would reprice the China risk premium.
The bar: Beat the implied Q1 run-rate of the €30-35B guide (approximately €7.5-8.0B), land GM above 51%, and provide some positive signal on demand durability. At ~$1,440 pre-earnings, ASML was not pricing a blowout — but the stock had been bid up sufficiently that an in-line print would not have been rewarded.
2. What Actually Happened
Headline Financials (Q1 2026 vs. Prior Quarters)
Key KPIs and Mix
EUV system sales: >€4.1B (includes 2 High NA units); roughly 65% of net system sales
Non-EUV system sales: >€2.1B — management called this out as a positive surprise, recovering vs. prior concerns
Logic/Memory split: 49% Logic / 51% Memory — Memory overtook Logic in Q1, reflecting the DRAM EUV adoption surge
IBM above guidance: Guided €2.3-2.4B (implied); delivered €2.487B, +16.6% QoQ despite Q1 being typically seasonally softer
Cash and ST investments: €8.4B (€7,970.4M cash + €405.9M ST investments)
Free cash flow: -€2.6B (operating -€2.19B + capex -€0.42B) — entirely driven by working capital timing (large customer payment outflows post-Q4 cash build)
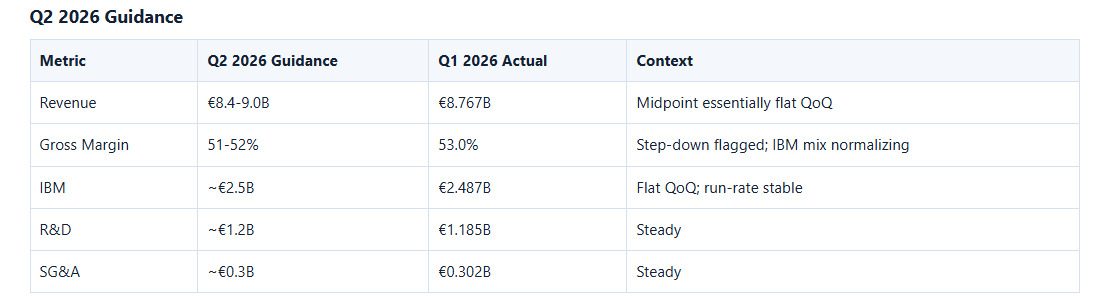
Q2 2026 Guidance
FY 2026 Updated Guidance
Revenue: €36-40B (raised from €30-35B; midpoint +€5.5B, +17%)
Gross margin: 51-53% (unchanged)
Revenue weighted to H2
3. What Was New This Quarter
1. Revenue guidance raise — the single most important development.
FY2026 raised to €36-40B from €30-35B. This is not a minor revision — at the midpoint, estimates move up €5.5B (~17%). The raise was driven by two distinct improvements: (a) immersion supply chain resolution (management had explicitly flagged DUV immersion as constrained at Q4 2025; that constraint is now cleared, adding non-China DUV demand), and (b) EUV can also deliver “a bit more” per management. China revenue remains capped at ~20% of midpoint — the incremental is entirely non-China.
2. Immersion supply chain resolution.
This was the key bear overhang from Q4 2025. Management now believes immersion can get “close to the levels that we had last year [2025]” — a material recovery from the Q4 2025 framing where management explicitly doubted this was achievable. The incremental immersion volume flows to non-Chinese customers, which have higher ASPs and better margin profiles than the China immersion mix.
3. 2027 EUV capacity raised to “at least 80” Low NA units.
2026 target remains at least 60 units. Management is now committing to the supply chain and manufacturing scale-up necessary for 80+ units in 2027. Critically, the “at least” framing means discussions are still ongoing and the number could move higher. 80 units in 2027 vs. 44 in 2025 = 82% increase in two years. But with productivity improvements (230 wph on the E-model vs. ~220 before, and 260 wph on the F-model beginning in 2027), the wafer capacity increase is even larger — Roger made the explicit statement that 80 tools at 2027 productivity specifications delivers “double, double the wafer per hour capacity” vs. 2025’s 44 tools.
4. ASP improvement for 2027 explicitly confirmed.
Roger confirmed: “clearly, the ASP next year will improve over this year.” Drivers: no NXE:3600D in 2027 (~€200M ASP), the lion’s share remains NXE:3800E at the higher 230 wph spec, and a “clear minority” will be NXE:3800F (first year; 260 wph → likely €350-400M ASP range based on throughput/ASP correlation Roger referenced). This is a concrete, unambiguous statement that per-unit EUV revenue will be higher in 2027.
5. DRAM characterized as “perfect storm” for ASML.
Capacity build + simultaneous EUV layer adoption (Low NA EUV is reducing multi-patterning, freeing fab space, and increasing litho intensity per capacity added) = demand compounding. Management noted that “US DRAM customer” (Micron) also announced a shift toward EUV. Memory at 51% of system sales in Q1 — this is historically high and reflects the DRAM tailwind.
6. CMD November 2024 numbers signaled for upward revision.
Management directly said the 160K wafers/month/year DRAM capacity addition assumption from CMD is “most probably above the number we have discussed at least this year” — and will be formally updated at the next Capital Markets Day (expected ~2027). This is as close as ASML gets to signaling that the FY2030 corridor of €44-60B may need to move. The company stopped short of saying which direction, but the context (AI-driven DRAM acceleration, customers “doing extremely well” on memory pricing) implies upward revision.
7. High NA operational milestones — customers testing on product wafers.
Over 0.5 million wafers processed; 80%+ availability. Multiple Logic and DRAM customers are now testing High NA on actual product wafers (not just process development). For DRAM specifically, Christophe noted that “the threshold to start using High NA on existing product is pretty low,” suggesting earlier-than-expected HVM qualification could occur. This is a 2027-2028 event at minimum, but the product wafer testing milestone is new vs. prior calls.
8. NXE:3800F specification raised to 260 wph (from 250).
A 4% throughput improvement at the spec level before the tool even ships. Shipping in 2027, full volume 2028. Combined with Roger’s explicit ASP-to-throughput correlation commentary, this suggests NXE:3800F ASP will be correspondingly higher than originally modeled.
4. Why the Stock Moved
The stock is down ~5.4% from the prior close ($1,518.30 → $1,437). This is a “sell the news” reaction on a genuine beat-and-raise — and it deserves an explanation.
Context: the stock had pre-run into earnings on anticipation, not preliminary results. ASML reported Q1 2026 results pre-market on April 15 (before the 9 AM ET call). The April 14 close of $1,518.30 reflects pre-earnings positioning — the stock gapped up to $1,526 at the April 14 open (from $1,500 on April 13) and closed at $1,518, all before any results were published. By the time ASML’s pre-market press release hit on April 15, the elevated setup meant the Q2 GM guide of 51-52% had a high bar to clear. It didn’t — and the stock opened down 3% at $1,473 before the formal call even began.
Primary driver of the selloff — Q2 gross margin guide at 51-52%. The formal call on April 15 introduced the Q2 guidance, which the market had not yet priced. Q2 GM at 51-52% is a 100-200bps step-down from Q1’s 53%. The market’s interpretation: Q1’s 53% was a mix anomaly (unusually high-margin software-based IBM upgrades), not a structural floor. The setup coming into the call had effectively priced a continuation of Q1 momentum; Q2 guidance revised that expectation sharply lower on margins, driving the gap-down open at $1,473 and continued selling to $1,437.
Secondary factor — elevated setup absorbed the beat. The pre-earnings rally from ~$1,478 on April 10 to $1,518 on April 14 (+2.7% over two sessions) meant the stock entered results day with a demanding entry price. The revenue beat and FY2026 raise were genuinely good, but they were not materially above what the pre-run had already priced. Without a positive surprise large enough to re-rate from the elevated base — and with the Q2 GM guide actively disappointing — there was no catalyst to push higher. The path of least resistance was lower through the session.
Was the selloff warranted? Partially. The Q2 GM step-down is real and explained (IBM mix normalization + ramp cost headcount), but the magnitude of the down move relative to the quality of the underlying quarter and the scale of the guidance raise looks excessive. At $1,437, the stock has effectively reversed the entire preliminary-results gain and is now trading as if the Q2 margin guide were more informative than the FY2026 revenue raise — which is a debatable prioritization. The guidance raise is structural; the Q2 GM step-down is one quarter of mix normalization.
The market may have focused on the wrong thing. The FY2026 guide raise from €32.5B to €38B midpoint is a €5.5B increase — structurally far more significant than a one-quarter GM dip. If the selloff holds, it creates a potential re-entry point for investors who believe the thesis (the GM air pocket in Q2 is temporary; FY2026 and FY2027 revenue and earnings power are both revised higher).
5. What the Market May Be Missing
5a. The Q1 IBM Quality Signal Is More Important Than the Q2 Dip
Management described Q1 IBM outperformance as driven by “very high margin components within our Installed Base business” — specifically software-based upgrades that provide near-instantaneous capacity delivery to customers. The market is focusing on the Q2 step-down as a mean-reversion story. The more interesting read is structural: ASML is developing an increasingly software-intensive layer within IBM where upgrades are delivered via software switches with near-zero incremental cost. These upgrades carry dramatically higher gross margins than hardware-intensive services. As the EUV installed base grows toward 400-500 tools by 2030, the volume of software-upgradeable capacity improvements available to ASML’s customers grows commensurately. The Q1 mix anomaly is a preview of what IBM’s long-run gross margin profile could look like — not a one-quarter distortion to be discounted.
5b. The Working Capital Movement Is a Seasonal Reversal, Not Cash Burn
The -€2.6B FCF and -€5.2B working capital outflow will generate sell-side commentary. The correct interpretation requires understanding what actually drove the number — two items account for nearly the entire outflow:
1. Current liabilities fell €3,976M (77% of the outflow). In Q4 2025, current liabilities surged from €19.2B to €24.3B — a +€5.1B spike driven almost entirely by customer advance payments received at year-end for 2026 tool deliveries. Q1 2026 is the mechanical reversal: ASML executes on those commitments by delivering tools (reducing deferred revenue), paying suppliers (drawing down the advance payment liability), and completing service milestones. The current liabilities contraction is not cash leaving the business permanently — it is the settlement of obligations already on the balance sheet in Q4.
2. Accounts receivable rose €1,380M (27% of the outflow). Q1 2026 tools were delivered and invoiced, but customers haven’t yet paid. This converts to cash in Q2 as payment terms are settled — again, not a burn signal, a timing signal.
Everything else — inventories +€282M (H2 build-up), contract assets +€103M, non-current contract liabilities +€219M — is noise relative to these two items. The actual balance sheet reconciliation of working capital changes sums to approximately -€5.6B, consistent with the -€5.2B in the cash flow statement (difference from FX and non-captured items).
ASML’s Q1 FCF is structurally negative for the same reason every year: Q4 collects year-end advance payments, Q1 executes on them. Q1 2025 operating cash flow was -€59M (confirmed in financial statements). The -€2.6B this year is substantially larger than Q1 2025’s -€59M because the Q4 2025 advance payment intake was far bigger — current liabilities surged +€5.1B in Q4 2025 vs. a much smaller seasonal build in prior years. The larger outflow is a function of greater demand, not deteriorating cash quality.
5c. The CMD Signal Is Underpriced
Management said at the call that the November 2024 CMD assumptions are being revisited because “a lot has changed.” The specific example given was DRAM capacity additions running above the CMD model. The November 2024 CMD presented a corridor of €44-60B revenue and 56-60% GM by 2030. If the CMD DRAM assumption was, for example, 160K wafers/month/year in capacity additions, and the actual 2026 trajectory is above that, the entire revenue corridor shifts upward. The stock today is being valued against the old CMD corridor. The 2027 CMD update is likely to move the low end of the corridor upward — potentially making the stock’s current price look less expensive against the revised long-term scenario. The market has not yet priced this because the CMD update has not occurred, but the setup is building.
6. Call / Filing Nuggets That Matter
From the transcript:
Christophe on DRAM litho intensity: “DRAM has been a bit the perfect storm for ASML, because of course, we have this capacity build up. But as we mentioned a few times, we have seen a major adoption of EUV in DRAM in 2025. And you may have noticed that our US DRAM customer also made this announcement that they were shifting also pretty strongly on EUV.” — This is not boilerplate. Micron explicitly highlighted EUV adoption in their own earnings call. ASML has both a volume driver (capacity build) and an intensity driver (EUV layers per unit of capacity) compounding simultaneously in DRAM.
Roger confirming immersion will scale with EUV (non-China): “For non-Chinese customers, the demand on immersion will scale with the demand for EUV because, as you know, there is a pretty clear relationship between the two.” — This is the single most important line for the non-China DUV revenue model. Immersion was previously modeled as flat or declining outside China; this confirms it grows with EUV demand.
Roger on 80 Low NA EUV at 2027 productivity = 2× the capacity of 2025’s 44 tools: This is a critical reframe. The market debates the “at least 80” unit number. Roger redirected the discussion to wafer-hours per year: 80 tools at 230 wph = roughly double the total wafer-hours shipped in 2025 at 44 tools × ~220 wph. Revenue grows with units × ASP; effective lithography capacity for customers grows even faster. This asymmetry will sustain demand ahead of ASML’s supply throughout 2027.
On pricing model: Christophe explicitly rejected “opportunistic pricing” during tight market conditions — “Our model of pricing is not based on the squeeze that our customers find themselves in.” This is positive for customer relations durability but means gross margin improvement must come from mix and productivity, not price leverage in tight markets.
On China: “China remains at the midpoint, around 20%.” Unchanged. The guidance raise is entirely non-China.
On customer cleanroom constraints: Management said Q4 2025 flagged cleanroom capacity as a key constraint; Q1 2026 showed that “plans for 2026 are really solidifying” with more clarity on pedestal availability timing. This reduces the cleanroom bottleneck risk for 2026 deliveries.
Equity method income jumped: €104.6M in Q1 2026 vs. €16.0M in Q4 2025 and €33.0M in Q1 2025. This is mostly Carl Zeiss SMT (ASML ~25% stake). The spike likely reflects CZS profitability as optics output ramps alongside ASML’s own EUV ramp — a secondary positive signal on supply chain health.
From the financial statements:
SBC notably lower this quarter: €31.1M vs. €55.6M in Q4 2025 and €40.0M in Q1 2025. Q1 is typically a low SBC quarter due to award timing, but the YoY decline is notable. This slightly improves the quality of the EPS beat.
Net income includes €104.6M equity method profit that is non-cash. “Income after income taxes” (the purer operational measure) was €2,652.1M vs. €2,322.0M in Q1 2025 = +14.2% YoY — still strong, but slightly below the headline +17.1% growth in reported net income. The equity method gain amplified the headline number.
Long-term debt essentially unchanged at €2.7B despite €692.9M debt repayment in financing activities: There were zero new debt issuances in Q1 (CF shows €0 proceeds from borrowings), so this is not a refinancing. The repayment almost certainly covered the current-portion of long-term debt that was sitting in current liabilities on the Q4 2025 balance sheet — part of the -€3,976M current liabilities decline. The LT debt balance barely moved because the maturing tranche was already classified as current, not long-term. Net leverage remains conservative at ~€5.7B net cash.
Shareholders’ equity growing strongly: €20.8B vs. €19.6B at year-end, despite €1.0B buybacks and €617M dividends in Q1. Driven entirely by earnings retention. ASML is self-funding its shareholder returns and capacity build simultaneously — no equity dilution required.
7. 2nd-Order Implications
For the next quarter (Q2 2026):
The Q2 GM guide of 51-52% is the immediate overhang. If Q2 GM comes in at the high end of the 51-52% range (52%), the full-year average would need to average ~52.5% to hit the 51-53% corridor’s midpoint — implying H2 improvement, consistent with volume leverage as revenue ramps. Any Q2 GM upside vs. the 51-52% guide would be the most important near-term bullish signal. The low Q2 GM will generate sell-side downgrades to near-term EBIT vs. Q1 run-rate — but this is known and priced.
For FY2026 margin trajectory:
The FY2026 GM guidance maintained at 51-53% despite a Q1 beat at 53% is a deliberate signal that the full-year average will be below Q1. The logic is: (1) Q1 IBM mix was unusually high-margin; (2) ramp costs are rising (headcount for the move-rate increase); (3) High NA units (EXE:5200) in H2 are near-zero or negative margin near-term. The honest read: FY2026 GM will likely average 52.0-52.5%, with Q1 a high-water mark and Q3-Q4 recovering as volume leverage improves.
For FY2027 revenue and earnings:
The explicit confirmation of (a) 80+ Low NA EUV units, (b) ASP improvement from mix shift (no 3600D, F-model introduction), and (c) non-EUV scaling with EUV demand creates a FY2027 framework that is materially above the prior base. Using rough math: 80 units × improved blended ASP + IBM compounding at 20%+ YoY + immersion scaling = FY2027 revenue likely €42-48B. Consensus is probably still anchored to the old CMD corridor’s lower range. Post-Q1 estimate revisions will be substantial.
For the IBM compounding thesis:
IBM grew +24.3% YoY in Q1 2026, reaching an annualized run rate of €9.95B. The internal thesis of 18-20% annual IBM growth is being validated — in fact, IBM is growing faster than modeled. At this rate, the FY2026 IBM full-year total could reach €10.0-10.5B vs. €8.2B in FY2025. The market’s consensus IBM model for FY2030 (~€12-15B) continues to look understated if the current trajectory holds.
For the gross margin expansion path (FY2027-2030):
The NXE:3800F at 260 wph shipping in 2027 creates a compounding mix tailwind: each F-model shipped in 2027 is both higher ASP than an E and carries better gross margin than the 3600D/older systems it replaces. The EUV gross margin expansion path from ~51-53% today to management’s 56-60% target by 2030 requires: (1) F-model volume, (2) High NA scaling toward profitability (EXE:5200B), and (3) IBM mix shift toward software upgrades. All three are now actively in motion.
For competitive dynamics:
Roger noted that Samsung and Intel are both investing in advanced foundry capacity, with Samsung’s Texas fab (Taylor) explicitly called out. Multiple advanced foundry players is “good for the ecosystem” — and directly good for ASML since all of them require EUV. A two-node foundry world (TSMC dominant, Samsung catching up, Intel rebuilding) creates broader demand for the tools than a single-customer foundry scenario.
For the export control tail risk:
Management explicitly stated the guidance bandwidth “accommodates potential outcomes of ongoing discussions around export control.” This is ASML’s formal hedge — the €36-40B range includes scenarios where additional restrictions emerge. At the low end (€36B), some China DUV service restriction is plausibly priced. At the high end (€40B), China restrictions are absent. The midpoint (€38B) likely assumes no incremental DUV restrictions but no expansion either.
8. What Matters Next
Before Q2 2026 earnings (~mid-July 2026):
Q2 2026 gross margin vs. 51-52% guidance. This is the single highest-priority watch item. The market has accepted that Q1’s 53% included a mix benefit; if Q2 prints at the high end of 51-52% (i.e., 52%), the full-year GM path is intact. If Q2 comes in at 51%, there will be questions about whether the FY2026 GM can average 52%+ — which was the implicit bar set by the Q1 beat. The IBM upgrade mix within Q2 is the key variable (management said upgrade business continues in Q2, just at a less favorable mix than Q1).
Revenue acceleration toward FY2026 midpoint. Q1 at €8.77B and Q2 guided at €8.4-9.0B midpoint (€8.7B) means Q3+Q4 need to average €10.2-10.4B to hit the FY midpoint of €38B. Watch for any Q2 call signals about H2 delivery cadence — specifically, are NXE:3800E units being front-loaded or back-loaded into Q3 vs. Q4.
High NA customer progress signals. Christophe said Logic and DRAM customers are testing High NA on product wafers now. Watch for any customer disclosure (TSMC, Samsung, or Micron investor calls) confirming High NA production layer decisions — this would be the earliest signal of an EXE:5000/5200B HVM timeline compression.
China policy developments (Dutch government / US BIS). ASML’s guidance range explicitly accounts for export control outcomes. Between now and Q2, any Dutch government announcement on DUV service contract restrictions or additional entity list additions would immediately reprice the €36B low-end scenario. Monitor closely.
Micron and SK Hynix CapEx commentary. DRAM customers are ASML’s fastest-growing demand segment. Any DRAM customer CapEx guidance cut (economic slowdown, memory price reversal) would be the leading warning for ASML’s FY2027 memory demand. Current signal is strongly positive (both customers described as “sold out for the rest of the year” with supply limitations expected beyond 2026).
ASML capacity ramp progress (immersion + EUV move rate). Management said the immersion supply chain is now able to support near-2025 volumes but it is “close to” not “at” that level. Any supply chain disruption at Zeiss or in DUV assembly would be the first negative signal vs. the guide raise narrative.
2027 CMD timing and preliminary signals. The next Capital Markets Day will update the long-term model. Even ahead of the CMD, any interim analyst day presentations or conference participation by Christophe or Roger that touches on the 2030 corridor would be noteworthy given the guidance that the CMD numbers need updating.
9. Bottom-Line Analyst View
The thesis got stronger this quarter, not just maintained. The three pillars — IBM compounding, gross margin expansion path, and demand durability — all moved in the right direction:
IBM at +24% YoY with a structural mix upgrade (software-based upgrades accelerating) is growing faster than the base model assumed
The FY2026 guide raise eliminates the key bear scenario (€30-35B guidance tracking disappointingly vs. the CMD corridor) and restores the long-run trajectory toward the CMD range
DRAM becoming a co-equal demand driver with logic (Memory at 51% of Q1 system sales) adds cycle resilience — ASML is no longer predominantly exposed to a single foundry customer’s build cycle
The one genuine concern is gross margin. The Q2 guide at 51-52% — below Q1’s 53% — is explained (IBM mix normalization + ramp costs), and FY2026 guidance maintained at 51-53% means the average is probably 52-52.5% rather than the 53%+ that Q1 implied. For the 56-60% FY2030 target to be credible, ASML needs GM to demonstrate continued sequential progress after the Q2 air pocket. A single quarter at 53% surrounded by 51-52% quarters is not a structural inflection; it’s confirmation that the inflection is still ahead of us, not behind.
The stock reaction is arguably too harsh. The -5.4% selloff reverses the entire preliminary-results gain on a quarter where revenue, IBM, gross margin, and full-year guidance all improved. The market is treating the Q2 GM step-down as the primary signal and discounting the FY2026 revenue raise — which is the inverse of what the fundamentals warrant. That said, without quarterly bookings data as a confidence mechanism, and with the stock entering the day extended, the selling is mechanically understandable even if it is analytically excessive.
The highest-conviction takeaway from the quarter: ASML is confirming that the AI-driven semiconductor capacity cycle is not a single-vector event. It is simultaneously (1) driving advanced logic EUV demand at TSMC/Samsung, (2) accelerating DRAM EUV adoption as litho intensity increases, AND (3) creating a productivity upgrade cycle in the installed base as customers need maximum output from existing tools. Three independent demand channels for the same monopoly franchise, all accelerating simultaneously — and the company cannot build the tools fast enough to satisfy demand. That is the investment case in one quarter.
10. Quick Take
Quarter in one line: Revenue +13% YoY, IBM +24%, FY2026 raised €5.5B at midpoint — a genuine beat-and-raise on every metric that matters
Stock move in one line: Down ~5.4% from prior close because pre-earnings positioning had driven the stock to $1,518 heading into results, and the Q2 GM guide of 51-52% in the pre-market press release disappointed before the formal call even started
What matters now: Whether Q2 gross margin lands at the high or low end of the 51-52% guidance range — a Q2 print at 52% keeps the FY2026 average on track and closes the selloff narrative; a print at 51% reopens the structural GM debate
try this for automatic pulls from edgar - https://github.com/stefanoamorelli/sec-edgar-mcp
Good takes. Although I don’t think the Q2 guidance played a big role. Europe shares went up this morning and sell off started right before earning call. If Q2 guide is the issue then the sell off would have likely started earlier. Might be US based funds starting to offload the stock.